News

Exclusive analysis articles with the latest market updates, and real-time news feeds.
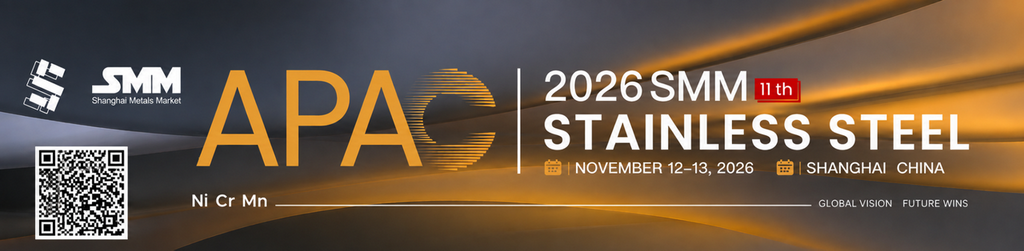
SMM to Host  SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event , Shanghai, Nov. 12–13
SMM to Host SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event , Shanghai, Nov. 12–13
Introduction [Shanghai, China] - Building on the success of its previous 10 sessions, the SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event will be held in Shanghai this November 12-13. [Scale] - Over 300+ delegates and 40+ speakers from 20+ countries will attend. [Agenda] - https://ni-cr-stainlesssteelapac.metal.com/home?fromId=265accf08c&from=58 Background: In 2026, the stainless steel market emerged from a trough. Driven by China’s anti-involution policies and expectations of nickel raw material shortages under Indonesian policies, the industry broke free from a three-year downturn, with prices rising rapidly. Stainless steel enterprises adjusted their nickel raw material ratios, leveraging the economic advantages of stainless steel scrap to expand its substitution share and gradually escape losses. However, the industry remained constrained by factors such as compliance restrictions on stainless steel scrap tax invoices and declining NPI grades, while demand for nickel replenishment further boosted the use of high-grade nickel, making structural issues increasingly prominent. On the raw material side, the nickel industry chain underwent a fundamental pattern shift in 2026, with industry logic moving from oversupply to a long-term tight balance constrained by resources and power. Market divergence intensified, and fluctuations across the industry chain became pronounced. The tightening of Indonesia’s RKAB quotas, the HPM policy driving up ore prices, and the crowding out of power supply by aluminum reversed the growth trajectory of smelting costs and supply in both China and Indonesia. Nickel prices rose in a stepwise manner in H1, with supply-demand and cost factors providing strong price support. The global ferrochrome market continued its trend of shifting eastward. China’s ferrochrome production grew steadily, maintaining the top position globally, while South Africa resumed production comprehensively with policy support. Multiple growth drivers pushed ferrochrome supply toward a surplus. The chrome ore market, supported by Middle East conflicts, saw short-term sharp price spikes; high imports pushed port ore inventory above 5 million mt, leaving spot cargo in clear surplus and prices on a downward trajectory. Increased policy uncertainty around South African mining pushed the ferrochrome market into a new cycle of supply-demand pattern adjustment. The manganese industry chain experienced significant divergence in 2026, with industry dynamics shifting from a single supply-demand game to a split pattern driven by dual demand from stainless steel and lithium batteries. Manganese ore capacity remained ample throughout the year, while production cuts in smelting and high raw material prices formed strong cost support, limiting the room for deep price declines. On the demand side, differentiation was evident: SiMn continued to replace EMM; trends in lithium-battery manganese materials diverged, with manganese sulphate receiving periodic market support while Mn3O4 terminal demand weakened under pressure. Multiple factors drove structural fluctuations, making Q4 a critical planning window for enterprise purchasing and production schedules. Currently, global nickel, ferrochrome, manganese, and stainless steel markets are intertwined with multiple variables including mining policies, energy, and downstream demand, resulting in notably wider price fluctuations. Q4 coincides with a critical period for enterprises formulating their production, procurement, and hedging plans for the following year. SMM will hold the SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event in Shanghai from November 12-13, 2026, inviting global stakeholders in the nickel, chromium, manganese and stainless steel industry to deeply explore hot topics such as the latest market policies, global market development, and hedging strategies with derivatives. This industry conference will bring together practitioners from the entire industry chain including miners, smelters, stainless steel mills and traders to conduct in-depth discussions on core topics such as Indonesian policies, nickel, chromium and manganese market price trends, raw material substitution, and medium and long-term supply-demand, breaking down upstream and downstream information barriers and providing reference for industry business decisions. Highlights: Co-located with Commodity Week, Comprehensive Coverage of Non-Ferrous Metals, Energy, Chemicals and Other Diverse Sectors 10+ International Associations Engaging in In-Depth Discussions on Policies, Methods and Market Global experts from 20+ countries/regions are brought together to adopt an international perspective and explore global opportunities. The latest strategies combine physical and futures markets to unlock new approaches to hedging. Exclusive 1-on-1 meeting platform: chat online and meet offline directly. Government & Policy Authorities & Industry Association: National Economic Council Republic of Indonesia | Asosiasi Penambang Nikel Indonesia (APNI) | Forum Industri Nikel Indonesia (FINI) | Indian Stainless Steel Development Association (ISSDA) | International Nickel Study Group | Nickel Institute | Shanghai OTC Commodity Derivatives Association | Internation Manangese Institute (IMnI) Agenda: Time Agenda 08:30-9:30 Sign in 9:30 - 9:40 Opening Ceremony 9:40 - 10:00 [Keynote Speech] Understanding Indonesia's Nickel Policy Shifts: Ensuring Orderly Market Development 10:00 - 10:30 [Keynote Speech] The New Global Nickel Landscape: Indonesia’s HPM Policy Revisions and the Reshaping of Price Benchmarks 10:30 - 10:50 [Keynote Speech] Indonesia's NPI New Export Policy and Protection of Smelter Interests 10:50- 11:00 Coffee Break 11:00 - 11:30 [Keynote Speech] The Global Landscape of Nickel 11:30- 12:00 [Keynote Speech] How NPI Calendar Spread Contracts Are Driving the Derivatives Trading Space 12:00 - 13:30 Lunch 13:30 - 14:20 [Panel Discussion] Who will Control the Pricing Power in the Global Nickel Market Amid Policy Shifts? 14:20 - 14:40 [Keynote Speech] Global Nickel Market Outlook 14:40 - 15:00 [Keynote Speech] Give Full Play to the Functions of the Futures Market and Promote the High-quality Development and Internationalization of the Nickel Industry 15:00 - 15:20 [Keynote Speech] Sustainability Requirements and Standards for the Nickel Industry 15:20- 15:40 Coffee Break 15:40 - 16:40 [Panel Discussion] Exchange-Traded Derivatives Trading Pathways-How to Rebuild Risk Management Systems amid Geopolitical Disturbances and Enhance Contract Pricing Value 16:40 - 17:00 Logistics and Supply Chain Collaboration Help the Industry Develop Efficiently 18.00-20.00 Banquet Dinner 09:00 -09:15 [Keynote Speech] The Nickel Ore Equation: Indonesia's Policy Stack, the HPM Gap, and the Making of a Structural Tight Balance 09:15 - 09:30 [Keynote Speech] Competitiveness and Pricing Logic of NPI Under the Adjustment of Stainless Steel Raw Material Structure 09:30-09:45 [Keynote Speech] Short-term Cost Support and Long-term Supply Release: Outlook for the Nickel Intermediate and Nickel Sulfate Market 09:45 - 10:00 [Keynote Speech] Cost Support and the Shifting Center of Gravity for Nickel Prices Amid Oversupply 10:00-10:15 [Keynote Speech] Analysis of Supply and Demand Game of Global Molybdenum Market and Mid- to Long-term Market Forecast 10:15-10:30 [Keynote Speech] Africa's Chromium Industry: Policy and Development Insights 10:30- 10:50 Coffee Break 10:50 - 11:20 [Keynote Speech] China Ferrochrome Supply-Demand Balance and Outlook 11:20-11:40 [Keynote Speech] Development Status of China's Stainless Steel Industry 11:40 - 12:00 [Keynote Speech] Global Stainless Trade Under Policy: From CBAM to Quotas, a Two-Front View of Europe and Southeast Asia 12:00 - 13:30 Lunch 13:30 - 13:50 [Keynote Speech] Trends, Challenges, and Future Outlook of Demand and Supply in the Japanese Stainless Steel Industry 13:50 - 14:10 Driving the Next Stainless Steel Growth Cycle: India’s Infrastructure Boom, Decarbonization, and Global Supply Chain Synergies 14:10 - 14:30 [Keynote Speech] European Stainless Steel Market Development and Trade Flow Analysis 14:30 - 14:50 [Keynote Speech] New Energy Batteries – Emerging Opportunities for Stainless Steel 14:50 - 15:10 [Keynote Speech] New Applications and Developments in the Stainless Steel Market 15:10-15:30 [Keynote Speech] Current Development and Industrial Distribution of the High-End Stainless Steel Fastener Industry Conference Ends
15 hours ago
Copper Prices Rebound Sharply: Bad News Fully Priced In, or Fundamentals Reasserting Themselves?
As September got underway, copper prices did not extend their decline after the US Federal Reserve delivered its rate hike. Instead, they rebounded quickly following a brief period of pressure. SHFE copper returned to elevated levels, while LME copper again approached its previous highs. The swift rebound cannot be explained by macro expectations alone. More precisely, the full pricing-in of the rate hike and subsequent short covering served as the immediate catalysts, while deeply negative treatment charges (TCs) for imported copper concentrates, more extensive smelter maintenance and a sharp decline in China’s social inventories of refined copper provided the fundamental underpinning. Persistent Raw-Material Tightness and Frequent Smelter Maintenance Keep Supply Constrained On September 18, the SMM Imported Copper Concentrate Index stood at -$221.89 per dry metric tonne, down another $12.19 per dry metric tonne from the previous reading and marking a fresh record low. Processing charges for copper anode are also at historically low levels, reflecting continued tightness in copper anode supply. Meanwhile, sulphuric acid prices have declined for around two and a half consecutive months, steadily eroding smelters’ by-product earnings and adding to operating pressure across the smelting sector. Several Chinese copper smelters are scheduled to undergo maintenance in October and November. With the availability of supplementary cold-feed materials constrained, raw-material bottlenecks are creating downside risks to refined copper output. Market sources indicate that some smelters have already signalled an intention to cut production and have notified customers that deliveries under long-term contracts will be reduced, although the scale of the reductions has yet to be specified. SMM will continue to monitor the execution of planned maintenance, the scope of actual production cuts and the marginal impact of sulphuric acid prices on smelter operating rates. Based on the maintenance schedule, the intensity of copper smelter maintenance in the second quarter of 2026 was notably higher than in 2025. Metric 2025 2026 Change Maintenance events 30 38 Up 8, or 26.7% Average maintenance duration 33.8 days 35.2 days Up 1.4 days Maintenance lasting 40 days or more 7 14 Doubled Maintenance lasting 60 days or more 2 5 Up 3 The number of maintenance events scheduled for the full year increased from 30 to 38, while long-duration maintenance lasting 40 days or more rose from seven events to 14. In terms of timing, the maintenance peak shifted from April–May in 2025 to March–June in 2026, with a second wave of concentrated maintenance still scheduled for October–November. Based on currently available data, the combined realised and anticipated output losses in 2026 already slightly exceed the actual impact recorded in 2025. As estimates have yet to be disclosed for some upcoming maintenance events, the overall disruption to refined copper supply from smelter maintenance is expected to be greater in 2026 than in 2025. Rapid Inventory Draws Shift the Market from Contango to Backwardation Inventory movements have been the clearest fundamental signal behind the latest rebound in copper prices. Around the 2026 Chinese New Year holiday, China’s social inventories of refined copper accumulated rapidly, at one point reaching approximately 570,000–580,000 mt. Inventories declined steadily after the holiday, falling to around 200,000 mt by Week 25. The drawdown accelerated further in the third quarter, with stocks dropping to roughly 90,000 mt in Weeks 36–37. Compared with the same period in previous years, current inventories are not only significantly below their 2024 and 2025 levels but are also approaching the seasonal lows seen in recent years. From the year’s peak, domestic social inventories have declined by nearly 500,000 mt, a drop of more than 80%. This means that the market’s inventory buffer has thinned considerably. When inventories are high, fluctuations of several tens of thousands of tonnes in arrivals or consumption may not be enough to alter the physical market structure. Once inventories fall to low levels, however, delayed imports, reduced smelter deliveries or periodic restocking by downstream producers can quickly amplify tightness in the physical market. The shift in the market structure from contango to backwardation is precisely how these low inventories have been reflected in the futures market. As immediately available physical supply declines, nearby contracts command a higher premium over forward contracts, sellers become more inclined to hold firm on offers and nearby spreads widen accordingly. In other words, backwardation is not an independent driver of the current copper rally. Rather, it is the result of low inventories and tight physical supply, while also reinforcing expectations of near-term supply tightness. It is important to note that falling inventories should not simply be equated with a sharp increase in end-user demand. The rapid drawdown in Chinese inventories reflects not only support from consumption but also the pull of copper units into the US market, import losses, the timing of cargo arrivals and smelter maintenance. A more accurate characterisation of the current physical tightness would therefore be that demand has not weakened materially, while supply replenishment has not arrived quickly enough, resulting in a rapid decline in readily available inventories. Outlook: Copper Prices Remain Supported, but Market Tensions May Shift at Elevated Levels In the short term, China’s social inventories remain low. With the National Day and Mid-Autumn Festival holidays approaching, downstream producers are also likely to restock in advance, lending continued support to spot premiums and nearby backwardation. At the same time, however, the COMEX-LME ( C/L) spread has turned slightly negative, and the cross-market arbitrage window for shipping copper to the US has largely closed. Global copper flows may therefore begin to shift, creating potential supply pressure in China’s physical market. First, changes in the C/L spread and the potential return of overseas cargoes. The C/L spread has continued to narrow from its earlier highs and has now moved slightly into negative territory, indicating that the US market’s price incentive for overseas copper units has weakened significantly. If this negative spread persists, incremental cargoes that had previously flowed to the US may be redirected to China and other Asian markets. Chinese import arrivals could consequently increase, placing pressure on spot premiums and backwardation. However, trade negotiations, contract signing, loading, vessel diversions and shipping all involve time lags. Any redirection of cargoes will therefore not be reflected immediately in domestic inventories; its impact is more likely to become visible later through import arrivals and changes in bonded-zone inventories. Conversely, if expectations of US tariffs on refined copper intensify again and the C/L spread widens, the pressure from returning cargoes may ease. Second, pre-holiday restocking and the performance of spot premiums. As the holidays approach, downstream producers will need to secure material in advance to cover production requirements and logistics schedules during the holiday period. Against a backdrop of low social inventories and limited immediately available supply, sellers are likely to hold firm on offers. Spot premiums may rise further, while nearby backwardation could deepen accordingly. However, pre-holiday restocking partly represents demand being brought forward. Once restocking is largely complete, high copper prices may curb downstream procurement and physical trading activity could cool rapidly. The sustainability of stronger pre-holiday premiums should therefore be assessed against actual transactions and post-holiday inventory movements. Third, imported copper concentrate TCs and the actual pace of smelter production cuts. TCs for imported copper concentrates are already deeply negative, and the economics of processing spot imported concentrates continue to deteriorate. Some smelters have consequently shown a stronger willingness to reduce production. The key question is whether these intentions will translate into actual output losses. If maintenance and operating-rate cuts broaden further, a contraction in Chinese refined copper supply would help offset the pressure from returning import cargoes. Conversely, if output recovers quickly once maintenance ends while overseas cargoes are simultaneously redirected to China, domestic supply pressure could rise markedly. Fourth, whether Chinese smelter output can recover. As maintenance at some smelters concludes, a rebound in refined copper production during the fourth quarter, combined with a concentrated increase in import arrivals, could cause domestic inventories to shift from destocking to stabilisation or even accumulation. Overall, pre-holiday restocking and low inventories should continue to support spot premiums in the near term. However, the negative C/L spread indicates that the US pull on global copper units has reached a potential inflection point. The market’s next key test is whether supply reductions at smelters can offset the return of import cargoes, and whether underlying consumption can continue to absorb high copper prices once concentrated pre-holiday restocking comes to an end.
Sep 18, 2026 17:56
[SMM Analysis] Lithium Battery Copper Foil: No Near-Term Supply Constraint, Structural Shortage Risks to Surface in 2027
[SMM Analysis] Lithium Battery Copper Foil: No Near-Term Supply Constraint, Structural Shortage Risks to Surface in 2027
Recently, news of tightening lithium battery copper foil supply has drawn attention from the industry and capital markets. Some worry that tight copper foil supply will immediately drag down battery capacity expansion and even affect end-user deliveries. In reality, however, the copper foil constraint will not materialize right away, and the real risk window may emerge next year. What is copper foil? Why is it so critical? Copper foil is the "conductive skeleton" of the lithium battery anode, an extremely thin copper film only a fraction of the thickness of a human hair. It accounts for a modest share of battery costs (about 10%-15%), but even slight quality fluctuations can affect battery yield and safety. More importantly, copper foil supply is not a case of "having capacity means having product"—a plant may plan annual production of 100,000 mt, but the volume that can actually pass battery maker certification and be supplied steadily is often discounted. The supply-demand gap does exist, but pressure is limited this year In 2026, China's lithium battery copper foil demand is about 1.37 million mt, while actual stable supply is about 1.35 million mt, leaving a gap of about 20,000 mt (corresponding to the copper foil raw material needed for about 50 GWh of lithium battery cells). Against an estimated global lithium battery cell production of about 3,400 GWh in 2026, this figure is not large, and in the short term battery makers can still buffer through inventory, adding suppliers, and adjusting production schedules. Therefore, copper foil will not become a hard constraint on lithium battery production increases this year; the impact will be seen more in tight production schedules at leading suppliers, greater difficulty in placing last-minute orders, and longer delivery cycles for certain specifications. Looking further ahead, however, pressure will rise: the gap in 2027 is about 40,000 mt (corresponding to the copper foil raw material needed for about 100 GWh of lithium battery cells), and it may continue to widen in 2028. Copper foil demand growth is outpacing supply growth, and the situation will tighten further over time. AI copper foil is "distracting" attention, but has not yet stolen the race Recently, AI servers and high-speed communications have been booming, and processing fees for high-end electronic copper foil have surged to 200,000-300,000 yuan/mt, nearly 10 times that of ordinary lithium battery copper foil. This will attract leading copper foil makers to shift capital and equipment toward high-end products, but such production lines have high technical barriers and long certification cycles, so they cannot be converted at scale in the short term. In other words, AI copper foil will not immediately crowd out lithium battery copper foil capacity, but it will raise the "opportunity cost" of lithium battery capacity expansion—when copper foil makers make new investments, they will prioritize the more profitable high-end electronic copper foil. Key judgment: this year can hold, next year depends on positioning The impact of copper foil shortages on the battery industry is progressive. Stage one (this year): inventory and flexible procurement can still hold. Battery makers generally have stockpiles and can also adjust through multiple suppliers, so short-term production increases will not be significantly constrained. Stage two (next year and beyond): if new capacity does not keep pace and long-term contracts are not locked in early, production may indeed be affected. New production line certification takes time, and once the gap widens, spot procurement will struggle to find stable supply sources, and certain specifications may see "capacity exists, but no spot cargo" situations. Stage three (long term): upstream and downstream will become deeply bound. CATL and partners such as Huike will jointly build 400,000 mt of copper foil capacity over the next three years, signaling that battery leaders are shifting from "annual tenders" to "direct participation in plant construction." In the future, battery makers wanting to secure supply will likely need to provide funds, orders, and joint R&D in advance. Conclusion The structural shortage of lithium battery copper foil is already established, but in the short term it will not significantly limit battery production increases, as enterprise inventory and procurement flexibility still provide buffer room. The real test will come in 2027 and beyond: if copper foil capacity expansion progress falls short of expectations and battery makers have not locked in long-term orders and capacity in advance, a tight balance of "orders but no materials" may emerge starting in H2 next year, thereby affecting production release. In summary, the copper foil supply constraint has not yet become the core contradiction this year, but it is shifting from an "option" to a "must-answer question." Battery makers that position long-term contracts and capacity binding in advance will gain a clear supply chain flexibility advantage next year.
Sep 16, 2026 15:18
Goldman keeps $5,400 gold forecast intact despite Fed hike
Goldman Sachs kept its end-2027 gold forecast at $5,400 an ounce despite this week's Fed hike, saying tighter policy will slow the rally but not derail it. Gold ticked above $4,355 on Friday on a softer dollar and lower oil prices. Goldman Sachs holding its end-2027 gold forecast at $5,400 an ounce despite this week's rate hike is the more notable signal here, since it suggests the bank sees the Fed's tightening path as a headwind that slows gold's rally rather than one that reverses it. That view sits against a backdrop where higher rates would typically curb demand for a non-yielding asset by increasing the appeal of yield-bearing alternatives, yet gold has still edged higher on Friday, helped by a softer dollar and a 1% pullback in oil prices. With 16 of 18 Fed policymakers now pointing to at least one more hike this year, the near-term path for real yields remains a genuine headwind, but Goldman's unchanged long-term call implies the bank sees that pressure as manageable within its broader bullish thesis, likely underpinned by continued central bank buying and ongoing Middle East risk. --- Goldman says the Fed's hike slows gold's rally, but the bank isn't backing off its $5,400 call. Summary: Goldman Sachs kept its end-2027 gold price forecast unchanged at $5,400 per troy ounce despite this week's Federal Reserve rate hike, saying tighter policy ( Goldman ditches one and done call, now sees a second Fed hike in October ) is likely to slow bullion's rally but not derail it Gold rose slightly on Friday to trade above $4,355 an ounce, supported by a 1% fall in oil prices and a subdued US dollar The Fed raised interest rates on Wednesday and signalled further hikes ahead, with updated projections showing 16 of 18 policymakers expecting at least one more quarter-point increase by year end A weaker dollar makes dollar-priced commodities cheaper for holders of other currencies, while higher rates typically curb gold demand by boosting the appeal of yield-bearing assets Market participants remain focused on developments in the Middle East and the broader path for global monetary policy Goldman Sachs kept its end-2027 gold price forecast unchanged at $5,400 per troy ounce on Friday, even after this week's Federal Reserve rate hike, saying tighter monetary policy is likely to slow bullion's rally rather than derail it. The bank's unchanged call comes despite a backdrop that would typically weigh on gold, since higher interest rates increase the appeal of yield-bearing assets and can curb demand for a non-yielding metal, even one traditionally viewed as an inflation hedge. Gold itself ticked higher on Friday, trading above $4,355 an ounce, as lower oil prices and a subdued US dollar offered support. Oil fell around 1% on the day, while the dollar remained soft after retreating from recent highs, a combination that makes dollar-priced commodities less expensive for holders of other currencies and has provided a modest tailwind for bullion. The move comes just two days after the Fed raised interest rates on Wednesday and flagged further hikes in the months ahead. Updated quarterly economic projections showed 16 of the Fed's 18 policymakers now anticipate at least one more quarter-percentage-point increase by the end of this year, a hawkish signal that has kept real yields and the dollar in focus for gold traders. Despite that backdrop, market participants have kept a close eye on developments in the Middle East alongside the broader path for global monetary policy, with geopolitical risk continuing to provide an offsetting source of support for the metal even as the rate outlook turns less accommodative. Source: https://investinglive.com/commodities/goldman-keeps-5-400-gold-forecast-intact-despite-fed-hike/
Sep 18, 2026 15:37
[SMM Analysis] Sustained Zinc Inventory Drawdown in China: Key Drivers & Outlook
[Zinc inventory falls from 270,000 mt to 213,500 mt: Who is driving this round of destocking?] Since late August, China's visible social inventory of refined zinc has dropped from 270,000 mt all the way to 213,500 mt, showing a sustained pullback overall. Entering September, social inventory declined at an accelerated pace. By region, Shanghai and Tianjin saw the most pronounced inventory pullbacks......
Sep 17, 2026 16:20

Latest News

[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
15 hours ago
US Makes Preliminary Anti-dumping Determination on Tinplate
Sep 18, 2026 19:03
[Indonesia's ICOMEX opens on January 4, 2027, with tin included in the first batch of traded commodities]
Indonesia Commodity Exchange chief regulator Sardjito said at a parliamentary hearing on Tuesday that the country's newly established ICOMEX commodity exchange plans to begin trading on January 4, 2027, with tin to be included among the first traded commodities. Slides he presented showed that Indonesian state-owned mining companies are expected to be among the first participants. The commodity exchange, ICOMEX, is one of President Prabowo's initiatives to strengthen state control over natural resources and their revenues. Prabowo has previously stressed that Indonesia should not sell its resources at low prices. OJK Chairman Friderica said the exchange will help combat underreporting of prices and transfer pricing in exports. OJK expects to issue regulations for the exchange on September 17, with the exchange to be established on the same day and its license to be issued on January 1. Sardjito said trading in mineral and strategic commodities is expected to officially commence through the ICOMEX entity on January 4, 2027.
Sep 18, 2026 17:29
Data: SHFE, DCE market movement (Sep 18)
The following table shows the ferrous and nonferrous metals movement on the SHFE and DCE on 18 Sep , 2026
Sep 18, 2026 16:11
Tightening pressure peaks in stages, the most-traded SHFE tin contract continues to rebound [SMM Tin Midday Review]
[SMM Tin Midday Review: Tightening Pressure Peaks in Stages, the Most-Traded SHFE Tin Contract Continues to Rebound]
Sep 18, 2026 11:56
The most-traded SHFE tin contract closed overnight at 405,050 yuan, up 1.36%, with the 405,000 yuan/mt level yet to be tested [SMM Tin Morning News]
[SMM tin morning briefing: The most-traded SHFE tin contract closed overnight at 405,050, up 1.36%, with the 405,000 yuan/mt level yet to be tested]
Sep 18, 2026 09:00
SHFE tin rose 1.61% in the daytime session, returning to 400,000. After the rate hike materialized, it consolidated in the 400,000-405,000 range. [SMM Tin Morning Meeting Summary]
[SMM Tin Morning Meeting Summary: SHFE tin rose 1.61% in daytime session, back to 400,000, consolidating in the 400,000-405,000 range after the rate hike was delivered]
Sep 18, 2026 08:58
SHFE tin closed at 398,430 on September 16, up 0.99%, stopping its decline and rebounding. Bulls reduced positions, with the 410,000 level yet to be confirmed [SMM Tin Morning News]
[SMM Tin Morning Update: LME tin inventory at 4,890 mt, down 230 mt; September FOMC rate hike almost certain, watch for decision]
Sep 17, 2026 08:57
SHFE tin rose 1.24% overnight to close at 400,240, with the 400,000 level becoming new support [SMM Tin Morning Meeting Summary]
[SMM Tin Morning Meeting Summary: SHFE tin rose 1.24% overnight to close at 400,240, with the 400,000 level becoming new support]
Sep 17, 2026 08:54
Data: SHFE, DCE market movement (Sep 16)
The following table shows the ferrous and nonferrous metals movement on the SHFE and DCE on 16 Sep , 2026
Sep 16, 2026 16:28
Macro headwinds marginally blunt, coupled with active market trading, the most-traded SHFE tin contract rebounds after dipping [SMM Tin Midday Review]
[SMM Tin Midday Review: Macro Headwinds Marginally Diminish and Active Market Trading Drive the Most-Traded SHFE Tin Contract to Rebound from Lows]
Sep 16, 2026 11:54
LME tin inventory 4,890 mt, down 230 mt; September FOMC rate hike almost certain, watch for decision [SMM Tin Morning News]
[SMM Tin Morning Update: LME tin inventory at 4,890 mt, down 230 mt; September FOMC rate hike almost certain, watch for decision]
Sep 16, 2026 09:02
SHFE tin stabilized at 394,010, down slightly by 0.13%, LME tin inventory decreased by 230 mt to 4,890 [SMM Tin Morning Meeting Summary]
[SMM Tin Morning Meeting Summary: SHFE tin stabilized at 394,010, down slightly by 0.13%, LME tin inventory decreased by 230 mt to 4,890]
Sep 16, 2026 08:58
Central China Lead Smelter's Upgrade Delayed, Production to Resume in October
【Lead Smelter Dynamics】 It is understood that a mid-sized primary lead smelter in Central China has indicated that the actual progress of its electrolytic lead equipment technological renovation and upgrade is slower than expected. The equipment upgrade was originally planned to be completed in about one month, but in reality, it will be difficult to complete before the end of September. The lead smelting system is expected to resume production at the earliest in October.
Sep 15, 2026 18:08
[SMM Analysis] Indonesia Revises Nickel Ore HPM Once Again, Pulling Limonite Prices Toward Market Levels
[SMM Analysis] Indonesia Revises Nickel Ore HPM Once Again, Pulling Limonite Prices Toward Market Levels
Indonesia’s Ministry of Energy and Mineral Resources (ESDM) recently further revised the benchmark price (HPM) formula for nickel ore, under Kepmen ESDM No.363.K/MB.01/MEM.B/2026 which took effect on September 15, 2026. This revision specifically targets the two parameters that have had the greatest impact on the pricing of low-grade limonite used as feedstock for HPAL — the nickel correction factor (CF) for the 1.2% nickel grade range and the cobalt coefficient
Sep 16, 2026 12:16
SMM to Host  SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event , Shanghai, Nov. 12–13
SMM to Host SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event , Shanghai, Nov. 12–13
15 hours ago
Copper Prices Rebound Sharply: Bad News Fully Priced In, or Fundamentals Reasserting Themselves?
Sep 18, 2026 17:56
[SMM Analysis] Chinese tungsten market sees broad-based decline amid weak supply and demand, with no upside in sight
[SMM Analysis] Chinese tungsten market sees broad-based decline amid weak supply and demand, with no upside in sight
Sep 18, 2026 17:13
[SMM Analysis] Lithium Battery Copper Foil: No Near-Term Supply Constraint, Structural Shortage Risks to Surface in 2027
[SMM Analysis] Lithium Battery Copper Foil: No Near-Term Supply Constraint, Structural Shortage Risks to Surface in 2027
Sep 16, 2026 15:18
Goldman keeps $5,400 gold forecast intact despite Fed hike
Sep 18, 2026 15:37
[SMM Analysis] Sustained Zinc Inventory Drawdown in China: Key Drivers & Outlook
[SMM Analysis] Sustained Zinc Inventory Drawdown in China: Key Drivers & Outlook
Sep 17, 2026 16:20
Latest News
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
9 hours ago

[SMM Flash] China's Sulphuric Acid Production Data for August
15 hours ago

[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
15 hours ago
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
15 hours ago
US Makes Preliminary Anti-dumping Determination on Tinplate
Sep 18, 2026 19:03
[Indonesia's ICOMEX opens on January 4, 2027, with tin included in the first batch of traded commodities]
Sep 18, 2026 17:29
Data: SHFE, DCE market movement (Sep 18)
Sep 18, 2026 16:11
Tightening pressure peaks in stages, the most-traded SHFE tin contract continues to rebound [SMM Tin Midday Review]
Sep 18, 2026 11:56
The most-traded SHFE tin contract closed overnight at 405,050 yuan, up 1.36%, with the 405,000 yuan/mt level yet to be tested [SMM Tin Morning News]
Sep 18, 2026 09:00
SHFE tin rose 1.61% in the daytime session, returning to 400,000. After the rate hike materialized, it consolidated in the 400,000-405,000 range. [SMM Tin Morning Meeting Summary]
Sep 18, 2026 08:58
Data: SHFE, DCE market movement (Sep 17)
Sep 17, 2026 16:27
Rate Hike Lands as Expected; SHFE Tin Returns to 400,000 Yuan Mark [SMM Tin Midday Review]
Sep 17, 2026 11:49
Jintian Titanium: Plans to Raise No More Than 300 Million Yuan Through a Private Placement
Sep 17, 2026 09:52
SHFE tin closed at 398,430 on September 16, up 0.99%, stopping its decline and rebounding. Bulls reduced positions, with the 410,000 level yet to be confirmed [SMM Tin Morning News]
Sep 17, 2026 08:57
SHFE tin rose 1.24% overnight to close at 400,240, with the 400,000 level becoming new support [SMM Tin Morning Meeting Summary]
Sep 17, 2026 08:54
Data: SHFE, DCE market movement (Sep 16)
Sep 16, 2026 16:28
Macro headwinds marginally blunt, coupled with active market trading, the most-traded SHFE tin contract rebounds after dipping [SMM Tin Midday Review]
Sep 16, 2026 11:54
LME tin inventory 4,890 mt, down 230 mt; September FOMC rate hike almost certain, watch for decision [SMM Tin Morning News]
Sep 16, 2026 09:02
SHFE tin stabilized at 394,010, down slightly by 0.13%, LME tin inventory decreased by 230 mt to 4,890 [SMM Tin Morning Meeting Summary]
Sep 16, 2026 08:58
Central China Lead Smelter's Upgrade Delayed, Production to Resume in October
Sep 15, 2026 18:08