

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
[SMM Analysis] India’s BESS Manufacturing Push Accelerates, but Cell Dependence Remains a Key Bottleneck
In the first quarter of 2026, global energy storage system shipments reached 100.0 GWh, a 96.5% increase from 50.9 GWh in the same period of 2025, bringing quarterly shipments to an entirely new scale.
Sep 30, 2026 08:50 (GMT+8)
SMM Launches Aluminium CBAM Calculator: What Cost Estimates Mean for EU-Bound Offers【SMM Analysis】
As the EU Carbon Border Adjustment Mechanism (CBAM) enters its definitive phase, aluminium trade with Europe requires carbon costs to be assessed alongside metal prices, processing charges and logistics. SMM has launched its Aluminium CBAM Calculator , bringing together product codes, origin, emissions data and certificate prices to support export quotations, European procurement and internal budgeting. The aluminium module offers 58 CN codes and 68 origin/default-value categories, covering unwrought aluminium, profiles, sheet, strip, foil and other products. Annual parameters are available for 2026–2030. Users enter a tonnage and select default emissions or enter verified actual emissions. The page then displays estimated certificates per tonne, total certificates, cost per tonne and total budget, with primary and secondary aluminium routes matched to the applicable data basis. The practical benefit is that assumptions and results appear together. Exporters can specify the product, origin, import period and emissions basis behind a quotation, while buyers can compare sources under consistent conditions. The page includes Chinese and English interfaces, parameter tables and a printable cost-sheet option. How the associated costs are shared between buyers and sellers remains a contractual matter. Certificate exposure should be distinguished from its monetary value. As of 29 September 2026, the calculator incorporates official prices of €75.36 per certificate for Q1 2026 and €75.28 for Q2. The Q3 price has not yet been published. Where a price is unavailable, the page retains certificate-volume estimates and leaves costs blank, rather than substituting an assumed price. The current version excludes deductions for carbon prices paid abroad and assessment of the annual import threshold. Its actual-emissions calculation for complex aluminium goods also lacks the free-allocation adjustment attributable to precursors. The analysis below therefore uses the checked default-value calculation. Results are commercial estimates, not final statutory surrender obligations. For market comparisons, the same aluminium product can carry materially different estimated costs depending on its origin-specific default value. Consider CN 76012040—unwrought aluminium alloys in billet form—with primary route K, the Q2 2026 certificate price and a quantity of 1,000 tonnes. Estimated costs under the Chinese, Indian and Canadian default-value cases are €143.98, €50.41 and €57.86 per tonne, respectively. These figures include the annual default-value mark-up and the benchmark-based free-allocation adjustment. The Chinese and Indian default-value cases differ by approximately €93.57 per tonne. Comparing only the metal price or processing charge may therefore miss a meaningful difference in the buyer's budget. Where other commercial terms are similar, estimated CBAM costs could affect an offer's attractiveness. However, this is not a ranking of producers' actual carbon intensity. Freight, customs duties, quality and delivery terms are also outside this comparison, so the figures alone cannot determine the preferred supplier. This highlights the commercial value of supplier emissions documentation. For producers whose actual emissions are below the applicable default value, supported by compliant verification, actual data may change a buyer's cost assessment. Buyers can use defaults for an initial budget when documentation is unavailable, then reassess using supplier evidence. Exporters consequently have a reason to prepare emissions information alongside their product offers, rather than negotiate solely around country-default differences. Annual parameter changes also warrant attention. Holding the Chinese product's base default value, route and benchmark constant, and assuming that the import year and applicable reporting year coincide, estimated certificate exposure rises from 1.912575 per tonne in 2026 to 2.248150 in 2027—an increase of approximately 17.5%. This reflects a higher default-value mark-up and a smaller free-allocation deduction; it does not imply a rise in future certificate prices. For supply arrangements spanning different years, companies can first compare certificate exposure, then discuss price-update mechanisms and cost sharing. Even while future certificate prices remain unknown, identifying that exposure and obtaining supplier documentation can improve the comparability of offers and procurement budgets.
Sep 29, 2026 17:32 (GMT+8)
[SMM Analysis] Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?
[SMM Analysis: Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?] BHP and Amazon’s EAC pilot separates verified emissions reductions from physical copper trade, giving low-emissions primary copper a new source of environmental value. Recycled copper retains a major energy advantage, but future competitiveness may depend more on traceability, recycled content and verified carbon data, potentially adding an environmental dimension to pricing.
Sep 29, 2026 16:03 (GMT+8)
Latest News

[South Africa Moves to Ban Cash Scrap Metal Sales to Curb Infrastructure Theft]
3 mins ago

[India's Steel Exchange India hits record monthly rebar output; September at 25,095 tonnes]
3 mins ago
[Nigeria scrap dealers' 15-day strike threatens steel output and construction costs]
3 mins ago
[India's SAIL posts record 8.39 million tonnes H1 steel output, September sales up 4%]
Steel Authority of India Limited (SAIL) posted record first-half steel output of 8.39 million tonnes for April-September of the current fiscal year, with September sales up 4% year on year, underscoring resilient demand from construction and infrastructure. As India's largest state-owned steelmaker, operating integrated plants at Bhilai, Bokaro, Rourkela, Durgapur and Burnpur, SAIL's volumes are a key gauge of domestic consumption and public capital spending. The record H1 output and September sales growth point to steadier blast furnace operations and firmer order books, supporting India's full-year crude steel growth. Attention now turns to post-monsoon construction, rail and port demand for longs, and pressure from cheaper imports. Source: SAIL.
3 mins ago
[India's Steel Ministry directs SAIL, NMDC to scout overseas iron ore and coking coal assets]
The Steel Ministry has directed SAIL and NMDC to scout and acquire overseas iron ore and coking coal assets, to secure long-term raw material supply, cut reliance on imported metallurgical coal (about 90% of India's needs) and stabilise steelmaking costs, supporting India's 300 MTPA capacity goal by 2030 against roughly 221.9 MTPA now. After a May 2026 delegation to Russia, SAIL set up an internal committee to assess coking coal and nickel deals, possibly via the ICV consortium. SAIL's August 2026 sales rose 13% y-o-y to 1.87 million tonnes and crude steel output 8% to 1.68 million tonnes; Q1 FY27 net profit jumped 138% to 186 million USD, with EBITDA up 49% to 496 million USD. NMDC produced 4.07 million tonnes of iron ore, up 20.8%, and sold 3.58 million tonnes. Geopolitical, funding and execution risks persist.
3 mins ago
[Tata Steel CEO: India's steel consumption to grow 7-8% in coming years]
Tata Steel CEO and MD T.V. Narendran expects India's steel consumption to grow 7-8% or more in coming years on strong domestic demand. Speaking at the IFQM Symposium 2026, he said GST changes have boosted the automobile sector, while construction demand, especially industrial projects and infrastructure, stays firm, with more balanced urban and rural growth. He is positive on the industry for the next 3-4 years. On rising global tariffs and trade barriers, he called supply-chain localisation inevitable, as countries and companies prioritise resilience over cost optimisation, urging firms seeking India's market to invest, create local jobs and serve consumers locally. On green steel, India remains at an early stage and needs policy support, customers willing to pay more and industry investment.
3 mins ago
Vedanta Faces $582M Demand from OMC After Court Rejects Bauxite Pricing Plea
Odisha Mining Corp has raised a Rs 56 billion ($582 million) payment demand on Vedanta Aluminium following an Orissa High Court ruling; Vedanta has approached the Supreme Court for relief, media organisation reported.
17 mins ago
[SMM Steel] Indian HRC Holds Steady as EU Quota Queue Builds
[India Export] India’s HRC export prices for Europe remained at 660USD/tonne FOB India on October 5, with the Northern European reference unchanged at 730USD/tonne CFR, retaining previous week’s levels. European buying remained selective amid moderate-to-high inventories and uncertainty over quota access and CBAM costs. According to the European Commission’s October 2 update, India officially had 149,318.61tonnes of EU HRC quota available for October–December under Category 1A, order 09.9803. Requests to use 102,977.12tonnes were already waiting for approval. If all those requests are approved, only 46,341.49tonnes would remain for additional imports. Out-of-quota imports face a 50% duty, while melt-and-pour documentation requirements have applied since October 1. The Commission’s consultation on the functioning of the new steel quota regime, opened on September 28, runs until October 11 at 23:59 CEST and seeks feedback from steel producers, users and third-country exporters on its first-quarter impact. Domestically, Mumbai HRC remained at approximately 656USD/tonne (63,000INR/tonne) EXW.
35 mins ago
India’s Steel, Ferro-Chromium and Electrical Equipment Exports to South Korea Rise in Q1 FY2026-27
India’s exports of steel, ferro-chromium and electrical equipment to South Korea rose strongly in Apr–Jun FY2026-27, reflecting robust demand for Indian industrial and engineering products.
47 mins ago
[SMM Steel] India domestic steel and scrap prices continues to rise
[SMM Steel] India domestic steel and scrap prices continues to rise
[India Domestic] Domestic steel and scrap market trended up from Oct 1 with prices rising across key markets while some remained flat. Unscheduled power cuts in Chhattisgarh have affected industrial operations, with production at several factories down by up to 35%. Power demand reached around 6,000 MW in September, while supply was reportedly short by 500–600 MW. Industry operators said 7–8 hours of night-time power cuts are affecting production, with the Mini Steel Plant Association also reporting lower output and losses. Mandi HMS 1&2 (80:20) up 3 USD/tonne (300 INR/tonne) to 412 USD/tonne (39,700 INR/tonne) delivered Mandi. Alang Melting flat at 395 USD/tonne (38,000 INR/tonne) ex-yard Alang. Mandi ingot up 1 USD/tonne (100 INR/tonne) to 506 USD/tonne (48,700 INR/tonne) EXW Mandi. Mumbai Rebar rose 6 USD/tonne (600 INR/tonne) to 557 USD/tonne (53,700 INR/tonne) EXW Mumbai. While, rebar unchanged 542 USD/tonne (52,200 INR/tonne) EXW Raipur. Raipur Billet up 2 USD/tonne (200 INR/tonne) to 474 USD/tonne (45,700 INR/tonne) EXW Raipur. Sponge iron PDRI unchanged at 309 USD/tonne (29,800 INR/tonne) EXW Raipur.
1 hour ago

[SMM Chromium Flash] China's High-Carbon Ferrochrome Output Drops 3.17% MoM in September as Cost Inversion Bites
1 hour ago

London BTC flags copper and antimony at Nevada Black Star
1 hour ago
[SMM Steel] Indonesian HRC Prices Steady at $520/mt FOB as Mills See No Need to Adjust
1 hour ago
Kantra extends Nugent copper-gold lode 70m below resource
Kantra Copper Limited (ASX:KAN) reported underground diamond drilling at its Kanmantoo copper mine in South Australia that extends the Nugent lode 70m below the 2025 Mineral Resource Estimate and 370m beneath the current 950 Level stopping horizon. Hole 26KVUG0949 returned 70m at 1.18% copper and 0.24g/t gold from 507m, including 38m at 1.46% copper and 0.18g/t gold. Nugent, on the deposit's south-western edge, carries generally higher gold grades. By end-August 2026 the company had completed 38,535m of underground diamond drilling, including 12,024m at Nugent, and expects a resource update incorporating about 80,000m of drilling in late October. Kanmantoo is an operating mine that produced 3,170t of copper in the June 2026 quarter; 2026 guidance is 12,750-14,000t of copper, and the deep extension offers low-capital growth from existing infrastructure.
1 hour ago
Liberia survey flags early-stage anomalies across Zodiac licences
[SMM Tantalum & Niobium Flash] Zodiac Gold has completed 10,661 soil samples across 530 km² of its Bomi South and Bong West licences in Liberia. National stream-sediment maps place parts of the licence package within the top 0.5% of Liberia’s dataset for 16 elements, including tantalum and niobium. Zodiac’s portable-XRF screening of 2,270 soil samples returned niobium values up to 61 ppm; the release provided no corresponding quantified tantalum soil result.
The findings broaden the licences beyond their primary gold focus and identify areas for follow-up mapping and infill sampling. They remain reconnaissance evidence, not a tantalum or niobium discovery: portable-XRF readings are preliminary, most samples have not yet been screened for multiple elements, and no drilling, mineral resource, metallurgy or economic study has established recoverable mineralisation.
1 hour ago
Indonesia and Chile Propose Green Minerals Partnership to Boost Critical Minerals and Battery Cooperation
Indonesia and Chile proposed a Green Minerals Partnership to deepen cooperation in copper, aluminium, battery materials, green mining technology and downstream processing, supported by the IC-CEPA.
1 hour ago
SAGA begins further processing tests on Labrador ore
[SMM Titaniumm Flash] SAGA Metals and Temas Resources have begun an approximately eight-week bench-scale optimisation programme using material from SAGA’s Radar titanium–vanadium–iron project in Labrador, Canada. The programme follows earlier laboratory tests that recovered up to 90.8% of titanium from an ilmenite concentrate under the conditions tested. The new work will compare feed samples and refine leaching and solvent-extraction conditions.
The companies aim to produce initial high-purity titanium dioxide, vanadium and iron samples and gather data for a possible mini-pilot decision. Those products have not yet been reported, and the earlier laboratory recovery does not establish commercial yields or costs. Processing results will help determine whether Radar has a viable route to downstream titanium products.
1 hour ago
Freeport Reports Q3 Copper Production of 830 Million lb as Grasberg Recovery Advances
Freeport-McMoRan reported third-quarter 2026 consolidated copper production of approximately 830 million lb, equivalent to about 376,500 mt, broadly in line with expectations as the company continued the phased recovery of operations at the Grasberg minerals district in Indonesia.
Freeport said slightly stronger results from its international operations offset somewhat lower production from its U.S. mines. Third-quarter copper sales are expected to approximate the company’s July estimate of 750 million lb.
At Grasberg, mill throughput averaged approximately 140,000 mt of ore per day during the quarter, equivalent to around 67% of normalized operating rates before the September 2025 incident. About 70,000 mt/day of the total throughput came from the Grasberg Block Cave underground mine.
Upgrades to the Block Cave material-handling system remain on track for completion in early 2027, while preparations continue for the targeted restart of Production Block 1S by mid-2027. Freeport continues to expect Grasberg to reach approximately 80% of capacity by mid-2027 and approach full capacity by the end of 2027.
PT Freeport Indonesia’s Eastern Java smelter, which had been temporarily suspended following the September 2025 Grasberg incident, restarted operations in late August 2026. Freeport said the smelter ramp-up is progressing in line with expectations. PTFI’s combined smelting capacity, including PT Smelting, is capable of producing up to approximately 800,000 mt/year of copper cathode.
Freeport also said its U.S. operations experienced lower-than-planned operating rates during the third quarter due to localized flooding, power outages and strong winds, while unusually dry conditions in Indonesia created some milling challenges with limited impact to date.
Freeport’s third-quarter production performance indicates that the Grasberg recovery is progressing broadly in line with the company’s expectations, although the operation remains below pre-incident throughput levels. The gradual ramp-up at both the Grasberg Block Cave and the Eastern Java smelter should support improving copper output and downstream processing capacity over the coming quarters. Attention will remain on completion of the material-handling upgrades, the planned restart of Production Block 1S and Freeport’s ability to reach 80% of Grasberg capacity by mid-2027.
1 hour ago
China Seeks Copper Concentrate Supply Commitments for Anglo–Teck Merger Approval
China’s antitrust regulator has asked Anglo American to provide assurances that the combined company resulting from its proposed merger with Teck Resources would maintain a steady supply of copper concentrate to China, according to Reuters, citing three people familiar with the matter.
The request forms part of China’s regulatory review of the proposed US$54 billion Anglo–Teck merger. Reuters reported that the supply assurances are being sought as a condition for Chinese approval of the transaction, although the precise terms of any undertaking have not been publicly disclosed.
The discussions come as Chinese copper smelters face severe constraints in concentrate availability. China accounts for around 60% of global refined copper cathode production, making its smelting industry heavily dependent on reliable supplies of copper concentrate.
Rapid growth in global smelting capacity has outpaced growth in mined copper supply, contributing to a prolonged tightening in the concentrate market. Reuters reported that China’s current feedstock shortage is among the most severe experienced by its copper smelting sector in decades.
Anglo American said it is working constructively with China’s State Administration for Market Regulation as the review progresses. No fixed concentrate volumes or binding supply arrangement have been publicly confirmed.
The proposed merger would combine significant copper assets held by Anglo American and Teck, increasing the enlarged group’s importance in global mined copper supply. Reuters estimates that the combined company would account for approximately 5% of global copper supply.
China’s reported request for copper concentrate supply assurances highlights the importance of feedstock availability to the country’s smelting industry amid a prolonged concentrate shortage. The request indicates that copper concentrate supply security has become an important consideration in China’s review of the Anglo–Teck merger. Attention will now turn to whether the parties agree to any formal supply commitments and whether those conditions affect the timing or structure of the merger approval process.
1 hour ago
Asante gains more time to arrange US$100 million for Ghana mines
[SMM Gold Flash] On 30th September 2026, Asante Gold announced that its senior lenders, stream purchaser and hedge counterparty had agreed to extend its deadline for securing at least US$100 million in new funding to 31 October. The deadline for a cost-to-complete certificate moved to 31 March 2027. Asante said it had agreed funding terms with Fujairah Holding, which requested more time for internal approvals. Final approval and signed funding agreements remain outstanding.
The extensions give Asante more time to address financing requirements affecting its operating Bibiani and Chirano gold mines in Ghana. They do not resolve the funding requirement: completion of the proposed package is the next material milestone.
2 hours ago
[SMM Announcement] Chinese Market Metal Prices and News Updates Suspended during National Day Holiday (Oct 1-7)
Dear Valued SMM Users, The National Day holiday is approaching. Please note that SMM Chinese market metal price assessments and news updates will be temporarily suspended during the holiday (October 1-7) and resume normal release after the break. However, SMM overseas price assessment will continue to be updated as usual throughout the holiday. We apologise for any inconvenience caused and wish you a pleasant holiday. Shanghai Metals Market (SMM)
Sep 28, 2026 17:06 (GMT+8)
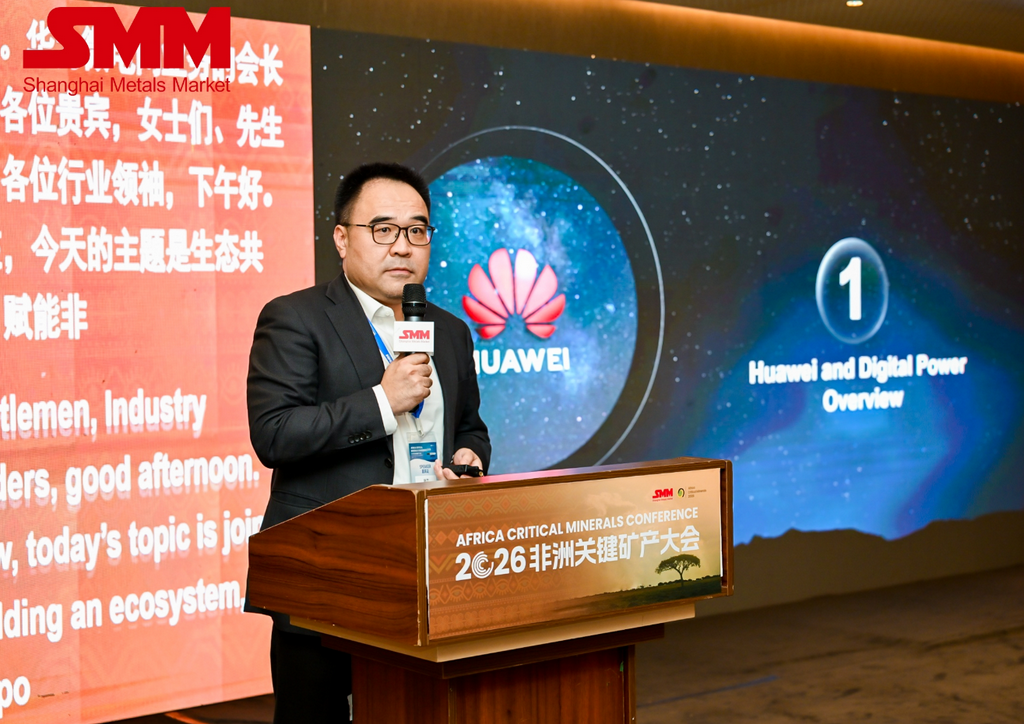
Huawei Pursues Africa Green‑Mining Partnerships and Holds Business Talks with ZESCO at SMM ACM 2026
Sep 23, 2026 16:41 (GMT+8)
[SMM Analysis] The U.S. Copper Tariff Trade Is Fading — but It Isn’t Over Yet
Sep 29, 2026 14:37 (GMT+8)
South Africa Poised to Become Key Player in Global Rare Earth Supply Chain by 2034【SMM Analysis】
Sep 29, 2026 18:54 (GMT+8)
[SMM Analysis] India’s BESS Manufacturing Push Accelerates, but Cell Dependence Remains a Key Bottleneck
Sep 30, 2026 08:50 (GMT+8)
SMM Launches Aluminium CBAM Calculator: What Cost Estimates Mean for EU-Bound Offers【SMM Analysis】
Sep 29, 2026 17:32 (GMT+8)
[SMM Analysis] Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?
Sep 29, 2026 16:03 (GMT+8)
Latest News
[South Africa Moves to Ban Cash Scrap Metal Sales to Curb Infrastructure Theft]
3 mins ago
[India's Steel Exchange India hits record monthly rebar output; September at 25,095 tonnes]
3 mins ago
[Nigeria scrap dealers' 15-day strike threatens steel output and construction costs]
3 mins ago
[India's SAIL posts record 8.39 million tonnes H1 steel output, September sales up 4%]
3 mins ago
[India's Steel Ministry directs SAIL, NMDC to scout overseas iron ore and coking coal assets]
3 mins ago
[Tata Steel CEO: India's steel consumption to grow 7-8% in coming years]
3 mins ago
Vedanta Faces $582M Demand from OMC After Court Rejects Bauxite Pricing Plea
17 mins ago
[SMM Steel] Indian HRC Holds Steady as EU Quota Queue Builds
35 mins ago
India’s Steel, Ferro-Chromium and Electrical Equipment Exports to South Korea Rise in Q1 FY2026-27
47 mins ago
[SMM Steel] India domestic steel and scrap prices continues to rise
1 hour ago
[SMM Chromium Flash] China's High-Carbon Ferrochrome Output Drops 3.17% MoM in September as Cost Inversion Bites
1 hour ago
London BTC flags copper and antimony at Nevada Black Star
1 hour ago
[SMM Steel] Indonesian HRC Prices Steady at $520/mt FOB as Mills See No Need to Adjust
1 hour ago
Kantra extends Nugent copper-gold lode 70m below resource
1 hour ago
Liberia survey flags early-stage anomalies across Zodiac licences
1 hour ago
Indonesia and Chile Propose Green Minerals Partnership to Boost Critical Minerals and Battery Cooperation
1 hour ago
SAGA begins further processing tests on Labrador ore
1 hour ago
Freeport Reports Q3 Copper Production of 830 Million lb as Grasberg Recovery Advances
1 hour ago
China Seeks Copper Concentrate Supply Commitments for Anglo–Teck Merger Approval
1 hour ago
Asante gains more time to arrange US$100 million for Ghana mines
2 hours ago