

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
China’s Spodumene Imports Rise 7% MoM in September, with Australia, Nigeria and Zimbabwe the Top Three Sources
According to compiled Chinese customs data, China imported 970,100 physical tonnes of spodumene in September 2026, up approximately 7.0% from 906,600 tonnes in August. Based on the classification and assumed grades, moisture content and conversion factors used in this analysis, September imports represented approximately 81,300 tonnes of lithium carbonate equivalent (LCE). By origin, imports from Australia, Nigeria and Zimbabwe increased significantly. Australia remained the largest supplier, with shipments to China reaching 446,200 tonnes, up approximately 36.7% month on month and accounting for around 46.0% of total imports. Nigeria became the second-largest supplier at 189,800 tonnes, up approximately 40.1%, while imports from Zimbabwe rose approximately 83.0% to 136,500 tonnes. Imports from South Africa fell approximately 49.6% to 112,400 tonnes, whereas imports from Brazil increased approximately 30.9% to 81,200 tonnes. Smaller volumes came from Burundi, Rwanda and Mozambique, at approximately 1,800 tonnes, 1,300 tonnes and 1,000 tonnes, respectively, with limited shipments from Zambia and Somalia. No imports from Mali or Canada appeared in the September dataset. Overall, China’s spodumene imports continued to grow in September, with the composition shifting toward concentrate. Under the classification used in this analysis, concentrate imports reached approximately 688,800 tonnes, accounting for 71.0% of total physical imports, compared with 60.7% in August. Raw ore imports stood at approximately 281,300 tonnes. Increased concentrate imports from Australia, Zimbabwe and Nigeria offset lower imports from Mali and Canada, providing the main support for growth in China’s imported lithium resource supply during the month.
Oct 20, 2026 19:03 (GMT+8)
[SMM Analysis] Hoa Phat’s record HRC sales reshape Vietnam’s self-sufficiency and China’s export flows
Hoa Phat sold 5.47 Mt of hot-rolled coil in January to September, up 59% and about a third of Vietnam’s consumption, with 24.6% of third-quarter sales exported. Vietnam’s HRC demand of about 17.3 Mt this year still exceeds local output of about 10.8 Mt by 6.5 Mt, and new capacity arrives mainly after 2027. Anti-dumping duties have pushed mainstream Chinese coil out of Vietnam; Chinese mills now face Vietnamese coil in ASEAN and other third markets.
Oct 20, 2026 14:36 (GMT+8)
China's Rare Earth Magnet Exports Hit Record in September, Driven by Backlog Release and Regulatory Easing【SMM Analysis】
China’s September rare earth magnet exports hit a record 6,165 tonnes (+23% MoM), driven by clearance of July–August port backlogs, not new demand. US-China talks unblocked shipments, while EU “green channel” talks lifted Q4 forecast to ~5,700 tonnes/month. Large producers recovered fastest; small mills remain constrained.
Oct 20, 2026 16:06 (GMT+8)
Latest News
Liuzhou Iron & Steel, Huawei deploy Xuantie steel AI model targeting 80% coverage
2 hours ago
[SMM Analysis] Indian flat steel demand supports record JSW sales as coal costs squeeze margins
20 hours ago

Magnesium Prices Fall Nearly 14% in Over Half a Year, Hitting Yearly Low; Low-Priced Supply Hard to Find Support for Rebound [SMM Commentary]
23 hours ago
[SMM Steel] Tight Supply Sends Indonesian Wire Rod Buyers to Small Java Mills Despite Modest Demand
[Indonesia] Wire rod prices remain at USD 500/metric ton FOB for January 2027 delivery from the mills. Wire rod is still the most active product in the local market, but its price from the mills is flat, as they cannot supply now. Demand is limited to small restocking, and buyers who cannot wait until January are turning to small mills in Java. Major mills, in turn, are keeping their price at USD 500/mt FOB to stay competitive when their January supply becomes available. With demand still slow and Chinese prices not rising, buyers continue to hold pricing power, and wire rod prices are unlikely to rise in the near term.
Oct 23, 2026 17:38 (GMT+8)
[SMM Sheets & Plates Daily Review] Demand recovery remains weak; HRC prices may consolidate on a subdued note next week
Today, the most-traded HRC contract drifted lower, closing at 3,209, down 0.43% intraday; spot prices mostly fell by 10-20 yuan/mt. This week, HRC prices drifted lower, with a notable decline in the second half of the week. Overall transaction performance deteriorated, and market trading sentiment cooled. In terms of supply, HRC rolling line maintenance decreased this week, and overall HRC production edged up. In terms of demand, apparent demand for HRC recovered MoM this week, with just-in-time procurement dominating. Downstream industries diverged, but destocking remained slow, and the sustainability of demand improvement was insufficient. In terms of inventory, this week SMM's survey of HRC social inventory across 86 warehouses nationwide (large sample) stood at 4.9706 million mt, down 56,500 mt WoW, or -1.12% WoW. By region, all regions across the country were destocking, with larger declines in central China and north-east China. Cost side, coke prices held steady this week, while iron ore prices edged down, slightly weakening cost support for HRC. Looking ahead, coke prices have fully stopped falling, while iron ore prices are expected to continue declining. Cost support for HRC remains insufficient, but the supply-demand imbalance in HRC has eased somewhat, limiting the room for deep declines. In summary, the most-traded HRC contract is expected to trade in the 3,160-3,260 range next week, consolidating on a subdued note. Going forward, focus on raw material price changes and blast furnace maintenance.
Oct 23, 2026 17:14 (GMT+8)
[SMM Steel]
[Sheets & Plates] Today, export prices for some HRC and other sheets & plates fell $1-2/mt WoW, with HRC transaction prices concentrated in the $486-490/mt range. Some steel mills in northeast China are still in maintenance, with quoting progress slowing down and shipment schedules already extended to December; some steel mills in south China continue to maintain relatively high offer levels due to elevated in-plant costs.
Oct 23, 2026 16:49 (GMT+8)
[SMM Steel] India Steel Prices Edge Lower as Buyers Remain Cautious
[India Domestic] India’s domestic steel market showed a weak trend with prices of edging lower to flat. Cautious buying and subdued demand continued to weigh on market sentiment. Raipur billet dropped 3 USD/tonne (300 INR/tonne) to 463 USD/tonne (44,000 INR/tonne) EXW Raipur. Ludhiana ingot down 3 USD/tonne (300 INR/tonne) to 502 USD/tonne (47,700 INR/tonne) EXW Ludhiana. Raipur Rebar declined 4 USD/tonne (400 INR/tonne) to 542 USD/tonne (51,100 INR/tonne) EXW Raipur. HMS 1&2 (80:20) slipped 1 USD/tonne (100 INR/tonne) to 399 USD/tonne (37,900 INR/tonne) delivered Mandi. Bellary PDRI sponge iron unchanged 308 USD/tonne (29,300 INR/tonne) EXW Bellary. Trading activity may improve and prices increase after early November post Diwali as per market participants.
Oct 23, 2026 16:48 (GMT+8)
[Brief Comment on Domestic Iron Ore] Iron ore concentrate prices in west Liaoning may consolidate
Domestic ore transactions in western Liaoning were weak today. Local iron ore concentrates were priced at yuan 640-650/mt on a wet basis, excluding taxes, Ex-works. Traders generally lacked confidence in the market outlook, with most inquiries at lower bids. Some local areas were still affected by earlier environmental protection checks, limiting mining and beneficiation operations. Independent beneficiation plants found it difficult to source ROM ore, and spot supply was tight.
Oct 23, 2026 16:46 (GMT+8)
[SMM Steel] Northwest EU Price Hikes Widen Regional Spread, Elevated Stocks and CBAM Capital Tie-Up Curb Buying
[Europe] Domestic hot-rolled coil (HRC) steel prices in Northwest Europe rebounded sharply, driven by new transactions as buyers showed a willingness to pay a premium to secure first-quarter 2027 production allocations. With December allocations largely sold out, primary mills in Northwest Europe have pivoted toward Q1 production schedules, opening February–March delivery offers at 800–830 EUR/tonne DDP. In benchmark evaluations, the Northwest European HRC ex-works price jumped by 8.00 EUR/tonne to 748.00 EUR/tonne EXW (~838 USD/tonne), whereas the Italian domestic HRC ex-works price slipped by 2.00 EUR/tonne to 741.00 EUR/tonne EXW (~830 USD/tonne), widening the North-South regional price spread. However, price hikes failed to spark a speculative buying wave across the continent. Elevated inventory buffers and heavy port accumulations continue to absorb immediate demand, while trading in Southern Europe (Italy) remains deeply depressed, prompting select cash-strapped service centers to liquidate inventories at cost to generate cash flow. On the foreign trade front, import activity for Q1 arrivals remained severely restricted by tariff-rate quota (TRQ) exhaustion and capital tie-ups under upcoming CBAM rules, with reports of order cancellations for cargoes scheduled to arrive ahead of January 1st. Quotes for Southeast Asian HRC failed to gain traction, as asking prices exceeded local domestic mill levels and attracted virtually no buying interest.
Oct 23, 2026 16:34 (GMT+8)
[SMM Steel] Turkish Rebar: Weak Domestic Intake Drives Prices Down, Export FOB Holds Flat
[Turkey] Domestic rebar prices in Turkey maintained their downward trend this week, overshadowed by expectations that end-use demand will remain stagnant until early 2027, which has kept buyers firmly in a wait-and-see stance to push for further price cuts. In daily evaluations, the Turkish domestic rebar ex-works price held unchanged at 605 USD/tonne EXW (excluding VAT). Regionally, primary steelmakers and traders in Izmir and Iskenderun lowered intraday workable target prices. In Izmir, mill tradable bounds slipped to 600–605 USD/tonne EXW against trader quotes of 598–600 USD/tonne EXW, while buyer counter-bids receded to 590–595 USD/tonne EXW. In Iskenderun, trader quotes held at 600–602 USD/tonne EXW against mill offers of 600–607 USD/tonne EXW. On the export front, Turkish rebar export prices held temporarily flat at 600–605 USD/tonne FOB; however, ongoing softness in the domestic market alongside cautious overseas counter-bids continues to exert downward pressure on export values.
Oct 23, 2026 16:33 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
[SMM Steel] Market feedback indicates that the current FOB quote for 3SP square billet, sized 150×150 mm, stands at USD 461/t, with Jiangyin Port as the port of shipment.
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
[SMM Steel] Market feedback indicates that for Q235B HRC with specifications of 3.5*1500*C, the ex-works price is 3,110 yuan/mt, with the port of shipment being Jingtang Port.
Oct 23, 2026 16:29 (GMT+8)
[SMM India Domestic Market Weekly Review] India Steel Market Remains Subdued Amid Festive Slowdown
India’s domestic steel market remained subdued during October 16–23, as demand and trading activity were affected by the Navratri and Dussehra holidays. Buyers remained cautious and largely focused on immediate requirements, while festive restocking provided limited support. Supply conditions and raw material prices showed mixed movements across the market. Raipur rebar down 6 USD/tonne (600 INR/tonne) WoW to 538 USD/tonne (51,100 INR/tonne) EXW Raipur. Mumbai rebar down 7 USD/tonne (700 INR/tonne) to 558 USD/tonne (53,000 INR/tonne) EXW Mumbai. PDRI sponge iron rose 2 USD/tonne (200 INR/tonne) to 297 USD/tonne (28,200 INR/tonne) EXW Raipur. Mandi ingot up by 3 USD/tonne (300 INR/tonne) to 493 USD/tonne (46,800 INR/tonne) EXW Mandi. Raipur edged down 1 USD/tonne (100 INR/tonne) to 463 USD/tonne (44,000 INR/tonne) EXW Raipur. HMS 1&2 (80:20) up 2 USD/tonne (200 INR/tonne) to 399 USD/tonne (37,900 INR/tonne) delivered Mandi. Melting rose 6 USD/tonne (600 INR/tonne) to 398 USD/tonne (37,800 INR/tonne) ex-yard Alang.
Oct 23, 2026 16:25 (GMT+8)
【SMM Analysis】Silicon Steel Import and Export Performance in September: Imports Surge, Exports Diverge
Oct 23, 2026 16:25 (GMT+8)
[SMM's Weekly Review of the Indonesian Market] Weak Demand Keeps Prices Flat to Soft, Buyers Hold Pricing Power
Week-on-week, wire rod held at USD 500/mt, slab edged down from USD 480 to USD 478/mt, HRC stood at USD 515/mt FOB, and square billet at USD 470/mt (ex-works). Indonesian HRC is priced at around USD 533/mt CFR both in Surabaya and in Vietnam.
Wire rod is still the most active product locally, but its price is flat. Demand is limited to small restocking, and supply is the real issue: mills can only deliver in January 2027, so buyers who cannot wait are turning to small mills in Java, while major mills keep their prices low. In Vietnam, HRC trade is very quiet, with buyers bidding lower and waiting for local mills' monthly prices next month.
Overall, prices are unlikely to rise, since demand is slow and Chinese prices are not increasing. Pricing power stays with buyers, as expected last week, and with no sign of mills raising offers, this is likely to continue next week.
Oct 23, 2026 16:06 (GMT+8)
[Think Tank Warns LNG Power Could Double Electricity Costs for Nippon Steel’s 2 Million mt/yr Yawata EAF]
Nippon Steel’s planned 2 million mt/year electric arc furnace (EAF) at Yawata could face higher production costs and fuel supply risks from its proposed LNG-based power supply, according to an October report by think tank Transition Asia. The report estimates electricity costs could reach about JPY 15,800/mt of steel at the March 2026 spot LNG price peak, compared with around JPY 6,400/mt under normal conditions. Nippon Steel’s share of storage at the shared LNG terminal would cover about 11 days of full power plant operation, and a severe gas-price year could add around JPY 16 billion in costs. Japan’s Ministry of the Environment has also called for the project to avoid fossil fuel lock-in, and urged that all options be considered, including operating restrictions or closure, if no climate-aligned emissions pathway can be set. Transition Asia recommends comparing captive LNG power with grid electricity backed by renewable contracts, noting Kyushu’s grid could become less carbon-intensive than the proposed plant by 2030. Nippon Steel began construction of the Yawata EAF conversion in April 2026.
Oct 23, 2026 16:06 (GMT+8)
[Egypt Sets Up Permanent Billet Supply Committee as Rerollers Push Back on Safeguard Duties]
Egypt’s government will establish a permanent committee to monitor steel billet availability and supply chains, following complaints from rerolling mills over billet costs, import duties and production disruptions. Investment and Foreign Trade Minister Mohamed Farid and Industry Minister Khaled Hashem met integrated and semi-integrated steelmakers and rolling mills to discuss the sector’s challenges and ensure sufficient billet supply at competitive prices. Rerollers have called for a review of safeguard duties on billet imports, saying they have raised costs and forced some mills to suspend production. The definitive duty was introduced at 13% in April 2026 and falls to 12% from September 2026 and 11% the following year. The committee will include the ministries of investment, industry, and supply and internal trade, as well as the Egyptian Competition Authority, and will assess market developments, billet availability and supply chain continuity. Hashem said new billet production licences had been offered under facilitated pricing and payment terms to boost domestic melting capacity and reduce import reliance.
Oct 23, 2026 16:06 (GMT+8)
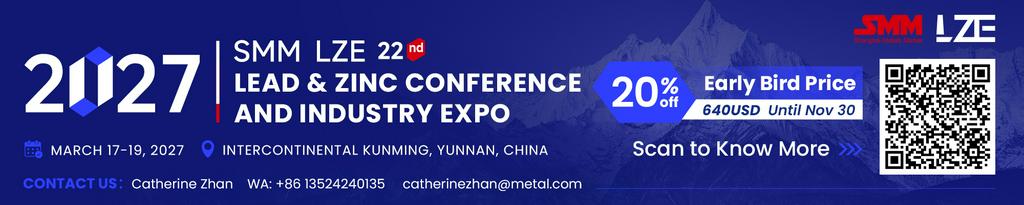
Early Bird Bookings Now Open for 2027 SMM LZE (22nd) Lead & Zinc Conference and Industry Expo in Yunnan next March
——From Conference to Expo · Doubled Scale · Full Upgrade—— [What This Article Brings You] ① Exhibition Introduction ② How to Register ③ First Batch of Exhibitors ④ Conference Agenda I. Doubled Scale, Full Upgrade! In 2026, lead and zinc face sharp volatility—elevated lead prices, scarce high-purity lead, record high LME low-grade lead stocks, lead-acid battery relocation from China to overseas, deeply negative zinc concentrate TCs, tight high-quality imported zinc ore, open export window for zinc ingots, and overseas zinc smelter buildout. The LZE covers market outlook, price forecast, equipment technology, recycling, and downstream applications—driving green transformation and win-win growth. What sets the 2027 (22nd) LZE apart from earlier events is its transformative upgrade: moving from a pure industry conference to a seamlessly combined conference and industry expo — deliver a larger-scale gathering, an expanded industry showcase and far-reaching involvement across the entire lead and zinc value chain. From industry trend analysis to in-depth industry chain exchanges, from upstream and downstream supply-demand matching to concentrated enterprise showcases, from a single industry conference to the further integration of "conference + industry expo"——in 2027, SMM LZE enters the "expo" era! The conference will embrace its 22nd edition with a larger scale, a richer industry lineup, and broader upstream and downstream participation! Scan the QR Code Below to Register as A Visitor for Free 1. Conference Scale Delegation: 6,000+ (up 71.4% from the previous edition) Companies: 2,000+ (up 100% from the previous edition) Exhibitors: 120+ (up 50% from the previous edition) Supply-demand matchmaking: 300+ (up 50% from the previous edition) Dedicated Forums: 7 (1 more than the previous edition) 2. Participant Groups 20% - Miners 23% - Smelters 22% - Processing enterprises 10% - Traders 5% - Lead-zinc end-user procurement 15% - Third-party equipment, technology, auxiliary materials, media, etc. 3% - Government, associations, university research institutions 2% - Financial and futures firms 3. Job Title Breakdown 4. Conference Highlights Price trends, consumption outlook, and policy interpretation Global dialogue on the lead-zinc industry and go-global strategies One-on-One Business Meetings Exploring Breakthrough Paths in Mining & Metallurgy Technology and Resource Recycling Showcase of Cutting-Edge Equipment and Consumables II. Four Identities, One Lead-Zinc Exhibition Whether you are here for market insights, procurement, showcasing or brand exposure, you will find a participation option that suits you. 1. Professional Visitors (Explore the exhibition for business opportunities and connect with the upstream and downstream of the industry) [Visitor Benefits] Exhibition Area Ticket On-site Check-in Gifts SMM Exclusive Lead-Zinc Industry Distribution Map Lead-Zinc Industry Visitor Exchange Group Group Benefits Tickets for Some Forums …… 2. Conference Delegates (Gain insights into new trends and discuss the lead-zinc market) [Delegate Benefits] Exhibition Area Ticket On-site Check-in Gifts SMM Exclusive Lead-Zinc Industry Distribution Map Lead-Zinc Industry Visitor & Conference Exchange Group Ticket for All Forums of the Conference Executive Dinner Voucher Lunch and Dinner Vouchers During the Conference Enterprise Directory Expert Reports 1-on-1 Supply-Demand Matching Post-Conference Field Trip Activities …… 3. Exhibitor (Step onto the industry stage and showcase your strengths) [18㎡ Custom Booth] [Benefits] Design & construction of all materials for the 18㎡ booth, tables, chairs, sofa & reception desk, TV, 5 conference passes, X-banner stand*1, conference booklet color page*1, LOGO display, multi-platform online exposure and promotion, supply-demand 1-on-1 matchmaking, long-term cooperation support from SMM, etc. [9㎡ Premium Booth] [Benefits] Design & construction of all materials for the 9㎡ booth, printed backdrop wall & reception desk & tables and chairs, TV, 3 conference passes, X-banner stand*1 or conference booklet color page*1, LOGO display, multi-platform online exposure and promotion, supply-demand 1-on-1 matchmaking, long-term cooperation support from SMM, etc. [6㎡ Standard Booth] [Benefits] Design & construction of all materials for the 6㎡ booth, one long table & two chairs, 2 X-banner stands with different content, 2 conference passes, multi-platform online exposure and promotion, supply-demand 1-on-1 matchmaking, long-term cooperation support from SMM, etc.
Oct 22, 2026 09:59 (GMT+8)
2027 Global Aluminum Supply-Demand Outlook: High Margins Drive Expansion, Shifting the Market from Tight to Loose
Oct 21, 2026 09:41 (GMT+8)
Chinese $6Billion Battery Investment in Morocco Reshapes EU Lithium Demand Amid Tariff Shifts
Oct 20, 2026 17:02 (GMT+8)
N-Type vs. P-Type Solar PV Modules: What Sets Them Apart, and Why Is N-Type Gaining Ground in the Global Market?
Oct 21, 2026 09:45 (GMT+8)
China’s Spodumene Imports Rise 7% MoM in September, with Australia, Nigeria and Zimbabwe the Top Three Sources
Oct 20, 2026 19:03 (GMT+8)
[SMM Analysis] Hoa Phat’s record HRC sales reshape Vietnam’s self-sufficiency and China’s export flows
Oct 20, 2026 14:36 (GMT+8)
China's Rare Earth Magnet Exports Hit Record in September, Driven by Backlog Release and Regulatory Easing【SMM Analysis】
Oct 20, 2026 16:06 (GMT+8)
Latest News
Liuzhou Iron & Steel, Huawei deploy Xuantie steel AI model targeting 80% coverage
2 hours ago
[SMM Analysis] Indian flat steel demand supports record JSW sales as coal costs squeeze margins
20 hours ago
Magnesium Prices Fall Nearly 14% in Over Half a Year, Hitting Yearly Low; Low-Priced Supply Hard to Find Support for Rebound [SMM Commentary]
23 hours ago
[SMM Steel] Tight Supply Sends Indonesian Wire Rod Buyers to Small Java Mills Despite Modest Demand
Oct 23, 2026 17:38 (GMT+8)
[SMM Sheets & Plates Daily Review] Demand recovery remains weak; HRC prices may consolidate on a subdued note next week
Oct 23, 2026 17:14 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:49 (GMT+8)
[SMM Steel] India Steel Prices Edge Lower as Buyers Remain Cautious
Oct 23, 2026 16:48 (GMT+8)
[Brief Comment on Domestic Iron Ore] Iron ore concentrate prices in west Liaoning may consolidate
Oct 23, 2026 16:46 (GMT+8)
[SMM Steel] Northwest EU Price Hikes Widen Regional Spread, Elevated Stocks and CBAM Capital Tie-Up Curb Buying
Oct 23, 2026 16:34 (GMT+8)
[SMM Steel] Turkish Rebar: Weak Domestic Intake Drives Prices Down, Export FOB Holds Flat
Oct 23, 2026 16:33 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:31 (GMT+8)
[SMM Steel]
Oct 23, 2026 16:29 (GMT+8)
[SMM India Domestic Market Weekly Review] India Steel Market Remains Subdued Amid Festive Slowdown
Oct 23, 2026 16:25 (GMT+8)
【SMM Analysis】Silicon Steel Import and Export Performance in September: Imports Surge, Exports Diverge
Oct 23, 2026 16:25 (GMT+8)
[SMM's Weekly Review of the Indonesian Market] Weak Demand Keeps Prices Flat to Soft, Buyers Hold Pricing Power
Oct 23, 2026 16:06 (GMT+8)
[Think Tank Warns LNG Power Could Double Electricity Costs for Nippon Steel’s 2 Million mt/yr Yawata EAF]
Oct 23, 2026 16:06 (GMT+8)
[Egypt Sets Up Permanent Billet Supply Committee as Rerollers Push Back on Safeguard Duties]
Oct 23, 2026 16:06 (GMT+8)