

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
[SMM Analysis] India’s BESS Manufacturing Push Accelerates, but Cell Dependence Remains a Key Bottleneck
In the first quarter of 2026, global energy storage system shipments reached 100.0 GWh, a 96.5% increase from 50.9 GWh in the same period of 2025, bringing quarterly shipments to an entirely new scale.
Sep 30, 2026 08:50 (GMT+8)
SMM Launches Aluminium CBAM Calculator: What Cost Estimates Mean for EU-Bound Offers【SMM Analysis】
As the EU Carbon Border Adjustment Mechanism (CBAM) enters its definitive phase, aluminium trade with Europe requires carbon costs to be assessed alongside metal prices, processing charges and logistics. SMM has launched its Aluminium CBAM Calculator , bringing together product codes, origin, emissions data and certificate prices to support export quotations, European procurement and internal budgeting. The aluminium module offers 58 CN codes and 68 origin/default-value categories, covering unwrought aluminium, profiles, sheet, strip, foil and other products. Annual parameters are available for 2026–2030. Users enter a tonnage and select default emissions or enter verified actual emissions. The page then displays estimated certificates per tonne, total certificates, cost per tonne and total budget, with primary and secondary aluminium routes matched to the applicable data basis. The practical benefit is that assumptions and results appear together. Exporters can specify the product, origin, import period and emissions basis behind a quotation, while buyers can compare sources under consistent conditions. The page includes Chinese and English interfaces, parameter tables and a printable cost-sheet option. How the associated costs are shared between buyers and sellers remains a contractual matter. Certificate exposure should be distinguished from its monetary value. As of 29 September 2026, the calculator incorporates official prices of €75.36 per certificate for Q1 2026 and €75.28 for Q2. The Q3 price has not yet been published. Where a price is unavailable, the page retains certificate-volume estimates and leaves costs blank, rather than substituting an assumed price. The current version excludes deductions for carbon prices paid abroad and assessment of the annual import threshold. Its actual-emissions calculation for complex aluminium goods also lacks the free-allocation adjustment attributable to precursors. The analysis below therefore uses the checked default-value calculation. Results are commercial estimates, not final statutory surrender obligations. For market comparisons, the same aluminium product can carry materially different estimated costs depending on its origin-specific default value. Consider CN 76012040—unwrought aluminium alloys in billet form—with primary route K, the Q2 2026 certificate price and a quantity of 1,000 tonnes. Estimated costs under the Chinese, Indian and Canadian default-value cases are €143.98, €50.41 and €57.86 per tonne, respectively. These figures include the annual default-value mark-up and the benchmark-based free-allocation adjustment. The Chinese and Indian default-value cases differ by approximately €93.57 per tonne. Comparing only the metal price or processing charge may therefore miss a meaningful difference in the buyer's budget. Where other commercial terms are similar, estimated CBAM costs could affect an offer's attractiveness. However, this is not a ranking of producers' actual carbon intensity. Freight, customs duties, quality and delivery terms are also outside this comparison, so the figures alone cannot determine the preferred supplier. This highlights the commercial value of supplier emissions documentation. For producers whose actual emissions are below the applicable default value, supported by compliant verification, actual data may change a buyer's cost assessment. Buyers can use defaults for an initial budget when documentation is unavailable, then reassess using supplier evidence. Exporters consequently have a reason to prepare emissions information alongside their product offers, rather than negotiate solely around country-default differences. Annual parameter changes also warrant attention. Holding the Chinese product's base default value, route and benchmark constant, and assuming that the import year and applicable reporting year coincide, estimated certificate exposure rises from 1.912575 per tonne in 2026 to 2.248150 in 2027—an increase of approximately 17.5%. This reflects a higher default-value mark-up and a smaller free-allocation deduction; it does not imply a rise in future certificate prices. For supply arrangements spanning different years, companies can first compare certificate exposure, then discuss price-update mechanisms and cost sharing. Even while future certificate prices remain unknown, identifying that exposure and obtaining supplier documentation can improve the comparability of offers and procurement budgets.
Sep 29, 2026 17:32 (GMT+8)
[SMM Analysis] Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?
[SMM Analysis: Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?] BHP and Amazon’s EAC pilot separates verified emissions reductions from physical copper trade, giving low-emissions primary copper a new source of environmental value. Recycled copper retains a major energy advantage, but future competitiveness may depend more on traceability, recycled content and verified carbon data, potentially adding an environmental dimension to pricing.
Sep 29, 2026 16:03 (GMT+8)
Latest News

Vedanta Plans $2.3 Billion Expansion in India and Saudi Arabia, and Advances Tuticorin Smelter Restart
3 hours ago

London BTC flags copper and antimony at Nevada Black Star
6 hours ago

Kantra extends Nugent copper-gold lode 70m below resource
6 hours ago
Indonesia and Chile Propose Green Minerals Partnership to Boost Critical Minerals and Battery Cooperation
Indonesia and Chile proposed a Green Minerals Partnership to deepen cooperation in copper, aluminium, battery materials, green mining technology and downstream processing, supported by the IC-CEPA.
6 hours ago
Freeport Reports Q3 Copper Production of 830 Million lb as Grasberg Recovery Advances
Freeport-McMoRan reported third-quarter 2026 consolidated copper production of approximately 830 million lb, equivalent to about 376,500 mt, broadly in line with expectations as the company continued the phased recovery of operations at the Grasberg minerals district in Indonesia.
Freeport said slightly stronger results from its international operations offset somewhat lower production from its U.S. mines. Third-quarter copper sales are expected to approximate the company’s July estimate of 750 million lb.
At Grasberg, mill throughput averaged approximately 140,000 mt of ore per day during the quarter, equivalent to around 67% of normalized operating rates before the September 2025 incident. About 70,000 mt/day of the total throughput came from the Grasberg Block Cave underground mine.
Upgrades to the Block Cave material-handling system remain on track for completion in early 2027, while preparations continue for the targeted restart of Production Block 1S by mid-2027. Freeport continues to expect Grasberg to reach approximately 80% of capacity by mid-2027 and approach full capacity by the end of 2027.
PT Freeport Indonesia’s Eastern Java smelter, which had been temporarily suspended following the September 2025 Grasberg incident, restarted operations in late August 2026. Freeport said the smelter ramp-up is progressing in line with expectations. PTFI’s combined smelting capacity, including PT Smelting, is capable of producing up to approximately 800,000 mt/year of copper cathode.
Freeport also said its U.S. operations experienced lower-than-planned operating rates during the third quarter due to localized flooding, power outages and strong winds, while unusually dry conditions in Indonesia created some milling challenges with limited impact to date.
Freeport’s third-quarter production performance indicates that the Grasberg recovery is progressing broadly in line with the company’s expectations, although the operation remains below pre-incident throughput levels. The gradual ramp-up at both the Grasberg Block Cave and the Eastern Java smelter should support improving copper output and downstream processing capacity over the coming quarters. Attention will remain on completion of the material-handling upgrades, the planned restart of Production Block 1S and Freeport’s ability to reach 80% of Grasberg capacity by mid-2027.
6 hours ago
China Seeks Copper Concentrate Supply Commitments for Anglo–Teck Merger Approval
China’s antitrust regulator has asked Anglo American to provide assurances that the combined company resulting from its proposed merger with Teck Resources would maintain a steady supply of copper concentrate to China, according to Reuters, citing three people familiar with the matter.
The request forms part of China’s regulatory review of the proposed US$54 billion Anglo–Teck merger. Reuters reported that the supply assurances are being sought as a condition for Chinese approval of the transaction, although the precise terms of any undertaking have not been publicly disclosed.
The discussions come as Chinese copper smelters face severe constraints in concentrate availability. China accounts for around 60% of global refined copper cathode production, making its smelting industry heavily dependent on reliable supplies of copper concentrate.
Rapid growth in global smelting capacity has outpaced growth in mined copper supply, contributing to a prolonged tightening in the concentrate market. Reuters reported that China’s current feedstock shortage is among the most severe experienced by its copper smelting sector in decades.
Anglo American said it is working constructively with China’s State Administration for Market Regulation as the review progresses. No fixed concentrate volumes or binding supply arrangement have been publicly confirmed.
The proposed merger would combine significant copper assets held by Anglo American and Teck, increasing the enlarged group’s importance in global mined copper supply. Reuters estimates that the combined company would account for approximately 5% of global copper supply.
China’s reported request for copper concentrate supply assurances highlights the importance of feedstock availability to the country’s smelting industry amid a prolonged concentrate shortage. The request indicates that copper concentrate supply security has become an important consideration in China’s review of the Anglo–Teck merger. Attention will now turn to whether the parties agree to any formal supply commitments and whether those conditions affect the timing or structure of the merger approval process.
6 hours ago
Zambia Orders KCM to Remediate Kafue River Pollution as Company Disputes Responsibility
The Zambian government has issued an Environmental Restoration Order to Konkola Copper Mines (KCM) following a pollution incident affecting the Kafue River and its tributaries in Chingola District, while the mining company has disputed claims that its operations caused the pollution.
The incident occurred on September 28, when the Zambia Environmental Management Agency (ZEMA) received notification from KCM's Nchanga Mine of discolouration in the Kafue River. According to the Ministry of Green Economy and Environment, KCM initially attributed the discharge to an infrastructure failure involving a pipe leak at the Tailings Leach Plant and an overflow from a Pollution Control Dam.
A joint inspection involving ZEMA, Mulonga Water Supply and Sanitation Company and KCM personnel subsequently confirmed the presence of a discharge affecting the Chingola Stream, Mushishima Stream and Kafue River. By the time inspectors arrived, the leaking pipe had been repaired and the Pollution Control Dam overflow had been contained.
Preliminary laboratory results showed elevated turbidity and conductivity at the confluence of the Mushishima Stream and Kafue River, while pH levels remained within acceptable limits. Further testing is being conducted to determine heavy-metal levels and other water-quality parameters.
The government has directed KCM to stop discharging effluent from the Tailings Leach Plant into the environment, remove visible tailings material from affected areas, assess the integrity of its Pollution Control Dams and tailings pipelines, and undertake clean-up and remediation of the affected water bodies. A Cost Order has also been issued requiring KCM to meet laboratory analysis and related monitoring costs, while weekly water-quality monitoring is expected to continue.
KCM has rejected allegations that its operations were responsible for the pollution and has called for an evidence-based investigation to determine the source and root cause. The company said it was the first to observe discolouration near the Hippo Pool area and reported the matter to ZEMA. KCM also said its operations had not recorded abnormal pollution levels warranting reporting and that operations were continuing normally.
The incident adds environmental and regulatory scrutiny for KCM at a time when the company is working to rebuild output across its Nchanga and Konkola operations. However, no production disruption has been reported and KCM says operations are continuing normally. Attention will now turn to the outstanding laboratory results, the implementation of the Environmental Restoration Order and whether further regulatory or operational measures follow once the investigation into the source and extent of the pollution is completed.
7 hours ago
【Flash | BHP-Funded Programme Advances Drilling at Argentina’s El Destino Copper-Gold-Molybdenum Target】
Kobrea Exploration Corp. announced the approval of a US$4 million 2026/27 exploration programme for the Western Malargüe Mining District in Mendoza Province, Argentina, fully funded by BHP. The programme includes diamond drilling at the El Destino copper-gold-molybdenum porphyry target, induced-polarisation surveys at El Destino and KBX-17, as well as geological mapping, geochemical sampling and hyperspectral work. The exploration alliance covers seven projects totaling approximately 733 square kilometres, where copper, gold and molybdenum geochemical anomalies have been identified. SMM analysis: approval of the new budget moves the BHP-Kobrea partnership from an alliance framework into an active drilling phase. However, the properties remain at an early exploration stage, with no molybden
11 hours ago
【Flash | Glencore Targets Q1 2027 Environmental Filing for El Pachón Copper-Molybdenum Project】
Glencore plans to submit the environmental impact report for its El Pachón copper-molybdenum project in Argentina in Q1 2027 and aims to secure approval under the Incentive Regime for Large Investments, or RIGI, before July 2027. Glencore previously reported approximately 6 billion tonnes of mineral resources grading an average 0.43% copper, 2.2 g/t silver and 130 g/t molybdenum, equivalent to around 0.013% Mo. Based on the disclosed tonnage and average grade, the resource contains roughly 780,000 tonnes of in-situ molybdenum, although this does not represent reserves, recoverable metal or future production. During the 2025/26 exploration season, the project completed 53 drill holes totaling 21,246 metres and advanced preliminary road and bridge infrastructure.
11 hours ago
【Flash | Glencore Secures RIGI Approval for Argentina’s Agua Rica Copper-Gold-Silver-Molybdenum Project】
Glencore announced that its Agua Rica project, known as MARA, has received approval under Argentina’s Incentive Regime for Large Investments, or RIGI. The large-scale copper-gold-silver-molybdenum deposit contains approximately 1.2 billion tonnes of measured and indicated mineral resources grading an average 0.03% molybdenum. Based on the disclosed tonnage and grade, the resource contains roughly 360,000 tonnes of in-situ molybdenum; however, this does not represent reserves, recoverable metal or future molybdenum production. Glencore also brought forward expected first production from the Alumbrera restart to H2 2027 from H1 2028. Alumbrera’s processing, logistics and workforce infrastructure is expected to support the future development of MARA. SMM analysis: RIGI approval improves the project’s fiscal and regulatory certainty, but no final investment decision, molybdenum recovery plan or molybdenum output guidance has been announced, leaving no direct near-term impact on molybdenum supply.
11 hours ago

【Flash | Sierra Gorda Starts Fourth Grinding Line, Targeting Higher Molybdenum Output from 2030】
12 hours ago
【Flash | Fatal Accident Halts Part of Radomiro Tomic, Molybdenum Impact Not Yet Disclosed】
12 hours ago
Glencore targets 2027 environmental filing for El Pachón
12 hours ago
BHP forms copper exploration alliance with Kobrea in Mendoza
BHP Metals Exploration and Canada's Kobrea Exploration have formed an exploration alliance across Kobrea's seven Western Malargüe copper projects in Mendoza province, Argentina. BHP will pay a one-time US$3 million advance and fund at least US$5 million over an initial two-year project-generation phase. For each selected project, BHP may earn a 75% interest by sole-funding at least US$40 million of exploration over eight years, with up to four projects advancing to joint ventures (BHP 75%, Kobrea 25%). The land package spans 73,334 hectares over prospective copper-gold-molybdenum porphyry terrain. Kobrea's earlier El Perdido campaign completed six holes totalling 2,358 m confirming porphyry mineralisation, and a US$4 million BHP-funded 2026/2027 program with diamond drilling at El Destino has been approved.
12 hours ago
Errington Metals posts maiden resource at Sudbury Basin project
Errington Metals has released a maiden mineral resource estimate for its Sudbury Basin Project in Ontario, totalling 14.2 million tonnes of measured and indicated copper, zinc, lead, gold and silver across the Errington, Vermillion and Balfour deposits. The 5,600-hectare property lies about 25 km northwest of Greater Sudbury and was held by Glencore Canada and predecessors until it went dormant in 2014; Errington acquired it in 2025 and launched exploration. The company is now executing a fully funded drilling program of up to 55,000 m through 2027 to expand the resource base and advance metallurgical studies. All three deposits remain open along strike and at depth, positioning the project as a potential new Canadian supplier of copper, zinc and by-product metals.
12 hours ago
【Flash | UK Expands Iran-Related Controls on Molybdenum Products】
The UK’s strengthened Iran sanctions entered into force on September 29. The new controlled schedules cover molybdenum and related articles under HS 8102 and include uniform spherical or atomised molybdenum and molybdenum-alloy powders containing at least 97% molybdenum with particle sizes of 500 micrometres or less. Restrictions also extend to related supply, delivery, technical assistance, brokering and financial services. SMM analysis: The measures increase compliance barriers for Iran-related high-purity molybdenum trade under UK jurisdiction, although the direct impact on global supply and demand is likely limited because no affected volume was disclosed.
12 hours ago
Copper One starts third hole at Redonda copper-molybdenum project
Copper One Resources (CSE:CEXY) has started drill hole RED-26-03, the third planned hole of its fully funded 2,400 m diamond drilling program at the 100%-owned Redonda copper-molybdenum project on West Redonda Island, British Columbia. RED-26-03 is designed to about 470 m to test the extent and continuity of the interpreted porphyry system. The completed RED-26-02 reached 425.8 m and showed geological and visual mineralisation consistent with the target from roughly 20 m downhole, with native copper visually identified near 40 m pending assay. The 2,746-hectare property sits in BC's Coast Suture Zone; historical work by Teck outlined copper-molybdenum zones open along strike and at depth. Copper One is also preparing a 1,219 m Phase 2 program at its Majuba Hill project in Nevada.
12 hours ago
Panama chamber demands transparency on Cobre Panamá talks
Panama's Chamber of Commerce, Industry and Agriculture (CCIAP) says evaluating a negotiation on Cobre Panamá is reasonable but demands the government keep the process clear and transparent, fully disclosing financial and legal terms to the public. The interministerial report recommends authorising talks with First Quantum on a conditional restart, and President Mulino set six non-negotiable criteria: compliance with the Supreme Court ruling, state sovereignty, zero fiscal cost, verifiable transparency, priority for affected communities, and independent international-standard oversight. The report quantifies the halt's toll — about 1,500 domestic firms lost markets, over 6,000 direct and 30,000 indirect jobs disappeared, and some 144,000 people lost income. Mulino pledged to publish the full report and announce the decision himself.
12 hours ago
Mitsubishi Materials Cuts H2 Japan Refined Copper Plan by 18% on Naoshima and Onahama Smelter Maintenance
Mitsubishi Materials has released its refined copper production plan for October 2026-March 2027, targeting 23,714 tonnes per month, or about 142,284 tonnes for the six-month period. This represents an 18% year-on-year decline and is also well below the 175,416 tonnes planned for April-September. The company attributed the reduction to scheduled maintenance shutdowns at its Naoshima Smelter & Refinery and Onahama Smelting & Refinery.
The new plan implies roughly 31,400 tonnes less refined copper production than the same period a year earlier. Japanese smelter plans are diverging: Furukawa expects output to fall 3% to about 21,500 tonnes, while DOWA targets 4,321 tonnes, around 12% higher year on year. With concentrate availability remaining tight globally, operating rates and maintenance durations at Japanese smelters will be important to monitor through the new October-March production cycle.
12 hours ago
【Flash | Elmet Wins $36 Million DLA Contract for Molybdenum and Tungsten Materials】
Elmet Technologies has been awarded an approximately $36 million contract by the US Defense Logistics Agency to supply the National Defense Stockpile with titanium-zirconium-molybdenum alloy billets, bars and ingots, as well as specialised molybdenum and tungsten wire. The materials are intended for jet-engine components and other high-temperature aerospace applications. Elmet did not disclose delivery volumes, contract duration or the value split between molybdenum and tungsten products. SMM analysis: The award confirms US defence-sector procurement demand for high-performance molybdenum materials, but cannot yet be translated into additional molybdenum consumption due to the absence of physical volumes.
12 hours ago
[SMM Announcement] Chinese Market Metal Prices and News Updates Suspended during National Day Holiday (Oct 1-7)
Dear Valued SMM Users, The National Day holiday is approaching. Please note that SMM Chinese market metal price assessments and news updates will be temporarily suspended during the holiday (October 1-7) and resume normal release after the break. However, SMM overseas price assessment will continue to be updated as usual throughout the holiday. We apologise for any inconvenience caused and wish you a pleasant holiday. Shanghai Metals Market (SMM)
Sep 28, 2026 17:06 (GMT+8)
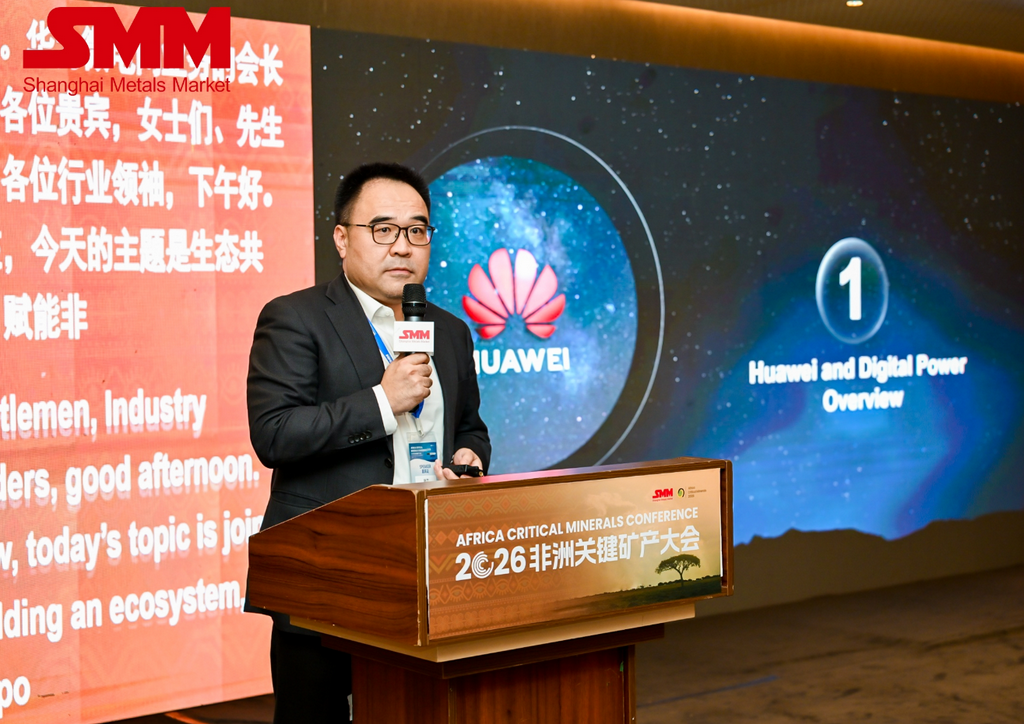
Huawei Pursues Africa Green‑Mining Partnerships and Holds Business Talks with ZESCO at SMM ACM 2026
Sep 23, 2026 16:41 (GMT+8)
[SMM Analysis] The U.S. Copper Tariff Trade Is Fading — but It Isn’t Over Yet
Sep 29, 2026 14:37 (GMT+8)
South Africa Poised to Become Key Player in Global Rare Earth Supply Chain by 2034【SMM Analysis】
Sep 29, 2026 18:54 (GMT+8)
[SMM Analysis] India’s BESS Manufacturing Push Accelerates, but Cell Dependence Remains a Key Bottleneck
Sep 30, 2026 08:50 (GMT+8)
SMM Launches Aluminium CBAM Calculator: What Cost Estimates Mean for EU-Bound Offers【SMM Analysis】
Sep 29, 2026 17:32 (GMT+8)
[SMM Analysis] Low-Carbon of Primary Copper Begin Trading Separately—Will Recycled Copper’s Green Value Be Reassessed?
Sep 29, 2026 16:03 (GMT+8)
Latest News
Vedanta Plans $2.3 Billion Expansion in India and Saudi Arabia, and Advances Tuticorin Smelter Restart
3 hours ago
London BTC flags copper and antimony at Nevada Black Star
6 hours ago
Kantra extends Nugent copper-gold lode 70m below resource
6 hours ago
Indonesia and Chile Propose Green Minerals Partnership to Boost Critical Minerals and Battery Cooperation
6 hours ago
Freeport Reports Q3 Copper Production of 830 Million lb as Grasberg Recovery Advances
6 hours ago
China Seeks Copper Concentrate Supply Commitments for Anglo–Teck Merger Approval
6 hours ago
Zambia Orders KCM to Remediate Kafue River Pollution as Company Disputes Responsibility
7 hours ago
【Flash | BHP-Funded Programme Advances Drilling at Argentina’s El Destino Copper-Gold-Molybdenum Target】
11 hours ago
【Flash | Glencore Targets Q1 2027 Environmental Filing for El Pachón Copper-Molybdenum Project】
11 hours ago
【Flash | Glencore Secures RIGI Approval for Argentina’s Agua Rica Copper-Gold-Silver-Molybdenum Project】
11 hours ago
【Flash | Sierra Gorda Starts Fourth Grinding Line, Targeting Higher Molybdenum Output from 2030】
12 hours ago
【Flash | Fatal Accident Halts Part of Radomiro Tomic, Molybdenum Impact Not Yet Disclosed】
12 hours ago
Glencore targets 2027 environmental filing for El Pachón
12 hours ago
BHP forms copper exploration alliance with Kobrea in Mendoza
12 hours ago
Errington Metals posts maiden resource at Sudbury Basin project
12 hours ago
【Flash | UK Expands Iran-Related Controls on Molybdenum Products】
12 hours ago
Copper One starts third hole at Redonda copper-molybdenum project
12 hours ago
Panama chamber demands transparency on Cobre Panamá talks
12 hours ago
Mitsubishi Materials Cuts H2 Japan Refined Copper Plan by 18% on Naoshima and Onahama Smelter Maintenance
12 hours ago
【Flash | Elmet Wins $36 Million DLA Contract for Molybdenum and Tungsten Materials】
12 hours ago