

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
[SMM Analysis] Those asking "how far will sulfur fall" should consider at least four questions
After sulfur prices dropped sharply from their earlier highs, the market kept circling back to the same question: where will the price settle? It seems simple, but it is the wrong question to ask first. Sulfur's price is never set by a single answer, but by at least four independent questions. Before asking "how far will it fall," these four questions have to be thought through. 1. First, sort out: is this one question, or several? Treating "how far will sulfur fall" as a single question is where most current judgments begin — and it is the biggest mistake. Sulfur's price is never set by a single force. The import channel, domestic supply, downstream substitution, and the shift in demand structure each pull in their own direction, on their own timeline. So the forces that determine the price are not one point, but several independent questions. This is why market views diverge so sharply: some see support abroad, some see pressure at home, some point to low inventories, some to shrinking demand. They are not arguing about the same thing — each is answering one question and then generalizing it into "the price of sulfur." The disagreement stems from a category error, not from conflicting facts. 2. The first question: the import channel, locked by the home-abroad price gap Sulfur is heavily import-dependent, and whether the import channel stays open directly sets the marginal cost of domestic supply. Once the home-abroad price gap inverts far enough, importing becomes unprofitable and voluntary imports stall. At that point the domestic market is no longer priced by "international price plus freight," but by domestic supply "circulating internally." This shift hides a paradox that is often missed: until the overseas price returns to a level that reopens the import window, the domestic market leans on domestic supply — and much of that supply is locked up by the guaranteed-supply mechanism, leaving only a limited portion genuinely available in the open market. The inversion is therefore no longer just a price phenomenon of "support abroad, pressure at home"; it is actively cutting off the import channel and shrinking domestic tradable supply. This question does not depend on when global supply and demand rebalance, but on when the truly tradable supply outside the guaranteed-supply system is exhausted. It asks about supply elasticity, not demand recovery. 3. The second question: the layer of demand that is permanently shaved off A common assumption is that once prices fall far enough, downstream margins recover and demand returns. This assumption misses a structural change — substitution is shaving off a portion of demand permanently, not cyclically. Sulfur's largest downstream is phosphate fertilizer, and the phosphate industry is migrating from "buying sulfur to make acid" toward "making acid from by-product resources." Once this substitution reaches scale, the demand it removes will not return simply because sulfur gets cheaper — because the driver is not only cost, but also environmental constraints and the strategic goal of resource self-sufficiency. This question is the opposite of the first in nature: the first is cyclical — prices recover, margins heal, demand returns; the second is structural — the demand curve shifts down as a whole, and what comes back is permanently less than before. Its implication for price is that even if sulfur rebounds in the future, the historical level it can return to is permanently lower. 4. The third question: the short-term level of the domestic spot market If the question is narrowed to "how much further can spot fall in the near term," the answer becomes clearer. After a rapid slide, the domestic spot market has shown signs of stabilizing. This stabilization comes from several forces stacking up: supply constraints from cost inversion, the relative tightness of tradable supply, and the approach of winter stocking. But the nature of this level must be understood clearly: it is stabilization brought by structural supply tightness and market sentiment, not a demand-driven reversal. The real demand downstream — phosphate operating rates, chemical purchasing — has not fundamentally improved. This short-term level is therefore fragile; its durability depends on whether expectations are realized, not on whether demand itself can support it. 5. The fourth question: the shift in demand structure, rewriting the premise of the first three There is one more variable that is easy to overlook. It belongs to none of the first three questions, yet it sets all three positions in motion: sulfur's demand structure is migrating. Sulfur's downstream is spreading from the traditional fertilizer sector into new energy and fine chemicals. This migration means sulfur's demand elasticity and pricing logic can no longer be explained by the fertilizer seasonality framework. When the demand structure shifts this way, judging sulfur's level by "the fertilizer cycle" may be wrong from the premise. The party that sets the price is changing, and so is its rhythm. A commodity being redefined is having its pricing logic redefined too. This is not a level that can be extrapolated from history — it is a force that erases the original scale on each of the preceding questions. 6. Putting the four questions together The answer then emerges: sulfur's price is not locked by a single answer, but by four questions stacked in layers. The import-channel question, set by the home-abroad gap and domestic guaranteed supply, locks in short-term supply elasticity. The substituted-demand question, set by the spread of substitution, locks in the medium- to long-term position of the demand curve. The short-term spot question, set by sentiment and structural supply, may already have an answer — but it is fragile. The demand-structure question, set by the direction of downstream migration, is rewriting the scale of every question before it. Near term, watch tradable supply and winter stocking; medium term, watch the pace of substitution and new capacity; long term, watch the direction of demand-structure migration. For different participants, the "question" that matters is different: traders care about the window between import contraction and spot tightness; downstream producers care about whether their substitution units come online before the wave of new capacity; long-term investors face a more fundamental question — when substitution permanently takes over a portion of demand, will sulfur's pricing logic be the same as it is today? The price will not give a single answer, because it was never a single question. The real question is not "where will the price settle," but "for me, which question is decisive." Figure that out, and the question is already half answered.
Nov 11, 2026 17:47 (GMT+8)
[SMM Analysis] Gold’s historical cycles and the drivers of 2026 price swings
Gold entered 2026 after an exceptional rally, but the gains proved difficult to sustain. The London Bullion Market Association (LBMA) afternoon gold benchmark ended October at US$3,913 per troy ounce, 10.4% below the end of 2025. Renewed pressure in November showed that buying for long-term security can coexist with sharp selling in financial markets. Understanding that tension requires looking at both the metal people hold and the decisions that move its price.
Nov 13, 2026 22:59 (GMT+8)
Gold – A trend reversal draws closer
The relentless sell-off in the gold market continues. With an intraday low of US$3,852, bears pushed the gold price yesterday to its lowest level since October 3, 2025.
Nov 16, 2026 17:08 (GMT+8)
Latest News
‘We believe gold and silver are not simply defensive assets’ – BlackRock’s Akullian
Nov 13, 2026 13:13 (GMT+8)
Silver price: Sixth consecutive supply deficit—when will the breakout come?
Nov 13, 2026 11:50 (GMT+8)
[SMM Macro Analysis] Strong US Data Boosts Rate Hike Expectations, Pressuring Precious Metals
Nov 12, 2026 11:51 (GMT+8)
US Oct CPI Rises More Than Expected, Boosting Bets on 50bp Rate Hike in December
[SMM Precious Metal Express] US October CPI rose 0.4% month-on-month, with core CPI up 0.3%, both exceeding market expectations and reaching the "significant rate hike threshold" previously mentioned by Waller. The Bureau of Labor Statistics said that due to last year's government shutdown, no year-on-year CPI data for October will be published, leaving markets pricing in a "semi-blind" state with only month-on-month figures, naturally amplifying volatility. Markets raised bets on a 50bp rate hike in December.
Nov 11, 2026 09:09 (GMT+8)
Fed Officials Advocate for Further Rate Hikes Amid Inflation Concerns
[SMM Precious Metal Express] Four Fed officials struck hawkish tones on the same day. Waller supports a December rate hike and is open to 50bp; Logan still sees at least two 25bp hikes needed, possibly at a faster pace than this autumn; Schmid said the current rate level is "quite accommodative" and inflation remains the top concern; Bowman said inflation still needs to be controlled but the costs of further tightening must be weighed. Officials expect October core PCE to rise 3.3% year-on-year.
Nov 11, 2026 09:09 (GMT+8)
World Bank sees gold holding above $4,000 through 2028, but warns silver faces steeper correction
(Kitco News) - Gold and silver prices are expected to remain historically elevated through 2027, but investors should not expect a repeat of the explosive gains and volatility that defined 2026, according to the latest report from the World Bank.
Nov 06, 2026 16:59 (GMT+8)
Silver Ingot Hong Kong Spot Premium Closes at -$0.15 to $0/oz Amid Price Rally
[SMM Silver Express] SMM November 5: This week, silver ingot Hong Kong spot premium (vs. LBMA silver) closed at -$0.15 to $0/oz. General trade import buying prices were concentrated at -$0.10 to $0/oz. Affected by yesterday's continued rally in silver prices, export offer discounts widened, concentrating at -$0.15 to -$0.10/oz.
Nov 05, 2026 12:12 (GMT+8)
Gold and silver selloff is the buying opportunity of the decade - Bawden Capital
Nov 05, 2026 10:21 (GMT+8)
Gold and silver: Forced selling gives rise to record rallies
Nov 05, 2026 10:04 (GMT+8)
SMM 1# Silver Output Drops 5.03% MoM in Oct, Yearly Production Up 3.72% YoY
[SMM Silver Express] SMM 1# silver production fell 5.03% month-on-month in October 2026; cumulative production for the year reached approximately 16,000 tonnes, up 3.72% year-on-year.
Nov 04, 2026 09:59 (GMT+8)
[SMM Analysis] Silver Production Drops 5.03% in October 2026, PV Sector Sees 13.48% Decline
Nov 03, 2026 19:28 (GMT+8)
Silver price poised for a comeback? India's import approval fuels speculation
Nov 03, 2026 15:59 (GMT+8)
Silver could see further losses against gold as physical market weakens - Metals Focus
Oct 30, 2026 15:53 (GMT+8)
Vedanta Commissions Gamsberg Phase II; Zinc-in-Concentrate Capacity Rises to Around 500,000 mt/year
Vedanta said on October 28 that the Gamsberg Phase II concentrator in South Africa was commissioned during Q2 FY2027, with first metal in concentrate produced in September. The approximately $595 million project adds 200,000 mt/year of contained zinc capacity, raising Gamsberg’s total capacity to around 500,000 mt/year. The new concentrator is currently processing an average of approximately 400 mt/hour, equivalent to 70% of its rated capacity, and remains in the stabilisation and ramp-up stage. Gamsberg’s production cost, including treatment charges, reached $1,533/mt in Q2, up from $1,282/mt a year earlier, while Vedanta maintained its FY2027 cost guidance of $1,500–1,550/mt. Zinc International produced 53,000 mt of metal in concentrate during the quarter, down 12% year on year but up 9% quarter on quarter, including 7,100 mt from Black Mountain. Zinc India reported record Q2 mined-metal production of 271,000 mt, alongside refined-metal output of 264,000 mt and silver production of 173 mt.
Oct 29, 2026 20:43 (GMT+8)
[SMM Macro Analysis] FOMC Holds Rates, Hawkish Tone Weighs on Precious Metals Amid Geopolitical Tensions
The US Fed kept rates unchanged in October, but a hawkish 10:2 vote continues to weigh on precious metals. Strong US dollar, rising yields, and oil-driven inflation create persistent upward resistance. However, steady central bank gold buying and oversold recovery demand provide key downside support, likely leading to short-term sideways consolidation as focus shifts to upcoming inflation data and December rate guidance.
Oct 29, 2026 17:08 (GMT+8)
US Treasury to Buy Back Bonds, US-Canada Trade Talks Intensify, UK PM Hopes for EU Re-entry
[SMM Precious Metal Express] The US Treasury will buy back up to $6 billion of longer-dated bonds on Tuesday. US-Canada trade talks have accelerated but no deal has been reached. The UK Prime Minister said he hopes to see Britain rejoin the EU in his lifetime.
Oct 28, 2026 17:56 (GMT+8)
Silver price: Correction brings key $50 level into focus
Oct 26, 2026 16:42 (GMT+8)
Oil shock and Fed rate fears: Gold below $4,100, silver falls sharply
Oct 26, 2026 16:16 (GMT+8)
Gold at USD 6,000, silver at USD 90: Metals Focus remains bullish for 2027
Oct 23, 2026 11:30 (GMT+8)
[SMM Silver Analysis] China's Silver Imports Increase, Exports Decline in September Amid Price Ratios and Policy Shifts
According to data from China Customs, China's exports of 99.99% unwrought silver totaled 309.77 mt in September 2026, down 23.7% MoM. Cumulative exports in January-September reached 3,341.28 mt, down 8.2% YoY. On the import side, imports of 99.99% unwrought silver came to 114.93 mt in September, up 73.5% MoM. Cumulative silver ingot imports in 2026 reached 1,066.32 mt.
Oct 21, 2026 22:09 (GMT+8)
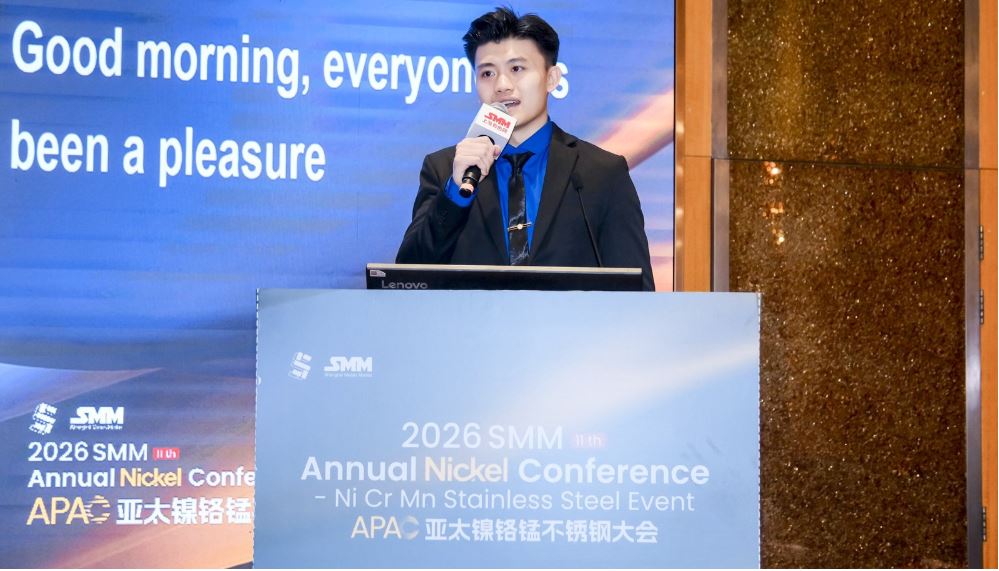
Key Takeaways from SMM NCMSS2026: Nickel Ore Equation — Indonesia's Policy Stack, HPM Gap and a Structural Tight Balance
On November 13, the (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event, hosted by Shanghai Metals Market (SMM), concluded successfully in Shanghai, China. Enzo Brooklyn, Senior Analyst of Indonesia Nickel Industry Chain at SMM, delivered a presentation titled "The Nickel Ore Equation — Indonesia's Policy Stack, the HPM Gap and a Structural Tight Balance."
14 hours ago
SMM Net Zero Europe 2026: Navigating Europe’s Energy Transition, Opening a New Chapter for PV+ESS
Nov 13, 2026 13:27 (GMT+8)
Gold Price Forecast: UBS's $4,000 Support Call Tested As Bullion Falls To $3,942
Nov 13, 2026 13:15 (GMT+8)
India Bans Lithium-Ion Battery Black Mass Exports to Boost Domestic Recycling Capacity
Nov 12, 2026 19:31 (GMT+8)
[SMM Analysis] Those asking "how far will sulfur fall" should consider at least four questions
Nov 11, 2026 17:47 (GMT+8)
[SMM Analysis] Gold’s historical cycles and the drivers of 2026 price swings
Nov 13, 2026 22:59 (GMT+8)
Gold – A trend reversal draws closer
Nov 16, 2026 17:08 (GMT+8)
Latest News
‘We believe gold and silver are not simply defensive assets’ – BlackRock’s Akullian
Nov 13, 2026 13:13 (GMT+8)
Silver price: Sixth consecutive supply deficit—when will the breakout come?
Nov 13, 2026 11:50 (GMT+8)
[SMM Macro Analysis] Strong US Data Boosts Rate Hike Expectations, Pressuring Precious Metals
Nov 12, 2026 11:51 (GMT+8)
US Oct CPI Rises More Than Expected, Boosting Bets on 50bp Rate Hike in December
Nov 11, 2026 09:09 (GMT+8)
Fed Officials Advocate for Further Rate Hikes Amid Inflation Concerns
Nov 11, 2026 09:09 (GMT+8)
World Bank sees gold holding above $4,000 through 2028, but warns silver faces steeper correction
Nov 06, 2026 16:59 (GMT+8)
Silver Ingot Hong Kong Spot Premium Closes at -$0.15 to $0/oz Amid Price Rally
Nov 05, 2026 12:12 (GMT+8)
Gold and silver selloff is the buying opportunity of the decade - Bawden Capital
Nov 05, 2026 10:21 (GMT+8)
Gold and silver: Forced selling gives rise to record rallies
Nov 05, 2026 10:04 (GMT+8)
SMM 1# Silver Output Drops 5.03% MoM in Oct, Yearly Production Up 3.72% YoY
Nov 04, 2026 09:59 (GMT+8)
[SMM Analysis] Silver Production Drops 5.03% in October 2026, PV Sector Sees 13.48% Decline
Nov 03, 2026 19:28 (GMT+8)
Silver price poised for a comeback? India's import approval fuels speculation
Nov 03, 2026 15:59 (GMT+8)
Silver could see further losses against gold as physical market weakens - Metals Focus
Oct 30, 2026 15:53 (GMT+8)
Vedanta Commissions Gamsberg Phase II; Zinc-in-Concentrate Capacity Rises to Around 500,000 mt/year
Oct 29, 2026 20:43 (GMT+8)
[SMM Macro Analysis] FOMC Holds Rates, Hawkish Tone Weighs on Precious Metals Amid Geopolitical Tensions
Oct 29, 2026 17:08 (GMT+8)
US Treasury to Buy Back Bonds, US-Canada Trade Talks Intensify, UK PM Hopes for EU Re-entry
Oct 28, 2026 17:56 (GMT+8)
Silver price: Correction brings key $50 level into focus
Oct 26, 2026 16:42 (GMT+8)
Oil shock and Fed rate fears: Gold below $4,100, silver falls sharply
Oct 26, 2026 16:16 (GMT+8)
Gold at USD 6,000, silver at USD 90: Metals Focus remains bullish for 2027
Oct 23, 2026 11:30 (GMT+8)
[SMM Silver Analysis] China's Silver Imports Increase, Exports Decline in September Amid Price Ratios and Policy Shifts
Oct 21, 2026 22:09 (GMT+8)