Key Takeaway from SMM 2023 Indonesia Nickel and Cobalt Industry Chain Conference: Macquarie Group Says Nickel Demand Growth Will Outpace Lithium, with Battery Being Major Driver

Published: May 31, 2023 14:05
Source: SMM
SHANGHAI, May 31 (SMM) - At the SMM 2023 Indonesia Nickel and Cobalt Industry Chain Conference, Jim Lennon, senior commodity consultant at Macquarie Group, made a detailed analysis of Indonesia's role in meeting the soaring demand for nickel.
SHANGHAI, May 31 (SMM) - At the SMM 2023 Indonesia Nickel and Cobalt Industry Chain Conference, Jim Lennon, senior commodity consultant at Macquarie Group, made a detailed analysis of Indonesia's role in meeting the soaring demand for nickel.

Jim Lennon said that global nickel supply growth has been strong in recent years, contributed by Indonesia. Nickel is currently a value-added product that contributes significantly to Indonesia's export earnings. Indonesia's planned total nickel production capacity currently exceeds 5 million mt/year, compared with global nickel production of 3.1 million mt in 2022. After losing 100,000 mt of nickel production in 2021 due to the pandemic and other factors, Indonesia began to increase production capacity to catch up. From 2022 to 2029, Indonesia's nickel production will account for more than 75% of the global supply.

Demand for nickel in batteries is expected to grow strongly through 2030. The future race for high-nickel batteries means that demand growth for nickel is likely to outpace that for lithium, with cobalt lagging behind.
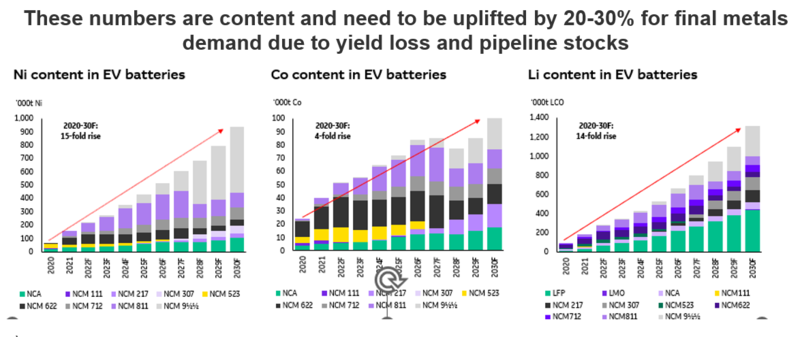
Total global EV demand for primary mines will peak in mid-2030 as secondary mines emerge - thus concerns of depleting reserves are less of a concern.

The supply of Indonesian nickel will no longer be an issue, but the type of supply and restrictions will become the main issue. Strong Indonesian supply and slowing demand caused global nickel supply to record a surplus ofr the first time in 2022. What was in surplus was not (LME deliverable) nickel metal, but rather NPI and ferronickel. Prices of LME and SHFE nickel saw an unprecedented premium over NPI and ferronickel. Considering the underutilization of nickel production capacity in Indonesia, the market may continue to be in surplus in the next five years.

Stainless steel dominates the use of nickel, and batteries are the second-largest use of nickel and nickel demand from batteries is growing rapidly. In 2022-2023, nickel use in battery and stainless steel declined due to the use of NPI and intermediate products, leading to a surplus of nickel.

Global markets are increasingly concerned about dependence on Indonesian nickel supply from a state dependence (including Chinese control) and ESG perspective. Indonesia now needs to carefully manage the next phase of nickel supply growth against a backdrop of growing concerns over the “localization” of battery supply chains in North America and Europe. Significant regional price variations for nickel battery raw materials (mainly sulphates) are increasingly likely, with potential premiums for non-Indonesian/Chinese materials also increasing.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Nickel Morning Meeting Summary] US Stocks Rebound, Macro Pressure Eases, the Most-Traded SHFE Nickel Contract Edges Up in Early Trading
9 hours ago
[SMM Nickel Morning Meeting Summary] US Stocks Rebound, Macro Pressure Eases, the Most-Traded SHFE Nickel Contract Edges Up in Early Trading
Read More
[SMM Nickel Morning Meeting Summary] US Stocks Rebound, Macro Pressure Eases, the Most-Traded SHFE Nickel Contract Edges Up in Early Trading
[SMM Nickel Morning Meeting Summary] US Stocks Rebound, Macro Pressure Eases, the Most-Traded SHFE Nickel Contract Edges Up in Early Trading
[9.21 Morning Meeting Notes] After the rate hike landed, US stocks rallied across the board, with a "bad news exhausted" rally unfolding. Overnight, the Dow rose 0.61%, the S&P 500 gained 1.14%, the Nasdaq advanced 1.69%, and the Philadelphia Semiconductor Index surged 3.14% (Arm up 8%, Intel up 7%, AMD/SanDisk up 6%); the 10-year Treasury yield pulled back from 5.02% to 4.94%, and the US dollar index edged down to 100.22. After the market digested the hawkish dot plot, risk appetite recovered, and European stocks closed higher in tandem. The most-traded SHFE nickel contract (2610) retreated after a rapid rise in early trading, closing the morning session at 123,640 yuan/mt, up 0.62%. After the US Fed's rate hike landed, global risk appetite recovered, and macro pressure eased in stages; SHFE nickel's rebound momentum remained mild, and with nickel's own high inventory and weak demand pattern unchanged, in the short term, the most-traded SHFE nickel contract price is expected to trade in the range of 122,000-126,000 yuan/mt.
9 hours ago
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
9 hours ago
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
Read More
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
NBS data shows that China's sulphuric acid (100% equivalent) production in August was 7.984 million mt, down 308,000 mt from 7.676 million mt in July, a YoY decline of 15.5%. The cumulative production of sulphuric acid (100% equivalent) in 2026 was 68.141 million mt, a cumulative YoY decline of 4.6%.
9 hours ago
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
14 hours ago
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
Read More
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
In August 2026, China's total monthly sulphur imports were 272,323.414 mt in physical content, down 29.34% MoM and down 65.03% YoY, with the main import sources being the UAE, South Korea, Canada, Japan, Kazakhstan, Vietnam, Singapore, and the Philippines. China's total monthly sulphur exports were 48 mt in physical content, down 96.34% MoM and up 26.32% YoY, with the main export destinations being Indonesia and South Korea. China's total monthly sulphuric acid imports were 9,938.436 mt in physical content, up 831.85% MoM and up 1,051.37% YoY, with the main import sources being South Korea, Taiwan, China, Germany, and the US. China's total monthly sulphuric acid exports were 2,474.46 mt in physical content, up 153.47% MoM and down 99.43% YoY, with the main export destinations being Angola, Ghana, Cambodia, Hong Kong, China, Vietnam, Singapore, Malaysia, and Tanzania.
14 hours ago

