Low-Carbon Steelmaking Pathways for Automotive Steel Producers
In response to global trends and the low-carbon demands of automotive end-users, steel producers actively promote the R&D and production of low-carbon automotive steel technologies.
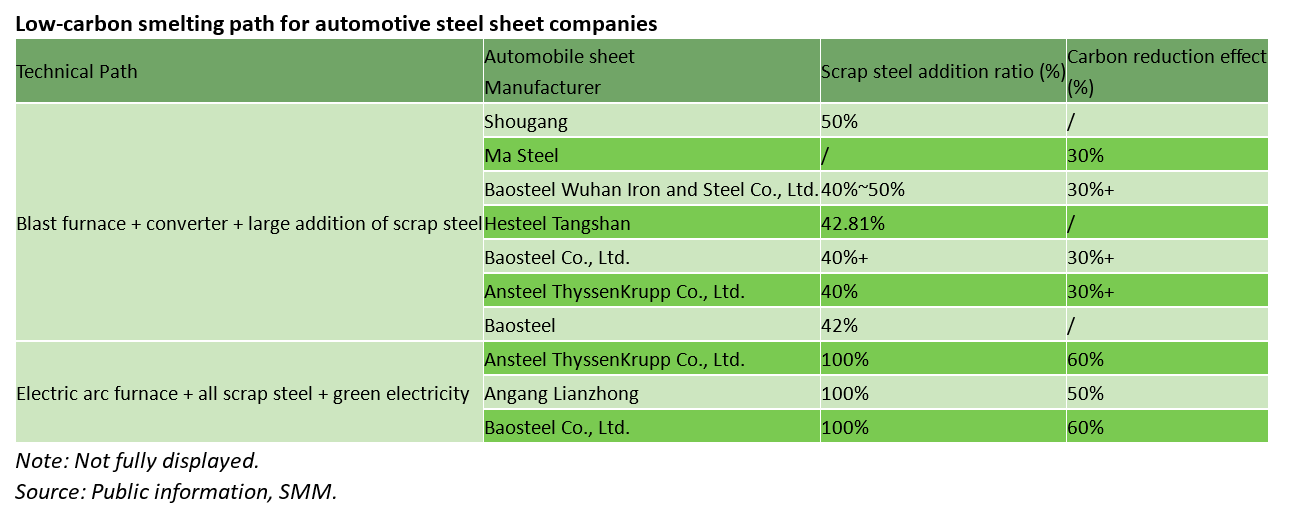
At the beginning of 2024, Shougang Jingtang adopted an extreme carbon reduction approach across the entire process. In the ironmaking stage, they used a high proportion of pellet smelting technology, with the pellet ratio exceeding 50%, achieving efficient and low-consumption blast furnace smelting. In the steelmaking stage, they focused on a smelting technology with a high steel scrap ratio, gradually building the capacity for mass production with over 50% steel scrap ratio, driving product diversification and high-end development and helping establish Shougang Jingtang's unique low-carbon converter steelmaking process with a high steel scrap ratio. As the transformation demand for green and low-carbon supply chains from automotive OEMs surged, automotive sheet producers have been upgrading their steelmaking pathways to meet low-carbon purposes. Steel producers like Baosteel, HIBS, Masteel, and TAGAL have all achieved remarkable performance in this field.
"Blast furnace + converter + large amounts of steel scrap" and "electric furnace with all steel scrap + green electricity" are currently the main low-carbon steelmaking pathways. Although in the short term, adding steel scrap increases additional energy costs and the cost per ton of molten steel, this technological pathway transformation can effectively reduce carbon emissions in blast furnace steel production in the long term, providing strong support for the expansion of steel products into the low-carbon sector.
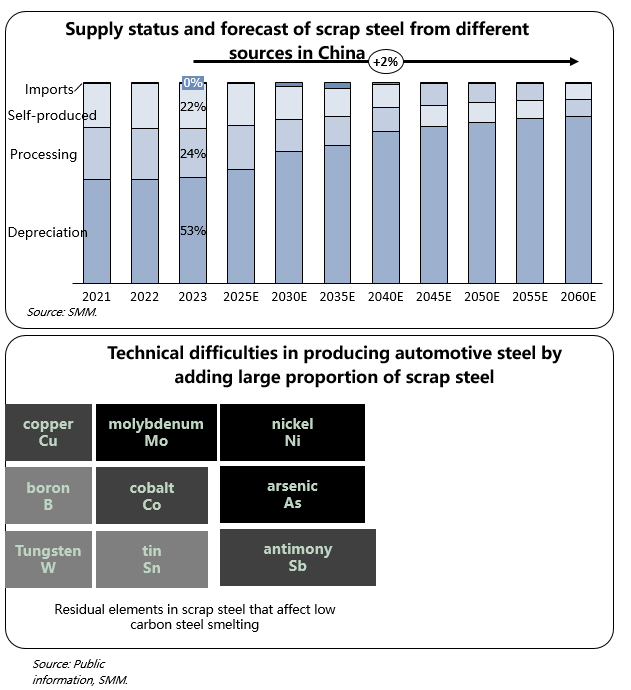
 Technical challenges of producing automotive steel with a high proportion of steel scrap
There are technical challenges in controlling residual elements when adding a large proportion of steel scrap, and automotive sheets have stricter requirements for residual elements
Automotive sheets are one of the steel products with the strictest requirements for residual elements. The C, N, and residual elements in the steel significantly affect its performance and surface quality. As high-end automotive users increasingly demand higher purity and deep drawing performance for automotive sheets, controlling residual elements in steel has become the biggest technical challenge, whether in the blast furnace-converter-high steel scrap addition ratio process or the electric furnace-steel scrap production process.
Residual elements such as Cu, Ni, Cr, and Sn in molten steel are mainly affected by steel scrap and raw materials in furnaces. In the Chinese market, depreciation scrap is the primary supply source, accounting for more than 50% of steel scrap supply in 2023, followed by self-produced and processed steel scrap, with supply proportions of 22% and 24%, respectively. At present, the supply of depreciation scrap cannot meet the requirements for automotive sheet smelting. On the one hand, steel producers need to control the quality by managing the steel scrap supply chain at the source; on the other hand, they need to increase the proportion of recycled processed steel scrap (such as stamping off-cuts, turnings, and heads generated during the automotive production process) through strategic cooperation agreements with downstream companies to ensure high-quality steel scrap addition and reduce residual elements in the steel. The international automotive parts producer Gestamp has achieved a 70% increase in steel scrap utilization through cooperation with Tata Steel UK. Additionally, Gestamp has signed a circular economy cooperation agreement with ArcelorMittal.
Deep Drawing Performance: Residual elements have a low melting point. Low melting point substances continuously diffuse along the interior during the solidification process of continuous casting billets, forming segregation. This results in defects such as element enrichment and agglomeration at the end of solidification, reducing the internal structure density of billets and the dynamic performance of the material structure during rolling, adversely affecting the deep drawing performance of low-carbon steel for automotive sheets.
Plasticity, Toughness, and Cold Working Performance: Excess nitrogen affects the timeliness and blue brittleness of low-carbon automotive steel and reduces the plasticity, toughness, and cold working performance of steel. Excess carbon also reduces the plasticity and stamping performance of steel.
The melting rate of steel scrap is also one of the reasons limiting a high steel scrap ratio in the converter.
In the blast furnace-converter process, CO2 emissions are mainly concentrated in the ironmaking process. Reducing the amount of pig iron and increasing the proportion of high-quality steel scrap or DRI is the most effective method for carbon reduction. However, the process leads to insufficient heat in the converter, extending the converter smelting cycle and increasing the difficulty of cost control in the entire steelmaking process.
On the one hand, steel companies are vigorously developing rapid steel scrap addition and melting processes, combining the converter iron pouring process and the melting requirements of different types of steel scrap to increase the efficiency of converter steel scrap processing and the melting efficiency of steel scrap during the smelting process, thereby increasing the proportion of steel scrap in the converter. On the other hand, by developing ladle cover and pig iron ladle cover technologies, as well as improving the compactness of production organization and the level of smelting operations, the heat loss during converter smelting is reduced, and the melting rate of steel scrap is increased.
Additionally, the shape, size, and carbon content of steel scrap affect its melting time in the converter. Therefore, steel companies should measure basic parameters such as the yield of different types of steel scrap on the market and accurately establish the relationship between various steel scraps and the composition, temperature, and smelting time of the molten pool in converter steelmaking.
Low-Carbon Transition Goals for Automakers: Comprehensive Implementation from Manufacturing to Supply Chain
Automotive OEMs have set life-cycle decarbonization goals aimed at promoting the low-carbon transition of the entire industry chain.
At this critical moment in addressing global climate change challenges, the Chinese government has clearly stated its ambition to achieve carbon peak by 2030 and carbon neutrality by 2060. The Chinese automotive industry plays a significant role in achieving this goal. As the industry transitions from internal combustion engine vehicles (ICE) to battery electric vehicles (BEV), emissions during the vehicle usage phase have significantly decreased. However, the production processes of high-energy-consuming and high-emission automotive materials (such as steel, aluminum, and plastic) present new challenges for the industry's successful decarbonization. The production of automotive materials accounts for approximately 18% to 22% of the total life cycle emissions of ICEVs. Therefore, promoting low-carbon transitions at the raw material end is crucial for achieving the carbon reduction and decarbonization goals in the automotive industry.
Leading global automakers have announced their carbon neutrality plans, including target years for achieving carbon neutrality, overall carbon emission targets, and emission reduction targets for both the manufacturing and supply chain ends. They ensure the effective execution of their group's carbon reduction goals through measures such as building zero-carbon factories and setting clear emission reduction targets for each supply and manufacturing end. This presents both opportunities and challenges for every participant in the automotive value chain.
Overview of global automakers' carbon neutrality plans
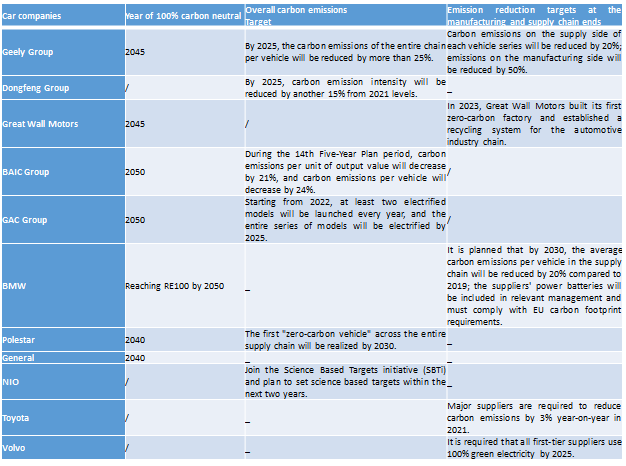
Note: Only some of the car companies' plans are displayed, and the statistics are up to May 2024.
Source: Public information, SMM.