SHANGHAI, Jul 1 (SMM) - This is a roundup of China's metals weekly inventory as of July 1.
Aluminium Ingot and Billet Inventory Slowing the De-stocking Speed
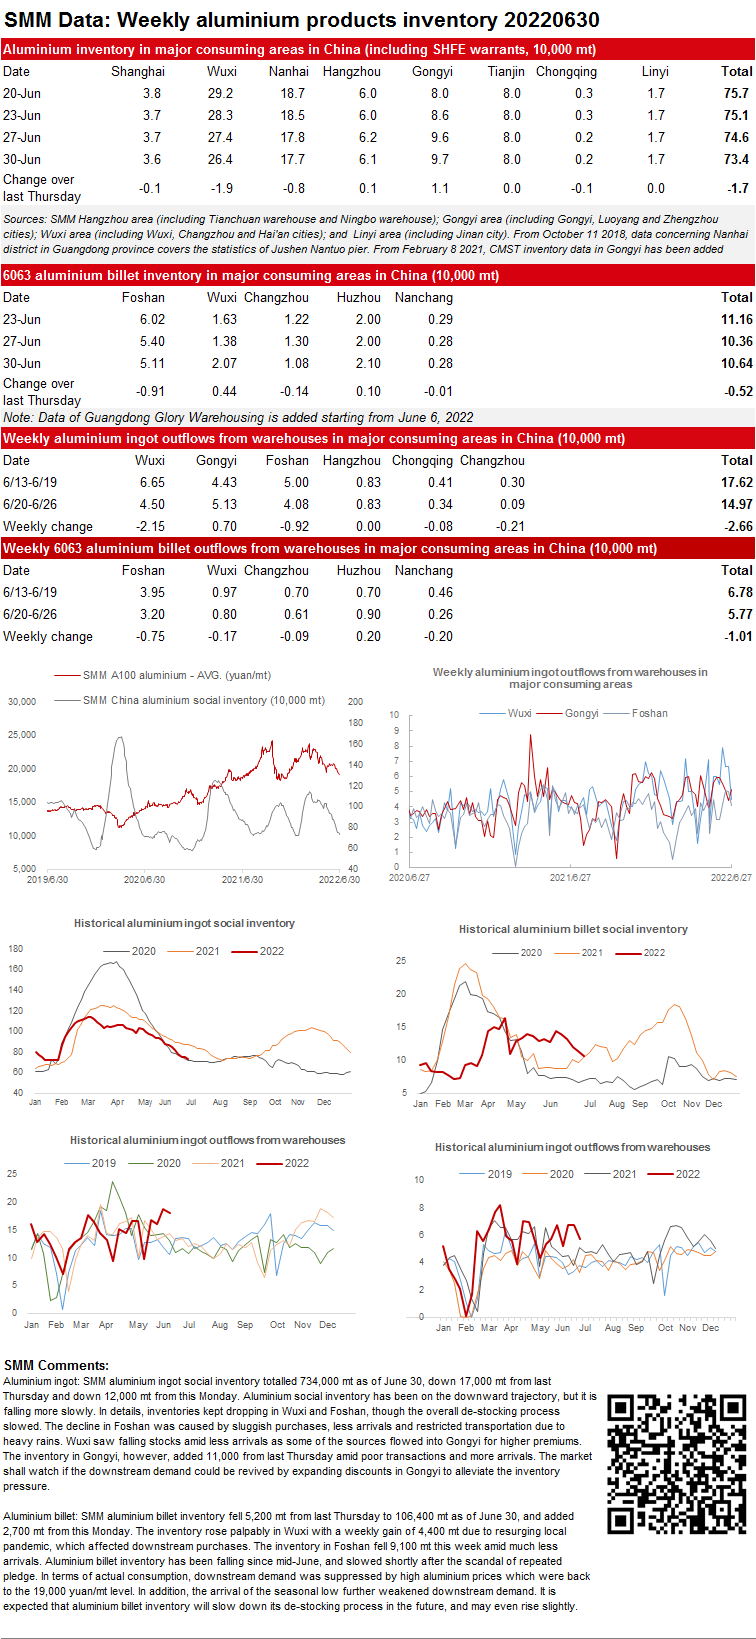
SMM aluminium ingot social inventory totalled 734,000 mt as of June 30, down 17,000 mt from last Thursday and down 12,000 mt from this Monday. Aluminium social inventory has been on the downward trajectory, but it is falling more slowly. In details, inventories kept dropping in Wuxi and Foshan, though the overall de-stocking process slowed. The decline in Foshan was caused by sluggish purchases, less arrivals and restricted transportation due to heavy rains. Wuxi saw falling stocks amid less arrivals as some of the sources flowed into Gongyi for higher premiums. The inventory in Gongyi, however, added 11,000 from last Thursday amid poor transactions and more arrivals. The market shall watch if the downstream demand could be revived by expanding discounts in Gongyi to alleviate the inventory pressure.
SMM aluminium billet inventory fell 5,200 mt from last Thursday to 106,400 mt as of June 30, and added 2,700 mt from this Monday. The inventory rose palpably in Wuxi with a weekly gain of 4,400 mt due to resurging local pandemic, which affected downstream purchases. The inventory in Foshan fell 9,100 mt this week amid much less arrivals. Aluminium billet inventory has been falling since mid-June, and slowed shortly after the scandal of repeated pledge. In terms of actual consumption, downstream demand was suppressed by high aluminium prices which were back to the 19,000 yuan/mt level. In addition, the arrival of the seasonal low further weakened downstream demand. It is expected that aluminium billet inventory will slow down its de-stocking process in the future, and may even rise slightly.
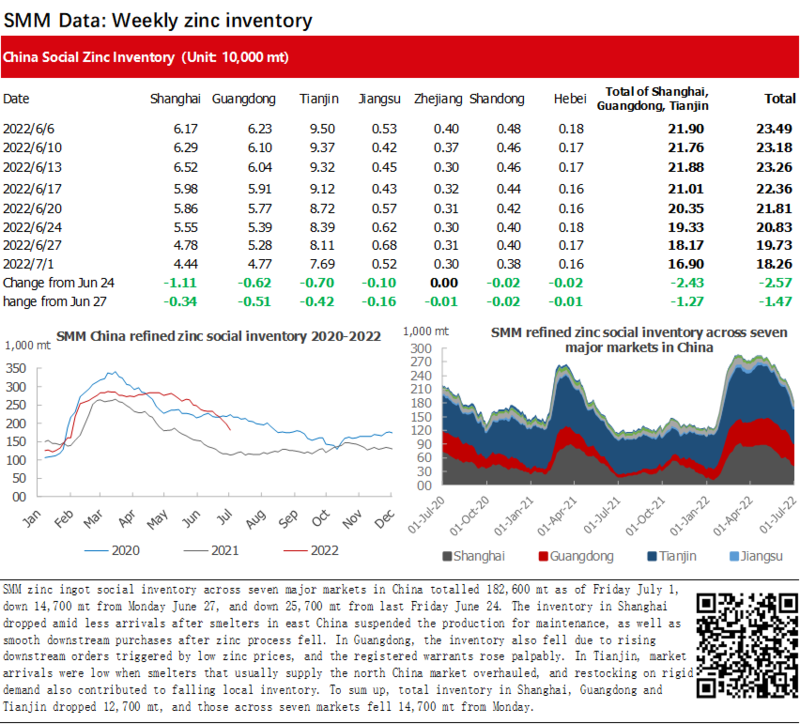
SMM Zinc Ingot Social Inventory Down 14,700 mt from Monday
SMM zinc ingot social inventory across seven major markets in China totalled 182,600 mt as of Friday July 1, down 14,700 mt from Monday June 27, and down 25,700 mt from last Friday June 24. The inventory in Shanghai dropped amid less arrivals after smelters in east China suspended the production for maintenance, as well as smooth downstream purchases after zinc process fell. In Guangdong, the inventory also fell due to rising downstream orders triggered by low zinc prices, and the registered warrants rose palpably. In Tianjin, market arrivals were low when smelters that usually supply the north China market overhauled, and restocking on rigid demand also contributed to falling local inventory. To sum up, total inventory in Shanghai, Guangdong and Tianjin dropped 12,700 mt, and those across seven markets fell 14,700 mt from Monday.
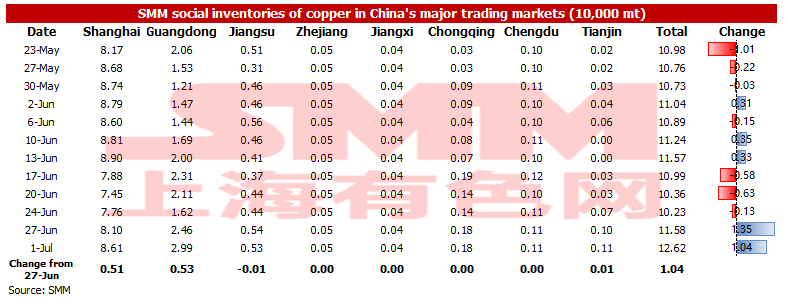
Copper Inventory in Major Chinese Markets Added 10,400 mt from Monday
As of Friday July 1, SMM copper inventory across major Chinese markets increased by 10,400 mt from Monday to 126,200 mt, up by 23,900 mt from last Friday. Compared with Monday's data, the inventories across China increased. The total inventory dropped by 106,500 mt compared with the same period last year when the inventory was recorded at 232,700 mt. Among them, the inventory in Guangdong dropped by 60,000 mt, the inventory in Shanghai dipped by 26,400 mt, and the inventory in Jiangsu fell by 14,000 mt. The increase in inventory this week is contributed by, first of all, smelters actively ship goods to the warehouses to relieve their inventory pressure approaching the mid-year. Secondly, downstream funds are tight and they are unwilling to make excessive restock amid falling copper prices. Thirdly, the imported copper continuously flows into the domestic market.
In detail, the inventory in Shanghai increased by 5,100 mt to 86,100 mt, the inventory in Guangdong rose by 5,300 mt to 29,900 mt, and the inventory in Tianjin added 100 mt to 1,100 mt.
Looking forward, the arrival of domestic and imported copper may fall further, while the consumption will recover somewhat. Therefore, SMM expects that the weekly inventory will drop slightly next week, and in the short term, the inventory may reach a low level.
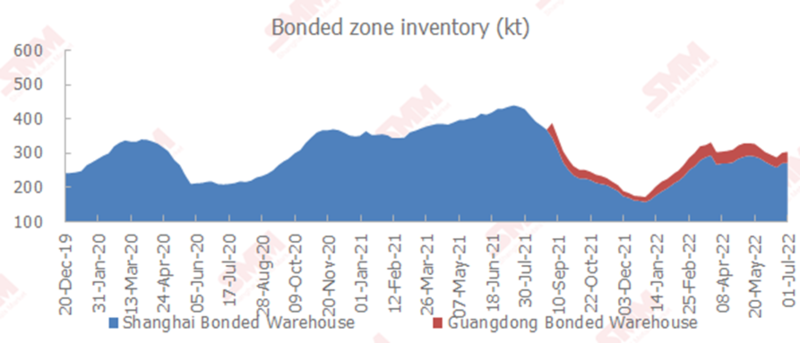
Copper Inventory in China Bonded Zone Dropped by 9,600 mt on Week
Copper inventories in domestic bonded zones fell by 9,600 mt from last Friday June 24 to 294,000 mt as of July 1, according to SMM survey. The inventory in Shanghai bonded zone decreased by 9,500 mt to 262,000 mt, while that in Guangdong fell by 100 mt to 32,000 mt. The import window opened in the past two weeks. Import profits enabled the importers to continuously declare customs of warrants at bonded warehouses this week, driving the bonded zone inventory to drop.
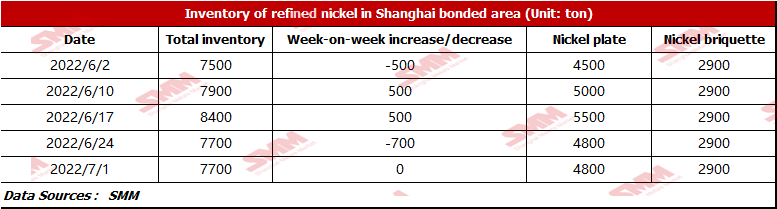
Bonded Zone Inventory of Nickel Stayed almost Unchanged this Week as the Price Ratio Narrowed
The price ratio has been narrowed recently due to the falling overseas nickel prices and the rising premiums of US dollars in the bonded zone. According to SMM research, the bonded zone inventory stood at 7,700 mt this week, flat from the previous week. The inventory of nickel briquette was 2,900 mt, and that of nickel plate was 4,800 mt. Bonded zone inventory stayed unchanged this week as the downstream demand of pure nickel remained weak and some overseas pure nickel had yet to arrive at ports.
Silicon Metal Inventory Flat from a Week Ago
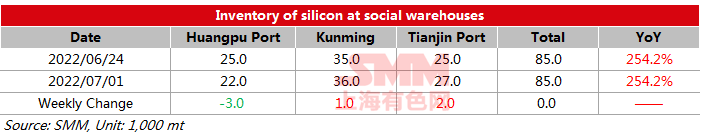
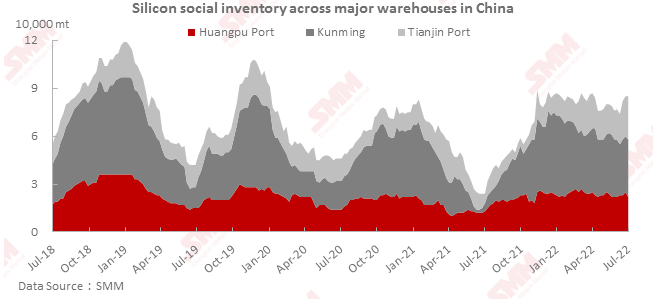
SMM silicon metal inventory across three major markets in China totaled 85,000 mt as of July 1, flat from a week ago. The inventory in Kunming rose amid poor transactions, while that at Tianjin port also rose due to more arrivals from smelters in Xinjiang and traders. The inventory at Huangpugang port fell slightly amid centralized delivery at the end of the month.
The overall inventory is likely to rise slightly next week as the market has been in a stalemate after silicon metal prices fall.
Nickel Ore Inventories at Chinese Ports Fell 120,000 wmt WoW
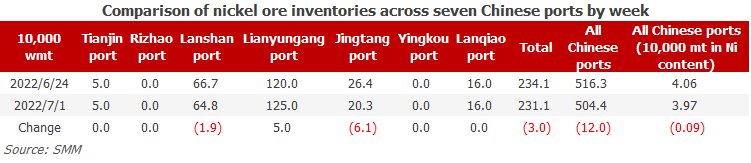
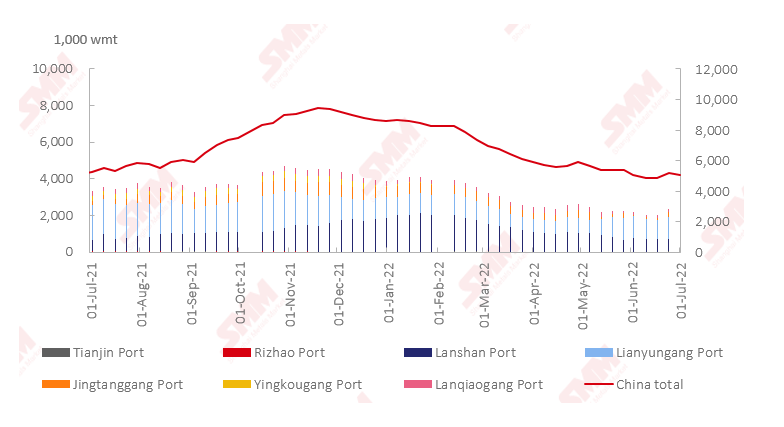
As of July 1, port inventories of nickel ore in China dropped by 120,000 wmt to 5.044 million wmt compared with last week. The total Ni content fell by 1,000 mt to 39,700 mt. The increase in port inventory remained unstable and rangebound at low levels, and the nickel ore supply was relatively tight. The port inventory of nickel ore across seven major Chinese ports stood at 2.311 million wmt, 30,000 wmt lower than the previous week. The supply in the Philippines gradually becomes sufficient, but the sluggish downstream market cannot boost nickel ore imports. The decrease in inventory is probably contributed by the pick-up of goods of NPI plants. SMM expects that the short-term port inventory of nickel ore may remain at low levels. The tight supply cannot change, and the increase in inventory will be unstable in the short term.