SHANGHAI, Mar 18 (SMM) - This is a roundup of China's metals weekly inventory as of March 18.
China Aluminium Ingot Inventory Dropped 53,000 mt on Week
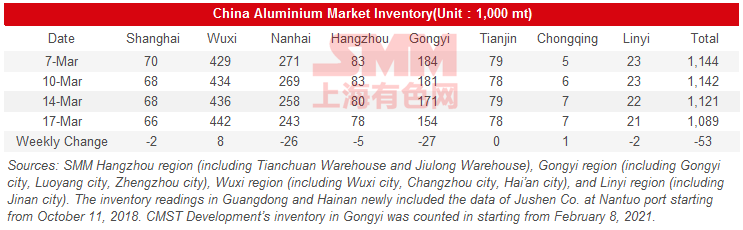
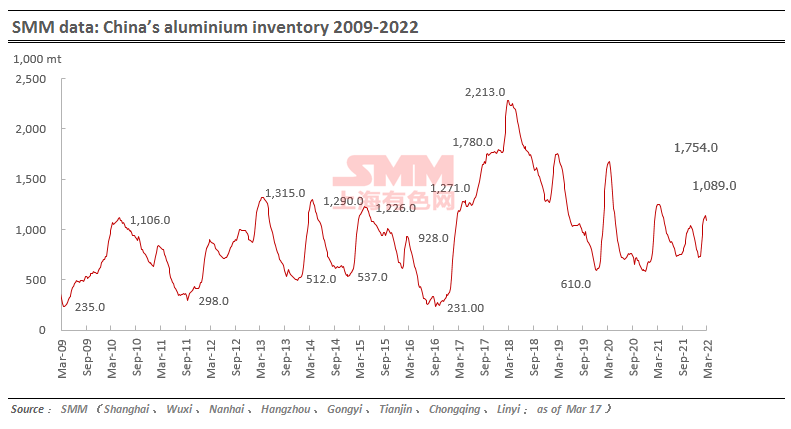
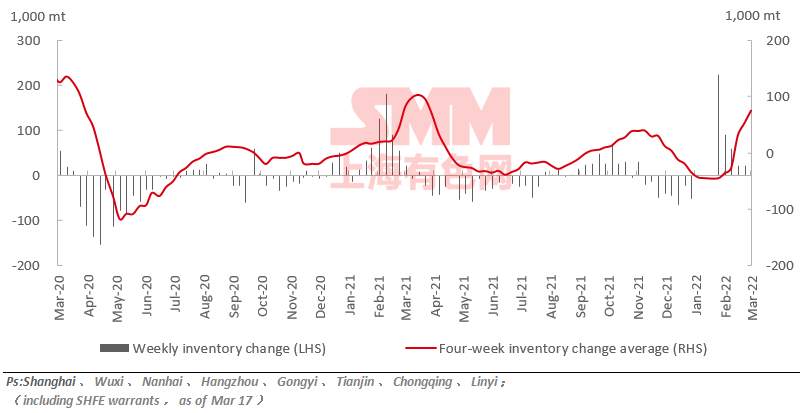
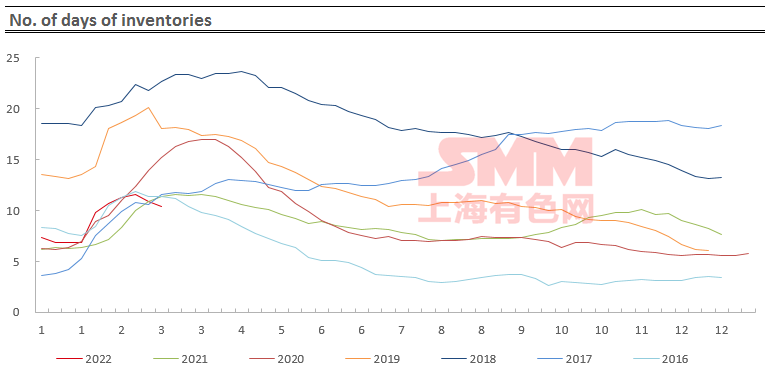
As of March 17, SMM data showed that the domestic aluminium ingot social inventory totalled 1.09 million mt, down 53,000 mt from a week ago. The local inventory across five regions in China all recorded a weekly decline.
Specifically speaking, the inventory in Gongyi and Nanhai dropped the most by 27,000 mt and 26,000 mt respectively. That in Shanghai and Linyi fell 2,000 mt each. Tianjin was flat. Wuxi, on the other hand, saw a weekly gain of 8,000 mt due to disturbed logistics.
In the spot market, the goods holders actively made shipments amid falling futures prices, while the downstream demand also picked up, reviving the tractions of aluminium ingot.
It is expected the aluminium ingot social inventory will drop further, and the market shall watch if the resurging COVID would affect market arrivals and shipments.
Aluminium Billet Inventory Dropped 18,400 mt on Week
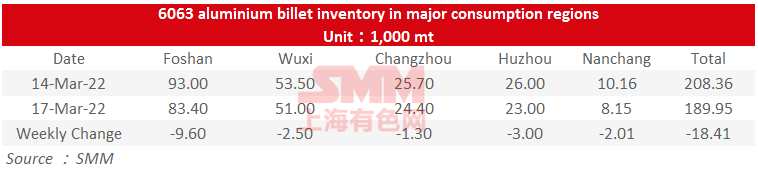
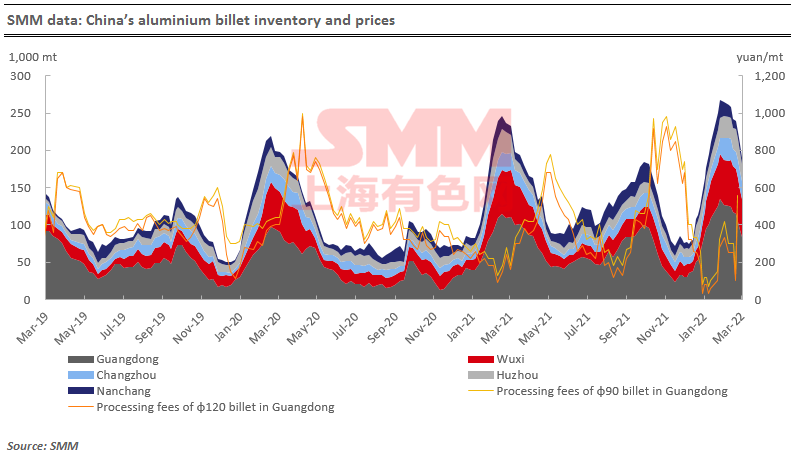
China aluminium billet inventory dropped 18,400 mt to 190,000 mt from last Thursday, down 8.84% on a weekly basis, according to SMM.
Specifically speaking, the inventory dropped 9,600 mt or 10.32% in Foshan, fell 2,500 mt or 4.67% in Wuxi, declined 1,300 mt or 5.06% in Changzhou, shrank 3,000 mt or 11.54% in Huzhou, and reduced 2,000 mt or 19.78% in Nanchang. Aluminium billet inventory kept falling as downstream purchased on demand.
The inventory in Foshan dropped quickly in the past week due to fewer arrivals. Looking forward into next week, the market shall closely watch the logistics which might have been or will be affected by the pandemic control, slowing the decline of aluminium billet inventory.
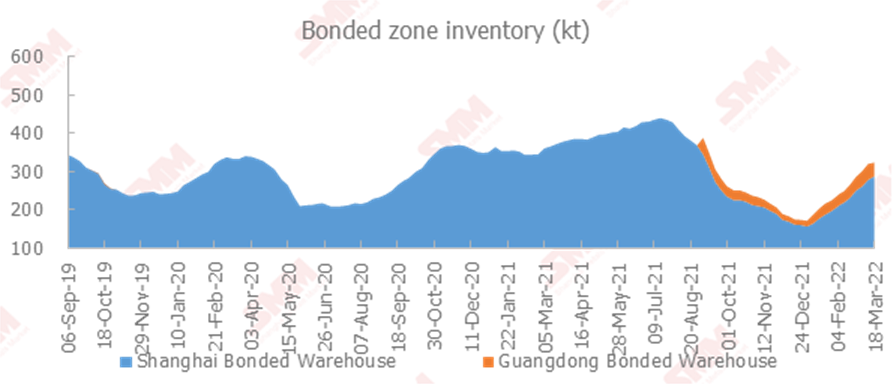
Copper Inventory in Domestic Bonded Zone Up 7,800 mt
Copper inventories in the domestic bonded zones increased 7,800 mt from March 11 to 331,400 mt as of Friday March 18, according to the most recent SMM survey. Inventory in the Shanghai bonded zone increased 5,800 mt to 293,500 mt, and inventory in the Guangdong bonded zone increased 2,000 mt to 37,900 mt. The SHFE/LME price ratio deteriorated again this week, and the import losses over 2204 contract expanded to about 1,400 yuan/mt. With the import window closed, the demand for customs declaration in the market was sluggish, and transaction in the import market was limited. Goods at ports flowed into the bonded zone continuously, so the bonded zone inventory continued to rise.
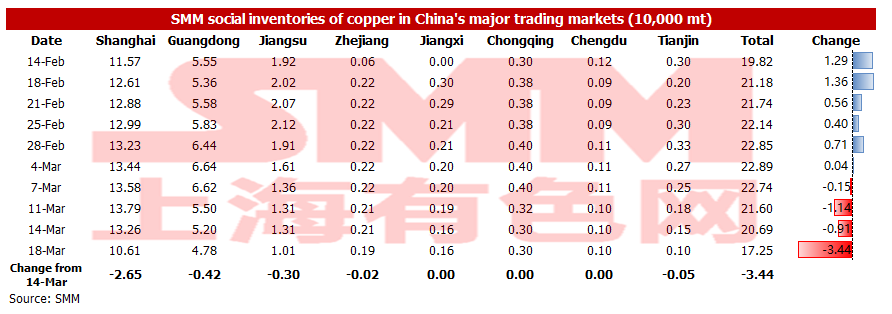
Copper Inventory in Major Chinese Markets Decreased 34,400 mt from Monday
As of Friday March 18, SMM copper inventory across major Chinese markets decreased 34,400 mt from Monday to 172,500 mt, up 73,800 mt from the pre-CNY holiday level of 98,700 mt and down 43,500 mt from last Friday March 11. Destocking this week was faster than that in last week, which showed that the turning point of domestic inventory has appeared. Compared with Monday's data, inventories across China decreased. In detail, the inventories in Shanghai decreased 26,500 mt to 106,100 mt, the inventories in Guangdong dropped 4,200 mt to 47,800 mt, the inventory in Jiangsu fell 3,000 mt to 10,100 mt, the inventory in Zhejiang dipped 200 mt to 1,900 mt, and the inventory in Tianjin dropped 500 mt to 1,000 mt. There were several reasons that led to the decrease of inventory this week: 1. Affected by the COVID-19, the delivery efficiency in some smelters was reduced; 2. There was not much imported copper; 3. The logistics cost was high, but the long-distance transportation freight would not increase, so the driver dawdled over work; 4. The factory could only pick up goods from the surrounding inventories because the long-distance transportation was reduced. What’s more, the downstream consumption was weakened by the COVID-19 to some extent. In general, the supply is weaker than the demand at present. Looking forward, SMM expects that the above situation will hardly improve significantly next week, and the inventory will continue to decline.
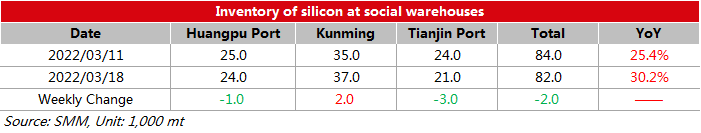
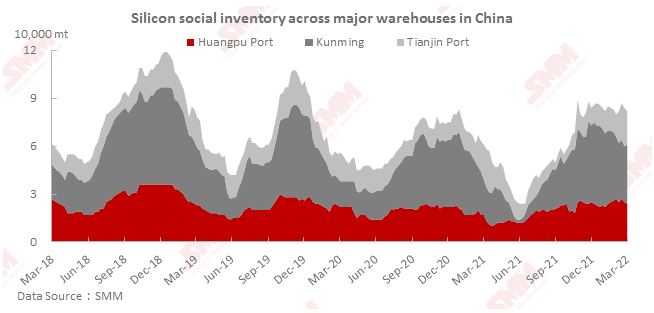
Silicon Metal Social Inventory Decreased by 2,000 mt on Week
The social inventory of silicon metal across Huangpu port, Kunming city and Tianjin port decreased by 2,000 mt from the previous week to 82,000 mt as of Friday March 18.
The port inventories dropped significantly due to the intensive deliveries, while the inventory in Kunming increased slightly as the traders picked up fewer goods amid high freight. The social inventory is expected to rise further this week amid reduced transactions and impeded logistics.
Zinc Inventory Dropped 9,000 mt on Week
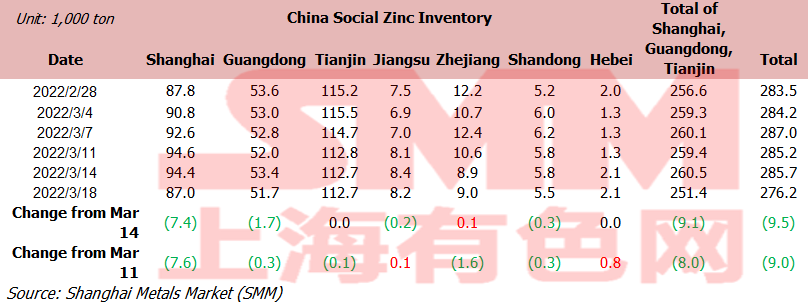
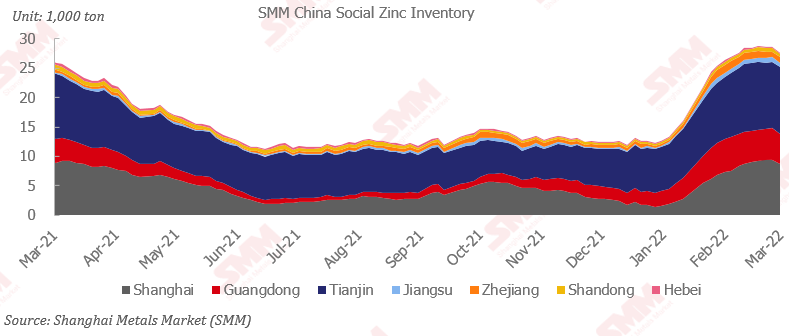
Total zinc inventories across seven markets stood at 276,200 mt as of Friday March 18, down 9,000 mt from March 11, down 9,500 mt from March 14. Domestic inventory reduced. Overall, transport was hampered due to the pandemic. Among them, the arrivals of Shanghai market relatively reduced. Downstream transactions were improved while the zinc prices were at low and inventory reduced. Arrivals also reduced in Guangdong market, coupled with consumption, the overall inventory decreased. In the case of restricted arrivals in Tianjin market, consumption was not improved, but inventory declined slightly. Inventories in Shanghai, Guangdong and Tianjin dropped 8,000 mt, and inventories across seven markets decreased 9,000 mt.