

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
[SMM Analysis] September 2026 Global Crude Steel Market Review: European Supply Squeeze Overshadows Headline Swings
Global crude steel fell 0.2% YoY to 142.4 Mt in September 2026. Overseas output slipped 0.5% (first drop since April), while China edged up +0.1%. Despite base-effect noise, the true shift is shrinking European supply from a German BF outage and ADI's idling. Meanwhile, Q4 quotas exhausted instantly on Oct 1 under new melt-and-pour rules, and Turkish scrap hit 435 USD/tonne.
Oct 30, 2026 13:28 (GMT+8)
DRC: KPM Launches Africa's Largest Renewable Mine Power System
On the southern edge of the DRC's copper belt, there is a question every operator learns to live with: not how much ore is in the ground, but how much electricity will arrive today. Kaipeng Mining (KPM) has answered it in an unusual way — by building a grid of its own. On October 7, the company commissioned Phase II of its new energy power system. Comprising 440 MWp of solar capacity and 300 MW/900 MWh of grid-forming energy storage, it is the largest mine-dedicated renewable power system currently in operation anywhere in Africa's mining regions. The idea is as simple as it sounds: if any one line fails, the power simply flows around it. Technically, Phase II pioneered the "unit–station–cluster" coordinated control strategy, completed full-scenario real-time digital simulator (RTDS) validation, and passed unplanned off-grid tests under all operating conditions, ultimately achieving seamless switching between grid-connected and islanded modes together with prolonged stable islanded operation. When operating at full load, the renewable power it generates can meet the power demand for its metallurgical operations, with annual clean power supply of up to 750 GWh, KPM says. That is roughly 240,000 tonnes of standard coal equivalent saved each year. Why a mine would build a power company None of this exists for its own sake. Mining along the Katanga copper-cobalt belt has long run up against a triple constraint, with each component raising costs for the next. The first is the public grid. The DRC's power supply is heavily dependent on hydropower, while installed capacity and transmission capability have lagged far behind the needs of its mining regions. According to public disclosure by Ivanhoe Mines, Kamoa-Kakula — among the region's best-positioned copper mines — assessed measures including cross-border transmission upgrades from Zambia and battery storage after grid stability disturbances affected its operations from late 2022. For most mines here, an unstable grid is not an emergency. It is a line item in every production plan. The second is the weather. The country's hydro resources are concentrated at the Inga Falls complex, more than 1,000 kilometres from the mining belt. Ageing generators at Inga I and II, deferred maintenance and the long-stalled Inga III expansion have kept actual output well below nameplate capacity; when the dry season arrives, a power shortfall follows. The third is geography. The DRC is nearly landlocked, with only a narrow coastal strip along the Atlantic Ocean: Its mining belt hauls diesel and sulphur thousands of kilometres overland from distant seaports such as Dar es Salaam and Durban. Sulphuric acid is an even tighter bottleneck: every tonne of cathode copper produced through SX-EW process requires 3.5 to 4.5 tonnes of acid, and around 90% of the region's imported sulphur moves through Middle East shipping routes. In the first half of 2026, amid geopolitical tensions and changes in export policy, acid prices in the mining region spiked to $1,000–1,400 per tonne at one point, and chemical delivery times stretched from about three months to between four and six months, forcing a number of producers to cut output when input supplies ran short. Fourth, the need for green smelting and production. Beyond the external factors mentioned above, large-scale adoption of green power also aims to advance green manufacturing and reduce carbon emissions in copper production. Today, the competitive logic of DRC mining has been completely rewritten: the contest is no longer only about mineral rights and ore grades, but about who holds a stable supply of power and acid — and who, as a result, holds the better position on the cost curve. From backup power to the main source KPM's mine-dedicated green microgrid was not built alone. KPM leads investment and operations while Chinese power-control specialist NR Electric is responsible for technical planning and the supply of core grid-forming energy storage and dispatch equipment. Phase I — described by KPM as the first large-scale renewable power system built for mine operating conditions in the DRC — achieved full-capacity grid connection on schedule and met its reliability targets, despite constrained cross-border logistics and underdeveloped local infrastructure. Phase II followed within the same year, and the upgrade changed the system's role rather than merely its size: voltage levels were raised, the solar-storage-diesel ratio re-optimised, and grid-forming storage expanded to 300 MW/900 MWh. A supplementary source became the mine's primary one — no longer a helper to the weak public grid, but the load-bearing source underneath the entire mining and metallurgical operations. The hard part is invisible. Coordinating wide-area, multi-node grid-forming storage clusters is a recognised control problem across the industry. For Phase II, the project team applied a hierarchical "unit–station–cluster" control strategy, which the developer says reduces the coupling between node count and control complexity from exponential to linear. Before commissioning, the system passed full-scenario real-time digital simulator (RTDS) validation and unplanned off-grid tests under all operating conditions. KPM adds that its solution has since been used as a technical reference in the renewable-integration plans of more than 30 miners. The loop that closes on site The power system is one leg of a larger design. This year, KPM brought three flagship projects on stream: the solar-storage system, an oxidative roasting-leaching line that recovers value from refractory mixed copper and cobalt ores while producing sulphuric acid as a by-product, and a dedicated sulphur-burning acid plant that secures on-site acid supply for hydrometallurgy. Each one covers a constraint the others expose — power for high-load roasting and electrowinning, acid for leaching, processing capacity for the mine's complex ores. The economics, ultimately, are what carry the case. The solar-storage architecture covers round-the-clock demand; the closed loop of power, roasting, acid and hydrometallurgy keeps production stable when external markets are not. As the EU’s Carbon Border Adjustment Mechanism (CBAM) is phased in, KPM notes, green-powered metallurgy puts the operation in a stronger position to manage the associated cost — one that competitors are only just starting to price in. Competition in global mining has long since shifted from "who secured the ore" to "who can turn ore into product at lower overall cost and with a more stable supply chain." Under the Congolese sun, 440 MW of solar panels now tilt toward the answer. The diesel units still stand at the edge of the plant, silent until called. For one mine on the copper belt, the question of "how much electricity will arrive today" has, at last, a different answer: as much as it needs. Note to editors: Installed capacity, generation, price and operating-performance figures in this article are provided by KPM and have not been independently verified; ramp-up performance and actual operating parameters remain subject to observation. Background on DRC power, sulphur and sulphuric acid markets draws on public reporting by Caixin, Reuters and industry research firms. Click to watch the video:》Kaipeng Mining: Rooted in Resources, Empowered by Green Power, Building Integrated Industrial Operations Content contributed by Kaipeng Mining (KPM).
Oct 30, 2026 10:00 (GMT+8)
Solid-State Batteries Await Mass Production, Gotion Positions Itself as a First-Mover
Gotion’s current solid-state layout puts materials, cells and customer validation on almost the same timetable. Near term, watch whether the 300-ton lithium sulfide pilot line in Anqing can produce reliable scale-up data and whether cost can fall from RMB 1.3 million/t toward RMB 500,000/t; G-Yuan’s 12 GWh capacity has been built, but actual deliveries will follow customer on-vehicle testing; the Jinshi 2 GWh line has not yet started formal GWh-level equipment tendering
Oct 29, 2026 15:35 (GMT+8)
Latest News
Tianjin Zinc: Futures Pull Back, Downstream Restocking on Rigid Demand [SMM Midday Commentary]
2 mins ago
Futures pullback combined with persistently tightening available supply, Shanghai spot copper premiums hit a new high for the year [SMM Shanghai spot copper]
5 mins ago
[SMM Computing Power News] Two H100 units in east China quoted at 92,000, hitting a new high for this model
15 mins ago
[SMM Computing Power News] 38 Turbo 5090 units in South China quoted at 48,000, continuing downward
SMM learned that 38 RTX 5090 turbo cards in South China are being offered for sale at 48,000 yuan per card, with the seller indicating that prices for this batch continue to decline. Turbo cards are used in both servers and workstations. The tax status of this lot was not specified: if calculated on a tax-exclusive basis, the price is 500 yuan lower than the 48,500 yuan derived from the tax-inclusive price of 54,800 yuan for turbo cards in the same region on October 28, continuing the downward trend since October 21; if calculated on a tax-inclusive basis, it is 6,800 yuan lower than 54,800 yuan, a decline of 12.4%. During the same period, fan cards and ROG editions were both quoted at 53,000 yuan tax-inclusive.
For details, contact SMM Cao Zheng at 021-51595793.
15 mins ago
[SMM Computing Power News] The annual rental price of an H100 8-GPU server is about 100,000 yuan/month.
SMM learned that on November 4, a cloud service channel reported an annual rental quote of approximately 100,000 yuan/month for an 8-card NVIDIA H100 80GB HBM3 server, with similar resources priced at around 92,000 yuan/month this week. The resource is offered on an annual rental basis, not a long-term lease, and is configured with two Intel Xeon Platinum 8468 processors and 2048GB of DDR5 memory. It is understood that the current resource is being sold externally after multiple layers of subcontracting.
[For details, contact: SMM AI Computing Power Analyst Li Siming 021-51666774]
19 mins ago
[SMM Computing Power Midday Review] H100 Falls Below 90,000 for the First Time, 5090 Turbo Continues to Decline
Of the 19 indices today, 18 remained unchanged. The highest monthly rental for the H100 in the Yangtze River Delta rose from 87,000 yuan to 92,000 yuan (up 5.7%), with the highest per-card hourly rate at 15.97 yuan, breaking the 90,000-yuan mark for the first time and matching the 92,000-yuan quote for two spot units in east China, while the lowest price of 78,000 yuan held steady. In south China, 38 RTX 5090 turbo cards were quoted at 48,000 yuan, with the tax-exclusive price down another 500 yuan from October 28 and the tax-inclusive price 12.4% lower, while fan-cooled and ROG models remained at 53,000 yuan.
20 mins ago
[SMM ESS Flash] LG Energy Solution Targets Over 70 GWh of Storage Cell Capacity by 2027
LG Energy Solution said at its third-quarter earnings call on 3 November that it expects pouch energy storage system capacity to exceed 50 GWh by the end of 2026 and rise above 70 GWh in 2027, converting some electric-vehicle lines to storage use and adding prismatic storage lines, as it chases North American demand driven by AI data centres. Third-quarter storage cell shipments rose more than 60% quarter on quarter with storage revenue above 30% of the total, the order backlog reached 160 GWh, and fourth-quarter storage shipments are guided up about 40% quarter on quarter. The company plans to mass-produce LFP 2170 cylindrical cells in the first half of 2027 and is accelerating sodium-ion development, with samples due at its Ochang plant by year-end and test deliveries to North American customers in 2027. LG Energy Solution posted third-quarter revenue of KRW 9.6 trillion and operating profit of KRW 756 billion with a net loss of KRW 296.9 billion including minority interests, and is diversifying cathode, anode and electrolyte suppliers to meet US restrictions related to prohibited foreign entities.
20 mins ago
[SMM PV Flash] New Zealand's Lightyears Secures NZ$174 Million in Investment and Debt
New Zealand renewable energy company Lightyears Group announced on 3 November a combined NZ$174 million (about US$102 million) of investment and debt support, with Japan's Obayashi Corporation planning to invest NZ$74 million for a 90% stake in new project-holding company LYOC1 Limited through milestone-based contributions and Australian infrastructure debt investor InfraDebt providing a NZ$100 million loan facility. The funding will support more than 300 MW of utility-scale solar and battery storage projects that Lightyears plans to advance over the next five years. The package builds on the Obayashi-Lightyears strategic partnership, and marks InfraDebt's first New Zealand transaction after the two parties began working together in 2025. Lightyears' 14 MW Reefton solar plant on the West Coast is nearing completion, its 15 MW Te Aho o te Rā plant developed with eight Maori land trusts is scheduled for completion in July 2027, and a 6 MW plant is under construction at Ashburton.
20 mins ago
[SMM PV Flash] Australia's Waroona Solar-Storage Project Signs A$280 Million Syndicated Facility
Australia's Frontier Energy, through subsidiary WRP Finance, announced on 2 November that it has signed a syndicated facility agreement of up to A$280 million with an international group led by Natixis CIB and Sumitomo Mitsui Banking Corporation to fund Phase 1 of the Waroona renewable energy project in Western Australia, moving the project closer to financial close. Phase 1 comprises a 132 MW solar farm and an 81.5 MW/562 MWh battery energy storage system, with the facility split into up to A$250 million of construction and term loans, up to A$17 million of debt service reserve and up to A$13 million of guarantee facilities, structured as secured, non-recourse project finance with a nominal 18-year repayment profile. Financial close is expected in November 2026, subject to executing a Capacity Investment Scheme agreement with the federal government and completing interest-rate hedging, with first drawdown planned for the first quarter of 2027. Combined with an A$110 million equity placement completed in July, the debt and equity are expected to cover the full Phase 1 construction cost, and the project targets first power in 2028.
21 mins ago
Aluminum prices edged down today, allowing spot aluminum to stabilize [SMM South China Spot Aluminum Daily Review]
22 mins ago
[SMM PV Flash] Thailand Readies Phase-One Budget for Million-Rooftop Solar Scheme
24 mins ago

Auto Trade Surges: $33.44B in Sept, Up 34.3% YoY, Driven by Strong Exports
35 mins ago
China's NEV Wholesale Sales Reach 1.8M in Oct, Up 12% YoY and 8% MoM
35 mins ago
Guangdong Announces Plan to Boost Intelligent Connected Vehicle Development and L3 Autonomous Testing
On November 3, the Guangdong Provincial Development and Reform Commission issued the Implementation Plan for Expanding Consumption in Guangdong Province. The plan proposes increased support for the development of intelligent connected vehicles, encourages whole-vehicle enterprises to pursue L3 autonomous driving car model access and road pilot programs in accordance with regulations, and promotes orderly intelligent driving testing and commercial operations in the Greater Bay Area.
35 mins ago
PBOC Governor: Ensure Stability in Stock, Bond, and Forex Markets
PBOC Governor Pan Gongsheng: Maintain stable operations of financial markets including stocks, bonds, and foreign exchange.
36 mins ago
【SMM Aluminum Flash News】Chinese Investors Eye Aluminum Plant and Green Energy Development in Malaysia's Sarawak
Chinese investors are exploring plans to establish an aluminum production facility alongside green energy infrastructure in Samalaju, Bintulu, Sarawak, Malaysia, with the energy facilities intended to supply electricity for manufacturing operations. Malaysian Deputy Prime Minister Ahmad Zahid Hamidi confirmed on November 2 that discussions had taken place with the Sarawak state government, with the proposed project targeting international markets.
The investment plan combines aluminum manufacturing with green energy development, although the project's investment value, production capacity, construction timeline and energy technologies have not yet been disclosed. Meanwhile, a Chinese business delegation has indicated potential investments totaling approximately $15 billion in Malaysia, covering high-tech and value-added industries. The figure represents broader investment interest rather than funding specifically allocated to the proposed aluminum project.
48 mins ago
Copper Prices Decline, Downstream Actively Restocks, Stimulating Premiums to Hit Record Highs [SMM South China Spot Copper]
49 mins ago
【SMM Aluminum Flash News】Canada's PrimeAlux Expands US Market Through Distribution Partnership with Shapes Unlimited
Canadian aluminum fencing supplier PrimeAlux has appointed Shapes Unlimited as its authorized US distributor, expanding access to its aluminum building products across the American market. The Ohio-based company will manage local pricing, orders and customer support for US contractors, dealers and builders.
The partnership covers aluminum privacy and semi-privacy fence panels, gates and privacy screens, with products supported by independent fire and acoustic performance testing. By establishing a domestic distribution channel, PrimeAlux aims to expand its US market presence and improve procurement accessibility for aluminum fencing and architectural products.
49 mins ago
【SMM Aluminum Flash News】Tesla Advances Aluminum Applications in EV Powertrains
Tesla plans to introduce Cybercab-derived inverter technology into Model 3 production in 2026, featuring fewer electronic components and greater supplier flexibility to simplify manufacturing and reduce costs. The Cybercab powertrain also incorporates an aluminum motor housing with integrated cooling channels, although this housing design has not been confirmed for Model 3.
Meanwhile, Tesla's next-generation Roadster is targeting production in 2028, using aluminum battery cell cans and an aluminum underbody protection plate to support thermal management, lightweight construction and structural durability. The vehicle targets a weight below 1,700 kg, with performance-focused battery technology designed for high power output. These developments highlight aluminum's expanding role in EV battery systems, powertrain housings and lightweight automotive engineering.
51 mins ago
SHFE Aluminum Futures Decline, Spot Premiums Weaken as Backwardation Widens to Yearly High
[SMM SHFE Aluminum Spot] SHFE aluminum futures continued to decline, with the nearby-month backwardation structure widening to a yearly high. Since trading began on the SHFE aluminum 2611 contract, spot premiums hit a new yearly high, but under pressure from the wide price spread between futures contracts, premiums gradually weakened, with weekly transactions moving back toward parity. The price spread between futures contracts has widened from a backwardation of 200 yuan/mt to around 350 yuan/mt. As delivery enters the countdown, spot prices against the SHFE aluminum 2611 contract are expected to continue weakening, but caution is needed regarding the guidance of the widening price spread between futures contracts on next-month premiums.
52 mins ago
【SMM Analysis】Vietnam Proposes Aluminium Export Duty Cuts, Implications for Southeast Asian Billet and Extrusion Trade
Vietnam is proposing to cut export duties on selected aluminium products, potentially giving domestic suppliers more room to adjust export offers. According to the Vietnam Chamber of Commerce and Industry (VCCI)'s account of the accompanying government draft, duties on relevant unwrought aluminium (HS7601), aluminium bars, rods and profiles (HS7604), and aluminium wire (HS7605) would fall from 5% to 1%. VCCI has called for a further reduction to 0%. If implemented, the changes could improve export netbacks and commercial terms for Vietnamese billet and extrusion suppliers, affecting competition with Chinese, Malaysian and other regional suppliers. The measures remained proposals at this article's research cut-off on October 30, 2026. No published instrument bringing the proposed 1% or 0% rates into force had been identified. A separate draft resolution published by the Vietnamese authorities would lower the statutory export duty range for products including HS7601 and HS7604 from 5–40% to 0–30%, providing legal scope for the government to reduce specific rates. A 0% floor would not automatically make these products duty-free. Applicable rates, tariff coverage and implementation dates remain subject to the final instruments. For Southeast Asian billet trade, the immediate commercial effect of a duty cut would be on Vietnamese suppliers' export netbacks and pricing options. With the taxable value and other conditions unchanged, lower export duties could increase sellers' net proceeds or support lower offers to secure orders. How suppliers allocate the savings would depend on inventories, available material, order books and bargaining power. The reduction in duty cannot be treated as an equivalent percentage decline in billet prices or processing fees. If Vietnamese suppliers pass part of the savings through to export offers, regional extruders could gain more attractive sourcing options, putting competing offers for comparable billet from China, Malaysia and other origins under pressure. Sustained trade growth would still depend on the specifications, delivery schedules and customer acceptance of Vietnamese export material. HS7601 covers a broad range of unwrought aluminium and cannot be treated entirely as 6063 billet. Billet made from primary aluminium and remelt billet also need to be assessed separately for alloy composition, impurity control, homogenisation and processing performance. A tax change alone does not demonstrate an increase in substitutable supply. For Vietnamese extruders, lower duties on covered HS7604 products would directly increase flexibility in export offers. Suppliers could retain more earnings at existing prices or offer concessions to compete for regional orders. Export duty, however, is only one element of a buyer's procurement cost. Comparisons with Chinese, Malaysian and other supplies must also account for specifications, surface treatment, certification, freight, delivery times, destination import duties and rules of origin. HS7604 coverage should not be extended to all finished aluminium products. Any benefit for doors, windows or structural components classified under other headings would depend on the final scope. Simultaneous duty cuts for billet and profiles could also change sales decisions within Vietnam's aluminium supply chain. Better export netbacks for unwrought aluminium alloy could prompt billet casters to reassess the returns from exports against domestic sales. Where available material is limited, more attractive export opportunities could intensify competition for feedstock among domestic extruders. If suppliers can expand output of billet that meets customer requirements, they may instead be able to serve both domestic processors and export markets. Lower duties on extrusion exports therefore would not necessarily reduce domestic billet procurement costs. The eventual benefit would depend on supply and demand along the chain and on contract pricing. Another trade channel to watch is the sale of aluminium products by Vietnamese domestic suppliers to export-processing enterprises and non-tariff zones. Supplies from the domestic market into non-tariff zones can fall within the scope of export duty, while goods brought from overseas into qualifying non-tariff zones and used exclusively within them can fall outside the scope of import duty. VCCI argues that this difference weakens the appeal of domestic aluminium supplies and has requested an explicit 0% export duty rate for domestically produced aluminium sold to export-processing enterprises and non-tariff zones for production use. If adopted, that recommendation could narrow the tax disadvantage faced by Vietnamese suppliers serving these customers, giving domestic billet and profiles more scope to compete for procurement contracts. For orders previously supplied from overseas, competition would increasingly depend on delivery reliability, quality and total delivered cost. The treatment would remain conditional: it should not be extended to all aluminium imports or interpreted as a blanket tax cut on ordinary domestic sales. Enterprise and zone eligibility, use within the zone and customs supervision requirements would still need to be met. At this stage, the proposals create potential for Vietnamese suppliers to adjust offers and sales channels. They do not establish that Southeast Asian billet prices have already fallen as a result, or that extrusion orders have shifted. The market impact will depend primarily on the final rates and implementation arrangements, changes in Vietnamese suppliers' actual offers and delivery schedules, and any shifts in regional buyers' sourcing. If duty cuts are implemented and translate into reliable supplies that meet customer requirements, Vietnam could strengthen its competitive position in Southeast Asian billet and extrusion trade.
Oct 30, 2026 12:05 (GMT+8)
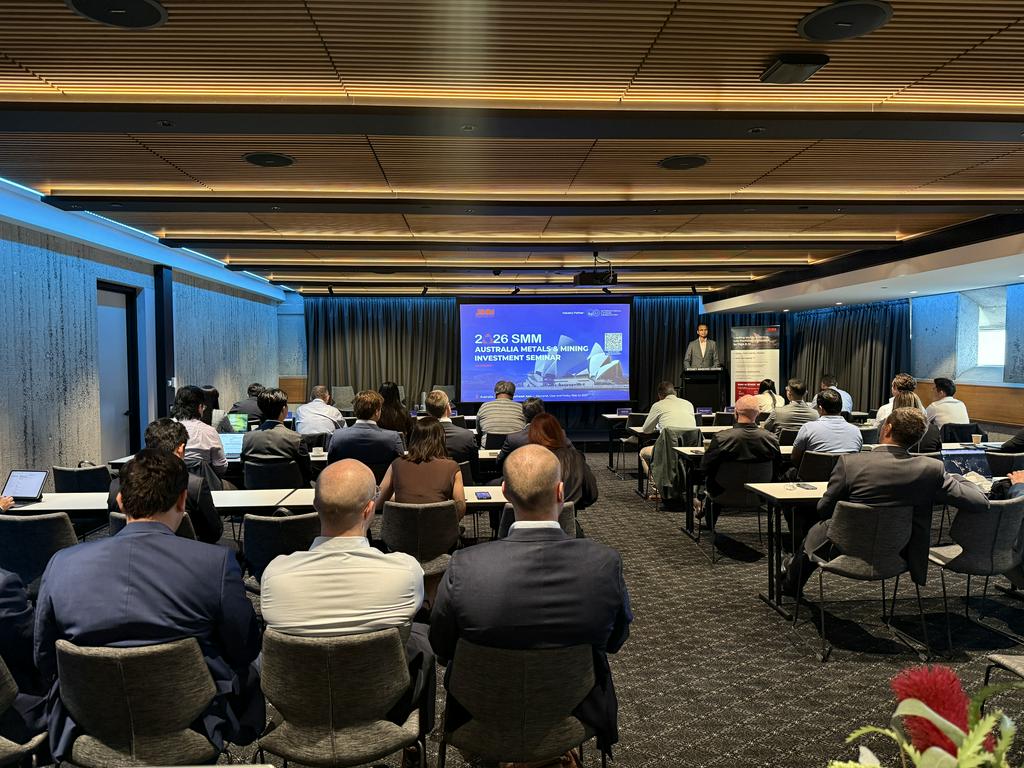
Takeaways from 2026 SMM Australia Metals & Investment Seminar: Outlook for Ferrous, Nonferrous and Battery Metals
Oct 28, 2026 16:47 (GMT+8)
[SMM Analysis] South America’s Solar Market: Installations, Policy and Key Country Trends
Oct 28, 2026 14:21 (GMT+8)

[SMM Analysis] Thailand's Proposed Scrap Import Ban May Redirect Shipments to India and Other Asian Markets
Oct 28, 2026 02:45 (GMT+8)
[SMM Analysis] September 2026 Global Crude Steel Market Review: European Supply Squeeze Overshadows Headline Swings
Oct 30, 2026 13:28 (GMT+8)
DRC: KPM Launches Africa's Largest Renewable Mine Power System
Oct 30, 2026 10:00 (GMT+8)
Solid-State Batteries Await Mass Production, Gotion Positions Itself as a First-Mover
Oct 29, 2026 15:35 (GMT+8)
Latest News
Tianjin Zinc: Futures Pull Back, Downstream Restocking on Rigid Demand [SMM Midday Commentary]
2 mins ago
Futures pullback combined with persistently tightening available supply, Shanghai spot copper premiums hit a new high for the year [SMM Shanghai spot copper]
5 mins ago
[SMM Computing Power News] Two H100 units in east China quoted at 92,000, hitting a new high for this model
15 mins ago
[SMM Computing Power News] 38 Turbo 5090 units in South China quoted at 48,000, continuing downward
15 mins ago
[SMM Computing Power News] The annual rental price of an H100 8-GPU server is about 100,000 yuan/month.
19 mins ago
[SMM Computing Power Midday Review] H100 Falls Below 90,000 for the First Time, 5090 Turbo Continues to Decline
20 mins ago
[SMM ESS Flash] LG Energy Solution Targets Over 70 GWh of Storage Cell Capacity by 2027
20 mins ago
[SMM PV Flash] New Zealand's Lightyears Secures NZ$174 Million in Investment and Debt
20 mins ago
[SMM PV Flash] Australia's Waroona Solar-Storage Project Signs A$280 Million Syndicated Facility
21 mins ago
Aluminum prices edged down today, allowing spot aluminum to stabilize [SMM South China Spot Aluminum Daily Review]
22 mins ago
[SMM PV Flash] Thailand Readies Phase-One Budget for Million-Rooftop Solar Scheme
24 mins ago
Auto Trade Surges: $33.44B in Sept, Up 34.3% YoY, Driven by Strong Exports
35 mins ago
China's NEV Wholesale Sales Reach 1.8M in Oct, Up 12% YoY and 8% MoM
35 mins ago
Guangdong Announces Plan to Boost Intelligent Connected Vehicle Development and L3 Autonomous Testing
35 mins ago
PBOC Governor: Ensure Stability in Stock, Bond, and Forex Markets
36 mins ago
【SMM Aluminum Flash News】Chinese Investors Eye Aluminum Plant and Green Energy Development in Malaysia's Sarawak
48 mins ago
Copper Prices Decline, Downstream Actively Restocks, Stimulating Premiums to Hit Record Highs [SMM South China Spot Copper]
49 mins ago
【SMM Aluminum Flash News】Canada's PrimeAlux Expands US Market Through Distribution Partnership with Shapes Unlimited
49 mins ago
【SMM Aluminum Flash News】Tesla Advances Aluminum Applications in EV Powertrains
51 mins ago
SHFE Aluminum Futures Decline, Spot Premiums Weaken as Backwardation Widens to Yearly High
52 mins ago