Recently, data from South Korean research institution SNE Research revealed that in 2023, the global (excluding China) sales of electric vehicle batteries amounted to approximately 319.4 GWh, marking a 43.2% increase compared to the same period in 2022.
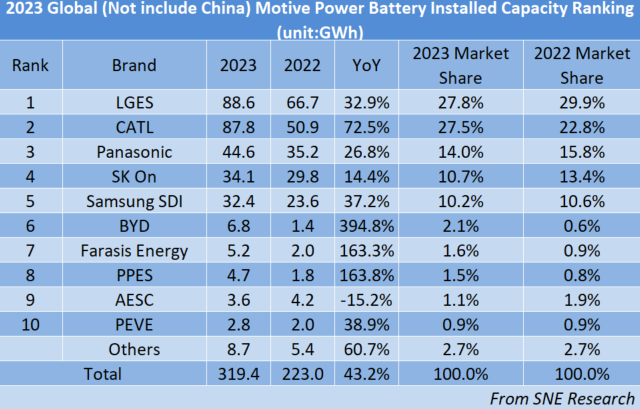
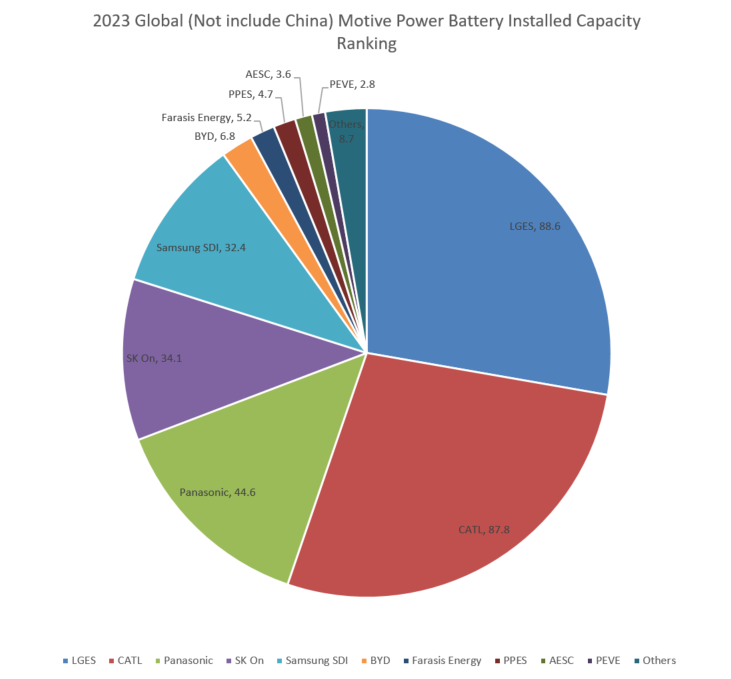 Worth noting is the ranking of electric vehicle battery installations globally (excluding China), with LG Energy Solution (LGES) maintaining the top spot. Compared to the same period in 2022, LGES experienced a growth of 32.9%, achieving an installation volume of 88.6 GWh and a market share of 27.8%.
In the global electric battery market outside of China, CATL follows closely behind LGES, securing the second position with a total installation volume of 87.8 GWh. CATL demonstrated continuous high growth of 72.5%, posing a significant threat to LGES's leading position with a market share of 27.5%.
SNE indicates that Chinese companies, including CATL, are experiencing higher growth rates in the global electric vehicle battery market than in the domestic market, rapidly expanding their global market share. CATL's batteries are installed in vehicles from major manufacturers such as BMW, MG, Mercedes-Benz, and Volvo, including Tesla Model 3/Y manufactured in China for export to Europe, North America, and Asia. Recently, CATL's batteries have been installed in Hyundai's new Kona and Kia Ray electric vehicles, further expanding the influence of Chinese companies in the domestic market.
Panasonic holds the third position in the rankings, with an installation volume of 44.6 GWh, showing a growth rate of 26.8% compared to the same period in 2022. In the global electric battery market (outside China) in 2023, Panasonic achieved a market share of 14%. As one of Tesla's main battery suppliers, Panasonic produces improved 2170 and 4680 batteries, aiming to increase its market share centered around Tesla in the future.
South Korean battery companies SK On and Samsung SDI rank fourth and fifth, with installation volumes of 34.1 GWh and 32.4 GWh, respectively. They experienced growth rates of 14.4% and 37.2% YoY, with market shares of 10.7% and 10.2%, respectively. SNE's analysis suggests that the growth of the three major South Korean battery companies is mainly attributed to strong sales of vehicles equipped with their respective batteries.
Chinese battery supplier BYD holds the sixth position, increasing its market share from 0.6% in 2022 to 2.1% in 2023, with overseas installation volume rising to 6.8 GWh, a remarkable 394.8% YoY increase. BYD is the company with the largest growth among the TOP 10 companies in the global new energy vehicle power battery market (excluding China).
Additionally, Chinese battery company EVE Energy rapidly increased its overseas battery market installations, achieving a growth rate of 163.3%. With an installation volume of 5.2 GWh, EVE Energy secured the seventh position with a market share of 1.6%.
Farasis Energy, with an installation volume of 3.6 GWh, also made it to the TOP 10 in the global market outside China in 2023, ranking ninth with a market share of 1.1%.
Toyota and Panasonic's joint ventures PPES and PEVE rank eighth and tenth, with installation volumes of 4.7 GWh and 2.8 GWh, respectively. Their market shares are 1.5% and 0.9%, with PPES experiencing a significant 163.8% YoY growth and PEVE growing by 38.9% in 2023 in the global electric battery market (outside China).
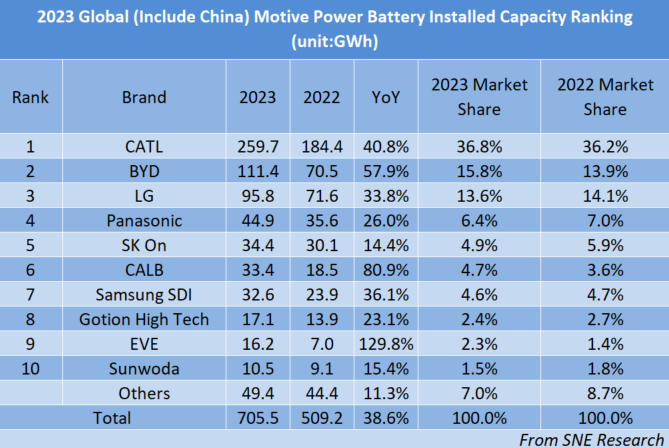
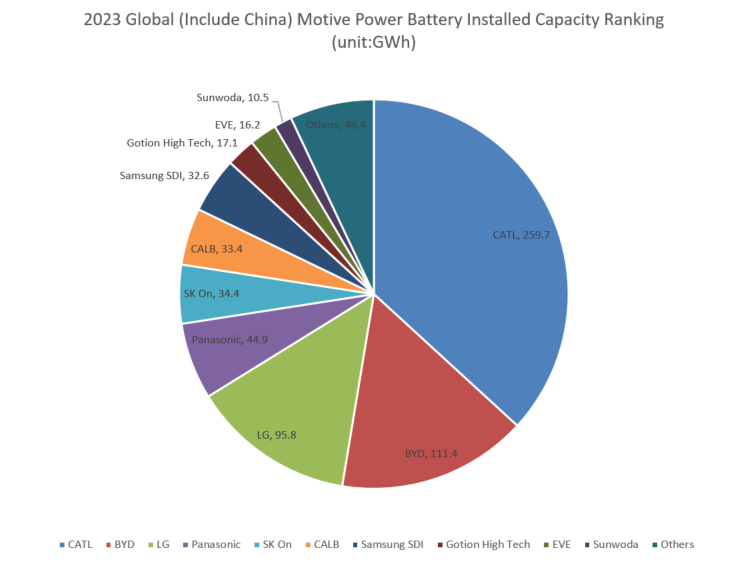
n addition to overseas electric vehicle (EV) battery installation data, SNE recently released the 2023 global (including the Chinese market) new energy vehicle power battery installation data. In 2023, the registered electric vehicle (EV, PHEV, HEV) battery installations worldwide reached approximately 705.5 GWh, a YoY increase of 38.6%. Examining the TOP 10 global power battery installers, Chinese companies secured 6 positions, with a market share of 63.5%, up from 59.6% in 2022. CATL and BYD combined still account for over half, reaching 52.6% market share.
SNE analysis indicates a significant slowdown in the growth rate of the global electric vehicle market in 2023, impacting the downstream secondary battery industry. Factors such as early adopters completing initial purchase demands, economic contraction due to high interest rates and prices, and a lack of charging infrastructure are identified as reasons slowing electric vehicle market demand growth. Although the slowdown in the electric vehicle market is expected to persist for some time, SNE anticipates that regulatory enforcement of IRA subsidies will strengthen from 2024, the number of models eligible for tax credits will decrease, and the maintenance of tax credits will depend on the results of the U.S. presidential election. Uncertainties have negatively impacted the demand for electric vehicles.
SNE believes that the electric vehicle market will shift towards a price-centric approach this year, intensifying competition among automakers to survive through price reductions. Attention is expected to be focused on battery technology development, competition, and strategies to stabilize the critical mineral supply chain.
If you have any questions regarding the industry data, or the news (e.g. how this can affect your business). Please feel free to reach out to me:
Robin He
SMM Li-ion Battery Materials Department
E: robinhe@smm.cn | T: +86-21-51595884