

The booming EV and energy storage system markets have driven strong demand growth of lithium salt, which attracted lots of investment. However rapid development in the lithium salt market has brought huge volatility of prices. Most recently, changes on lithium carbon futures prices at Guangzhou Futures Exchange(GFEX) also attracted market attention.
Contradiction between lithium carbonate quality diversity and futures market standard
Futures contracts outline minimum physical and chemical specifications for the underlying commodity so that each lot of material is standardised – this is a crucial parameter for consistent price discovery. As high-tech products Lithium-ion batteries have harsh and high-standard requirements on raw materials. However, as a chemical product, lithium carbonate qualities vary among producers. How to reasonably price them with different qualities based on the prices from the futures market is hard, which also incur many issues in the market. Firstly, high-quality battery grade lithium carbon producers have less interest in delivering their products to approved warehouses, because they can enjoy some premium from the spot market. Secondly, lithium carbonate from some producers cannot meet the battery grade standard of GFEX, which make some products cannot be traded in the futures market. Thirdly, downstream customers have specific requirements for lithium salt based on the characteristics of their products. Customized raw materials are popular in the lithium-ion battery industry, which reduce the possibility of consumers to source their lithium carbonate through physical delivery from the futures market. Thus the above factors contributed to a potential short squeeze in the current GFEX.
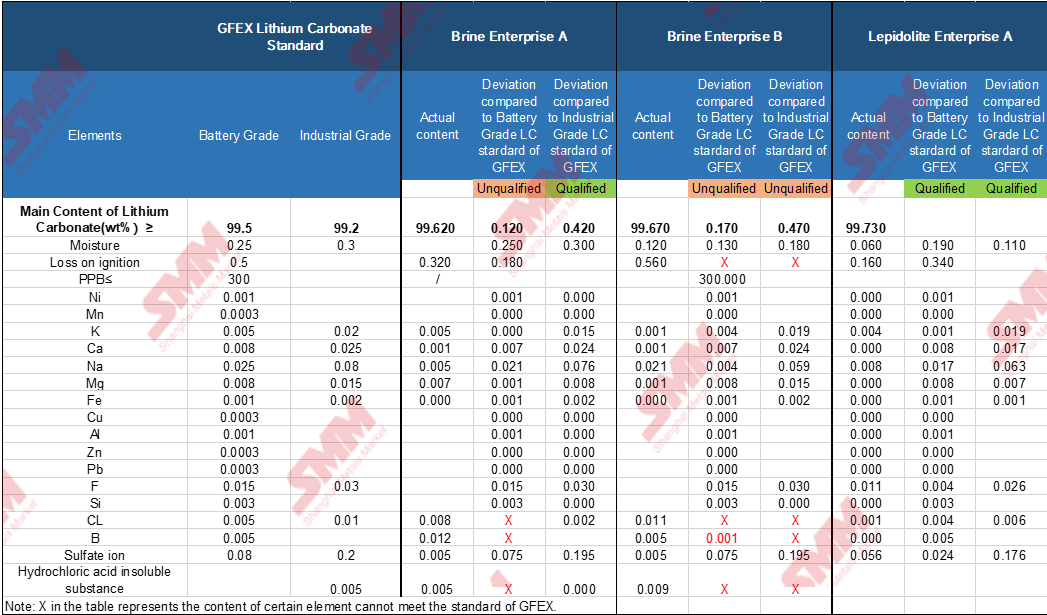
According to SMM survey on the quality inspection of lithium carbonate from most of producers in the market, we found battery-grade lithium carbonate producers adopting spodumene and lepidolite as raw materials are easier to meet the delivery standards that is draw up by GFEX, as shown in the following figure.
Fig 1:Comparison of GFEX standard and actual qualities from lithium carbonate producers
Data: SMM, GFEX
Complexity has a great impact on the market participants
From a producer’s perspective, high-quality lithium carbonate producers would not like to accept the same futures price with other producers. Other producers that can meet the delivery standard pay more attention on the futures market prices. Once the prices are good enough, they could implement hedging activities in the futures market. According to the lithium carbonate contracts rules of GFEX, the alternative delivery product (industrial grade lithium carbonate) that meet certain standard have a discount of 25,000yuan/t compared to the standard lithium carbonate. This fixed discount could reduce the willingness of some industrial grade lithium carbonate producers to trade their products in the futures markets, especially when lithium carbonate prices remain low.
On the other hand, lithium-ion batteries downstream consumers, OEMs, ESS producers and others, have strict requirements for battery performance. Therefore, battery manufacturers have strict certification requirements for raw materials when collaborating with suppliers of materials such as cathodes. Qualified suppliers must undergo rigorous certification before entering the supply chain, with a certification period of 1-2 years on average. For example, most battery manufacturers have consistent requirements on the lithium content and impurity content of lithium carbonate from different suppliers, which can secure the stability of lithium-ion battery quality. Consequently, most cathode material factories and battery manufacturers only work with certified lithium salt suppliers to avoid quality risks incurred from raw materials. It is less likely for consumers of lithium carbonate to source their raw materials through the physical delivery in the futures market under the current futures contracts.
In the current market, traders normally have long-term supply agreements with downstream customers, and only a small amount is sold on a spot basis. Some new trading companies with limited quantities and multiple brands of lithium carbonate sources, they may encounter situations where they have to significantly reduce prices but still have difficulty in selling, mainly because they cannot meet the requirements on raw materials from the cathode factories.
Expanding warehouses storage capacity could raise the limit for absorbing oversupply
On December 11th, GFEX announced it has approved the application from relevant delivery warehouses to increase the minimum guaranteed storage capacity from 30,000 tons to 60,000 tons. This includes GFEX-approved lithium carbonate factory warehouses, bringing the overall minimum guaranteed storage capacity to 63,150 tons.
Based on the Rules of Guangzhou Futures Exchange on Lithium Carbonate Futures and Options, Lithium carbonate with a production date within 60 days (inclusive) from the delivery date are eligible for registration as standard deliverable, while alternative deliverable with a production date within 240 days (inclusive) from the delivery date are also eligible for registration.
A part of additional output from new lithium carbonate capacity could be delivered to the GFEX-approved warehouses, as the market remain oversupply. Appearance of originally invisible inventory might accelerate oversupply correction by potential curtailments that are forced by great loss.
Unlike traditional commodities in the futures markets, pricing of lithium salt, including lithium carbonate is very complicated, which has driven strong competition among price reporting agencies that focus on raw materials of lithium-ion battery. SMM has made great efforts to help the market participants to get better understanding of pricing mechanisms and support the stability of lithium market development.
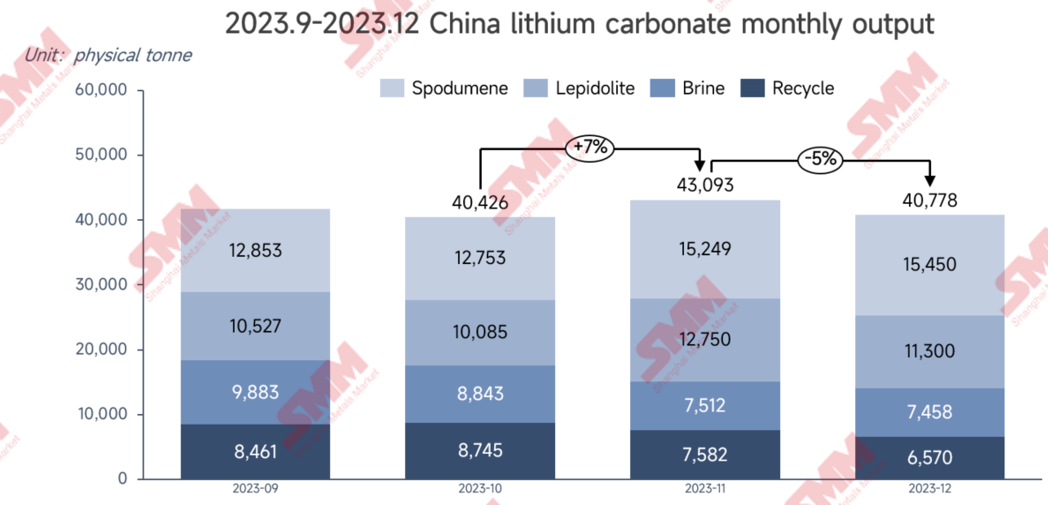
Production Increase: It is relatively easy to meet the exchange's requirements for the registration of warehouse receipts in terms of time.
[From the Rules and Regulations of Guangzhou Futures Exchange on Lithium Carbonate Futures and Options: Article 39, Lithium carbonate with a production date within 60 days (inclusive) from the delivery date are eligible for registration as standard deliverable, while alternative deliverable with a production date within 240 days (inclusive) from the delivery date are also eligible for registration. ]
SMM Data: In November, the increase in output in the lithium carbonate industry was mainly due to the gradual recovery of some lithium salt companies that had reduced production and undergone maintenance in September and October, as well as the continuous ramp-up of some newly added production capacity. However, the output of salt lakes and recycling decreased, mainly due to seasonal production reductions in winter and significant cost pressures, making it difficult for companies to maintain operations. Nevertheless, the decrease in output was not as significant as the increase in the spodumene and lepidolite sectors, resulting in an overall 7% increase in production in November. As we enter December, the output of major lepidolite and spodumene based factories has remained relatively stable, but the decrease in output in salt lakes and recycling has continued. At the same time, due to economic reasons and continuous losses, some lepidolite processing enterprises and spodumene converters relying on external sources have seen a decline in production in December. The combination of these factors is expected to lead to a 5% decrease in overall production in December. Looking ahead, with expectations of a weak price trend in the first quarter due to the off-peak season for consumption, the decrease in production is expected to be more certain. Furthermore, the low production enthusiasm of lithium salt companies due to the Spring Festival and annual maintenance will likely lead to a monthly decline in output, reaching a low point in February.
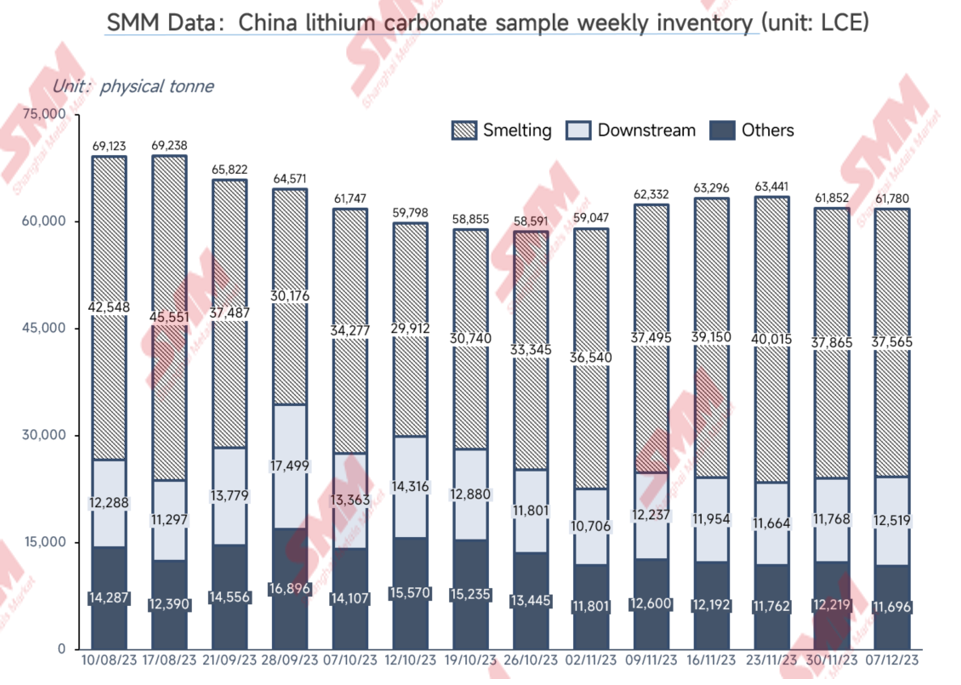
Inventory level: production time unknown. According to SMM, As of December 7th, the total inventory is 62,000 tons, including:
1. Cathode producers’s inventory of 12,500 tons, maintaining a stable production level for downstream customers (Cathode factory inventory at a relatively low level during the price decline);
2. Approximately 16,000 tons from spodumene producer , with lepidolite enterprise inventory of 3,300 tons;
3. Approximately 16,000 tons of salt lake enterprise inventory;
4. Approximately 2,500 tons of inventory for recycling enterprises.
5: Approximately 12000 tons of inventory for others (battery manufactory, traders)
Current spot market flow:
A. Among the inventory and production, the largest monthly flow is the delivery of long contracts from lithium salt factories to downstream customers, accounting for approximately 80-90%.
B. Flowing into the traders for circulation;
C. Placed in delivery warehouses, companies with delivery intentions undergo quality inspection, and those that meet the requirements are converted into warehouse receipts. As of December 13, 2023, there are 710 tons of warehouse receipts at GFEX, an increase of 200 tons from the previous day.
D. Others.
As a conclusion, huge reduction on the number of positions in the GFEX 2401 contract is being witnessed lately, considering the limited amount of possible delivery and the potential short squeeze. However when we look from the current lithium market supply-demand perspective, the current supply of lithium salts is still relatively high, leading to a clear oversupply situation as the performance of terminal demand remains sluggish. At meantime, the GFEX is also activily modifying their rules and regulation to mitigate the possibility of the squeeze.
It is still almost impossible to make a precise conclusion on future trends of the futures market. Our industry-related data is for reference only. Newcomers to the market are advised to be cautious.



