Sodium-ion batteries released by CATL, potentially threats to Li-ion batteries

Published: Aug 03, 2021 11:16 (GMT+8)
CATL recently released sodium-ion batteries, whose relatively higher energy density, fast charging rate, better high and low temperature performance, sufficient resources and low prices have attracted great attention from the lithium battery industry.

Background: In recent years, new energy vehicles have developed rapidly, especially since the second half of last year, the demand has increased significantly, which result in the shortage of raw materials. Among that, cobalt, nickel and lithium resources are insufficient, and prices have risen sharply. In the long run, the cobalt, lithium, nickel raw materials will be in a tight balance in the next 5 years. For lithium batteries, which account for a relatively large material cost (occupies 85%), it will be difficult to reduce the cost in the next 5 years, which will put greater pressure on batteries and car companies.

In this case, CATL recently released sodium-ion batteries, whose relatively higher energy density, fast charging rate, better high and low temperature performance, sufficient resources and low prices have attracted great attention from the lithium battery industry.

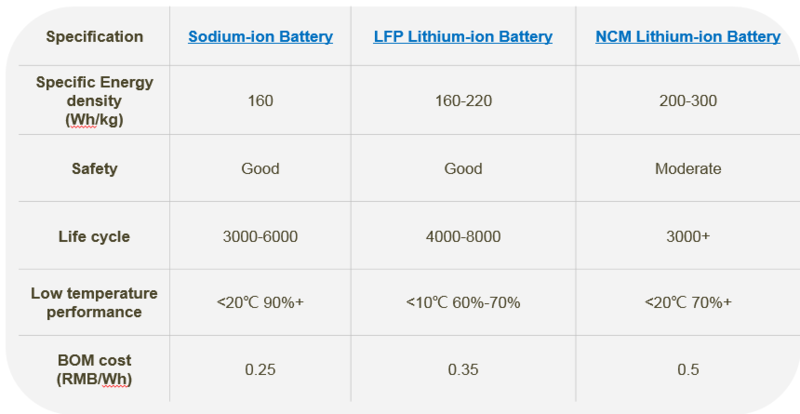
Sodium-ion battery specification

  1. Relatively higher specific energy density

The energy density of the battery cell has reached 160Wh/kg, which is higher of 120-130 Wh/kg, and is close to energy density of LFP&LMO battery cell ( Wh/kg).

  1. Good safety

The of sodium-ion battery is stable, although sodium-ion battery is easy to , its safety test performance is better than that of lithium-ion battery.

  1. Long Life cycle

The battery cell can achieve 3000-6000 , which is significantly higher than that of LCO and NCM battery cell. The life cycle is different in different scenarios, and the cycle will be longer with water cooling systems. It is expected to be more than 8,000 times in the future which is to LFP battery life cycle.

  1. Better low temperature performance

Discharge rate of Sodium-ion battery is 0.3c at -30 degrees, with a capacity retention rate of 80%. And at -20 degrees, capacity retention rate of Sodium-ion battery is above 90%, which is higher than that of Lithium-ion battery.

  1. Lower battery BOM cost

The Sodium-ion battery BOM cost is 0.25 RMB/Wh, which is lower than that of LFP battery (0.35 RMB/Wh). , the BOM cost of sodium-ion battery is 30% lower than that of LFP battery, but the current manufacturing costs of sodium-ion battery are still relatively high. BOM cost plus production costs of Sodium-ion battery are currently higher than that of LFP batteries, because Sodium-ion battery . But it is expected to reach to or lower than LFP battery around 2025.

  1. Sufficient raw material resources

The of sodium-ion battery are higher than lithium-ion battery, and the is lower. The global reserves of sodium are about 2.5% to 3%, which is about 1,000 times than that of lithium resources. In addition, sodium-ion battery almost use no rare metals, but mainly use metals such as iron, aluminum and manganese. These elements are relatively inexpensive compared to cobalt, nickel, lithium that used in lithium-ion battery and the huge market demand in the future.
Sodium-ion battery future application area

  1. Energy storage area

At present, the batteries energy storage market mainly use LFP battery and lead-acid battery. Lithium-ion battery are gradually replacing lead-acid batteries because of their high cycle life, safety and cost performance. From the perspective of cycle life, sodium-ion battery with more than 3,000 times can be used in 5G base stations, and their price may be lower than LFP batteries in 2025, or gradually replace LFP battery in 2025. Large energy storage (such as wind power photovoltaics, etc.) has higher requirements for life cycle, which is basically about 8,000 times, and its , or it is more inclined to use LFP battery with higher cycle life.

  1. Light electric vehiclesarea

Light electric vehicles require moderate life cycle (around 2000 times), lower battery cost and . Sodium-ion battery meet the requirement and its battery cost will be lower than LFP battery, so it may in light electric vehicles in 2025.

In conclusion, Sodium-ion battery will be applied to scenarios that do not require high energy density, but require cost-efficient and higher life cycle, such as energy storage,light electric vehicles, low-to-medium level new energy vehicles and construction machinery. It will not be able to replace the lithium-ion battery for a considerable period of time in the future, and it will be complementary to the lithium-ion battery.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Cobalt-Lithium Morning Meeting Summary] Raw material price trends diverge; supply-demand support for battery materials varies in strength
4 hours ago
[SMM Cobalt-Lithium Morning Meeting Summary] Raw material price trends diverge; supply-demand support for battery materials varies in strength
Read More
[SMM Cobalt-Lithium Morning Meeting Summary] Raw material price trends diverge; supply-demand support for battery materials varies in strength
[SMM Cobalt-Lithium Morning Meeting Summary] Raw material price trends diverge; supply-demand support for battery materials varies in strength
This week, the battery industry chain showed divergent trends. Spot lithium ore was tight, but expectations of future supply growth weighed on prices. On October 12, the average spot price of lithium carbonate fell to 115,400 yuan/mt, down 6,950 yuan/mt in a single day. Futures declined with rising open interest, while social inventory continued to destock. Lithium hydroxide, cobalt salt, and nickel sulphate were under pressure, with cautious purchasing. Ternary cathode precursor, ternary cathode material, and LCO weakened along with raw materials. LFP orders were relatively strong, with high-quality production lines running near full capacity and finished product inventories declining. Iron phosphate operating rates were high, but resistance to price increases grew. Artificial graphite edged up, supported by costs and demand, while natural graphite operated at low levels. Separator was supported by NEV, energy storage, and export rush demand, with supply-demand conditions tight. Electrolyte rose due to lagged cost pass-through. Sodium-ion battery production and delivery were stable, while recycling-side inquiries recovered but transactions did not increase in volume. In news, CATL deepened cooperation with Seres. In the first three quarters, NEV production and sales both exceeded 12 million units. Export tax rebate policy adjustments and China-EU automotive trade consultations drew attention.
4 hours ago
[SMM Cobalt Morning Meeting Summary] Weak Demand and Falling Raw Material Prices Increase Destocking Pressure Across the Entire Industry Chain
4 hours ago
[SMM Cobalt Morning Meeting Summary] Weak Demand and Falling Raw Material Prices Increase Destocking Pressure Across the Entire Industry Chain
Read More
[SMM Cobalt Morning Meeting Summary] Weak Demand and Falling Raw Material Prices Increase Destocking Pressure Across the Entire Industry Chain
[SMM Cobalt Morning Meeting Summary] Weak Demand and Falling Raw Material Prices Increase Destocking Pressure Across the Entire Industry Chain
At the start of this week, the cobalt industry chain remained weak overall, with downstream procurement mainly need-based and market trading sluggish. The mainstream ex-works price for refined cobalt held at 270,000 yuan/mt, while traders raised their basis. There was a divergence between the floor purchase price of $14.5/lb for intermediate products and downstream acceptance prices below $13/lb. Cobalt sulphate was quoted at around 60,000 yuan/mt, with weakening cost support; cobalt chloride and Co3O4 saw production cuts and destocking, while new orders were insufficient. Cobalt powder quotes fell to 325,000–340,000 yuan/mt, and high-priced inventory weighed on procurement. Ternary cathode precursor and ternary cathode material prices weakened, with order coefficients under pressure; export orders were relatively better, while domestic demand recovery remained limited. LCO pulled back along with costs, and peak-season expectations fell through. The industry is focused on order changes following the annual conference. In news, CATL and Seres deepened cooperation on capacity and outside China; NEV production and sales both exceeded 12 million units in the first three quarters, with notable export growth; export rebate rates are set to be lowered, and China-EU auto trade consultations clarified basic principles.
4 hours ago
September Sodium-Ion Battery Electrolyte and Battery Cell Market Analysis: Electrolyte Poised for Volume Growth, Battery Cell Under Pressure in Peak Season [SMM Analysis]
5 hours ago
September Sodium-Ion Battery Electrolyte and Battery Cell Market Analysis: Electrolyte Poised for Volume Growth, Battery Cell Under Pressure in Peak Season [SMM Analysis]
Read More
September Sodium-Ion Battery Electrolyte and Battery Cell Market Analysis: Electrolyte Poised for Volume Growth, Battery Cell Under Pressure in Peak Season [SMM Analysis]
[SMM Analysis: September Sodium-Ion Battery Electrolyte and Battery Cell Market Analysis: Electrolyte Poised for Volume Release, Battery Cell Under Pressure in Peak Season] SMM, October 13: Entering September, the sodium-ion battery industry chain further evolved its operating characteristic of "advancing amid divergence." The electrolyte segment continued the operating logic of "having capacity but no volume release," with shipments highly concentrated among top-tier players and growth mainly flowing to undisclosed major clients. A window for large-scale ramp-up is expected to materialize in Q4 with the fulfillment of GWh-level orders. In the battery cell segment, order deliveries were released intensively under the "September-October peak season" signal, but the actual pace of project implementation clearly fell short of plans, with regional and application-scenario divergence intensifying...
5 hours ago