[SMM thread] the road of accumulation is not over, and the upward road of steel price is not over.

Published: Jul 16, 2020 17:47
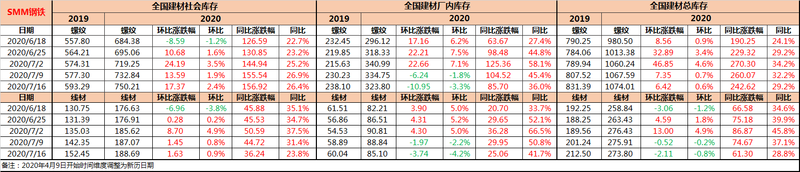
As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current year-on-year increase in inventory continues to narrow. (this week, the year-on-year increase of thread pool narrowed by 3%.


SMM7 March 16:

As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current inventory growth continues to narrow year-on-year (this week, the thread pool growth rate narrowed by 3 percentage points year-on-year).

Table 1: Overview of thread inventory
Source: SMM


Table 2: comparison of Thread inventory prices from 2018 to 2020
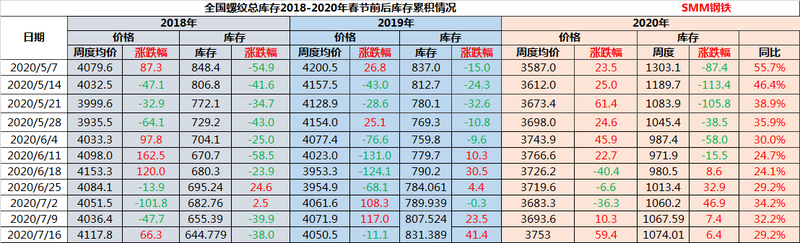
Note: due to the epidemic factors since 2020, due to the different opening times in different places, there is a certain error in the actual spot average price; the time dimension is the Gregorian calendar date.


Source: SMM

Specifically:

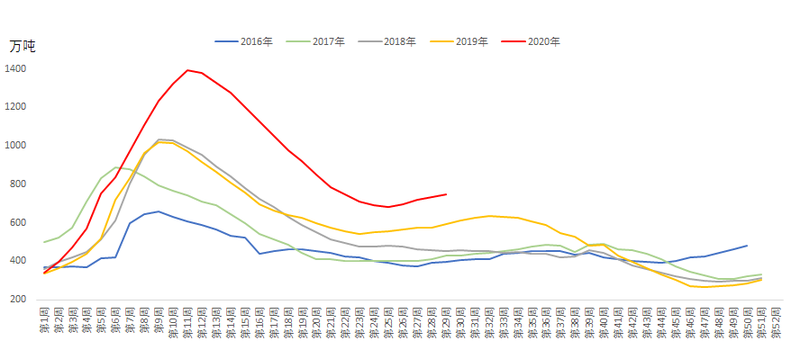
Social inventory of 7.5021 million tons, an increase of 173700 tons this week, + 2.4% month-on-month, + 26.9% year-on-year.

Under the background of a positive situation in the A-share bull market, the raw material side was led by the news side to rise first, driving the period snail to continue the strong situation in the past two weeks. The expectation of the spot market for the future is also improving, and the enthusiasm of traders to take goods has been significantly improved, accelerating the transfer of the factory warehouse to the social warehouse. While the terminal "steel needs" is "serious illness has not been cured", so the speed of accumulation has been accelerated.

Figure 1: an overview of the trend of threaded community library since 2016
Source: SMM

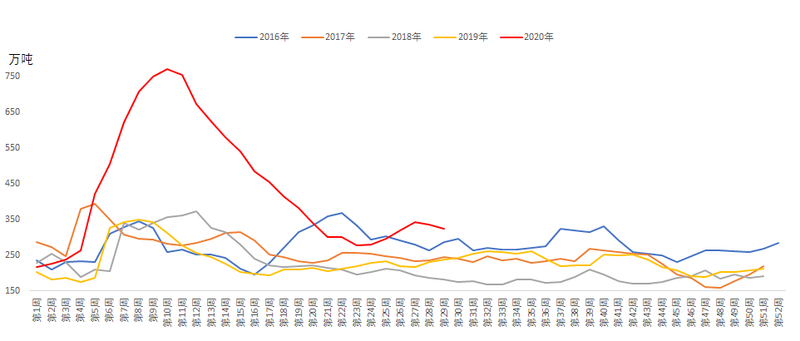
The inventory in the plant is 3.238 million tons, down 109500 tons this week,-3.3% month-on-month, + 36.0% year-on-year.

In addition to the market merchants' enthusiasm for taking goods driven by strong expectations, the decline in the output of steel mills is also an important reason for the decline in the factory warehouse. Under the dual pressure of high plant pressure and poor profitability, the overhaul and production reduction plans of steel mills have increased-according to SMM research, the planned rebar output of blast furnace steel mills in July decreased by 2% compared with the actual output in June, and the operating rate of electric furnace plants also dropped by about 11.52% compared with the same period in June.


Figure 2: an overview of the trend of thread factory warehouse from 2016 to now
Source: SMM

In the short term, the fundamentals of rebar are not unusual-the supply side is likely to maintain a small fluctuation at the current level, the demand side continues to be hit by precipitation, the road to rebar accumulation is not over, and steel prices are still in an awkward position of "neither up nor down". However, as more and more regions out of the "rainy season" haze, rush demand released as scheduled, thread fundamentals regained strong support, steel prices are expected to consolidate and continue to start.




Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
Sep 11, 2026 18:30
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
Read More
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
On September 9, 2026, Australia initiated its second sunset review of anti-dumping measures on galvanized steel sheet from India, Malaysia and Vietnam, and separately launched a sunset review of countervailing measures on imports from India. The review covers July 2025-June 2026, with the final report expected by February 11, 2027. As galvanized steel is the largest end-use sector for zinc, the measures directly affect export costs and competitiveness, potentially impacting Australia’s domestic zinc demand and supply chain. Maintaining the duties would provide some protection for domestic steel and coating capacity, while termination could increase low-priced imports and affect regional zinc consumption. The final outcome remains subject to the authorities’ determination.
Sep 11, 2026 18:30
JCC Hongyuan Copper's $200M Expansion Project Aims to Boost Capacity to 550,000 mt by 2027
Sep 7, 2026 15:43
JCC Hongyuan Copper's $200M Expansion Project Aims to Boost Capacity to 550,000 mt by 2027
Read More
JCC Hongyuan Copper's $200M Expansion Project Aims to Boost Capacity to 550,000 mt by 2027
The 300,000 mt/year copper cathode expansion project of JCC Hongyuan Copper, a subsidiary of Jiangxi Copper Corporation, entered the pre-approval public notice stage of its environmental impact assessment on September 4, with a total investment of approximately 1.416 billion yuan. The project is planned to start construction in September 2026 and be completed in December 2027. Upon completion, JCC Hongyuan's total capacity will jump from 250,000 mt to 550,000 mt.
Sep 7, 2026 15:43
Japanese Yen Increases USD/JPY Drops Below 159 Amid Intervention Speculation
Sep 3, 2026 19:00
Japanese Yen Increases USD/JPY Drops Below 159 Amid Intervention Speculation
Read More
Japanese Yen Increases USD/JPY Drops Below 159 Amid Intervention Speculation
[SMM Precious Metal Express] The Japanese yen spiked sharply during Wednesday's trading, with USD/JPY falling below 159 and closing down 0.92% at 158.69, sparking speculation of Japanese currency intervention. The dollar index also dropped sharply, with a weaker dollar environment providing support for precious metals.
Sep 3, 2026 19:00

