
Hoshine Silicon to add 800,000 mt/year silicon metal capacity in Yunnan

Telah Terbit: Dec 13, 2019 10:37 (GMT+8)
Sustainable availability of high-grade silicon ore has made Zhaotong in Yunnan province ideal for investment

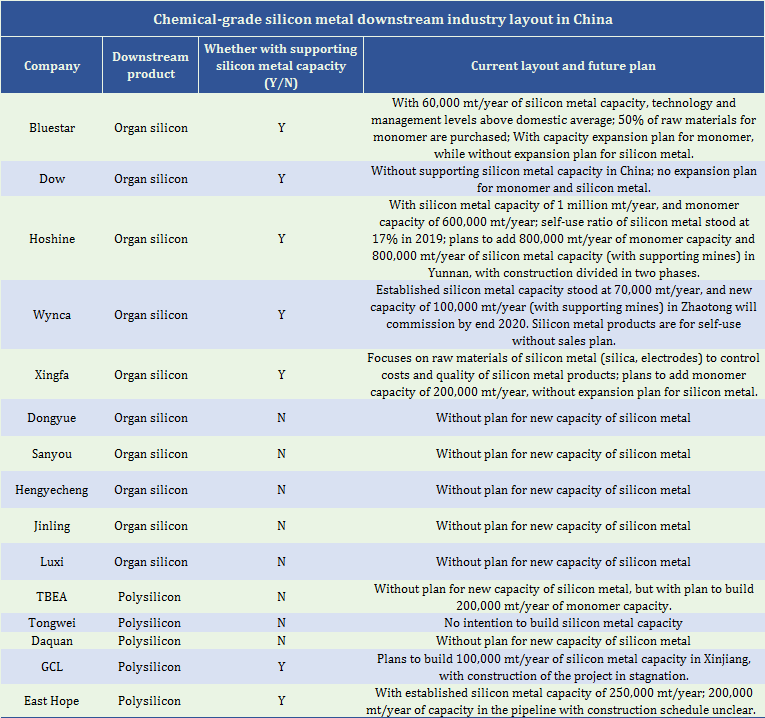
SHANGHAI, Dec 13 (SMM) –Hoshine Silicon, a Zhejiang-headquartered major silicon producer in China, will build 800,000 mt/year of silicon metal capacity in Zhaotong, Yunnan province. 

Although electrical power costs in Zhaotong are higher compared with other cities in Yunnan, sustainable availability of high-grade silicon ore has made Zhaotong ideal for investment, amid supply tightness of high-quality ore in China.

Yunnan currently has an annualised designed capacity of 1.3 million mt, located mostly in the western part of the province, including Dehong, Baoshan, Nujiang, and Lincang that boast rich hydro-power resources. 

The capacity utilisation rate, however, stands at low levels in Yunnan due to maintenance and dry season issues. The monthly average operating rate at silicon producers in the province stood at 46% in 2018. 

China’s silicon industry features low concentration ratios, as small and medium-scale producers with a capacity below 40,000 mt/year accounted for 89% in terms of number and 53% in terms of production capacity of the total silicon producers in China.

Silicon plants in Yunnan are mostly of medium-scale with an annualised capacity of 20,000 mt, invested by companies in Fujian and Zhejiang provinces before 2010. The past decade saw limited silicon capacity addition and expansion projects in Yunnan.

The opportunity of expansion/merger of Yunnan's existing small and medium-scale silicon companies came even smaller as the local implementation of desulfurisation methods over the past two years, ahead of other major silicon production areas in China, increased the cost of investment by around 10%.

Silicon metal can be categorised into metallurgical-grade and chemical-grade products based on downstream applications. Metallurgical-grade silicon, used to produce aluminum alloy, also sees limited chances of new investment due to demand bottleneck in the downstream car market, which is the main consumer of silicon-aluminium alloy. Besides, silicon accounts for only 3-7% of the feedstock to make silicon-aluminium alloy.

There will be more opportunities to invest in chemical-grade silicon on the back of the domestic shortage of high-quality ore and the trend in demand growth. Chemical-grade silicon is used mostly in organ silicon monomer and polysilicon, which have higher requirements for the stability and composition element of raw materials. 

For instance, chemical-grade silicon metal has to reach certain standards of content regarding not only main impurities such as iron, aluminium, and calcium, but also trace elements like phosphorus, boron, titanium, and carbon. 

On the policy front, major production areas such as Yunnan and Xinjiang have imposed controls on the total silicon capacity, but a national-level production quota scheme has not been introduced.  Yunnan aims to control silicon metal capacity within the province below 1.3 million mt/year by 2020, while boosting production and capacity of the top five producers to above half of the market share. 

New silicon projects in Yunnan should be equipped with downstream facilities to obtain government approval.

Xinjiang enjoys the advantages of lower electricity prices and thermal power plants that could guarantee production all year round without the impact of seasonality.  In terms of production capacity, Xinjiang has surpassed Yunnan to become the top silicon metal producer in China in 2015.

Addition of silicon capacity and construction of new self-owned power plants in Xinjiang face greater restrictions since 2018 as Xinjiang shifted its focus to high-level development. 

As a total 2 million mt silicon metal capacity quotas were all issued in Xinjiang, large companies are mulling acquisition or replacement of unrealised quotas for their further expansion. 

Besides capacity quotas, limitations on carbon emissions in each province will also be closely monitored.

Some silicon producers in Xinjiang were forced to cut or halt production due to depletion of carbon emissions quotas, a SMM survey showed. Some silicon mills in Fujian even purchased emissions quotas to extend production. 

A severe mismatch between the production capacity and carbon emission quotas has been seen across silicon production areas in China.

Pernyataan Sumber Data: Kecuali informasi yang tersedia untuk publik, semua data lainnya diproses oleh SMM berdasarkan informasi publik, komunikasi pasar, dan mengandalkan model database internal SMM. Hanya untuk referensi dan tidak menjadi rekomendasi pengambilan keputusan.

Untuk pertanyaan atau informasi lebih lanjut, silakan hubungi: lemonzhao@smm.cn
Untuk informasi lebih lanjut tentang cara mengakses laporan penelitian kami, hubungi:service.en@smm.cn
Berita Terkait
Melemahnya dukungan biaya untuk silikon; harga DMC sedikit diturunkan [Tinjauan Mingguan Silikon SMM]
53 menit yang lalu
Melemahnya dukungan biaya untuk silikon; harga DMC sedikit diturunkan [Tinjauan Mingguan Silikon SMM]
Baca Selengkapnya
Melemahnya dukungan biaya untuk silikon; harga DMC sedikit diturunkan [Tinjauan Mingguan Silikon SMM]
[SMM Tinjauan Mingguan Silikon: Dukungan Biaya untuk Silikon Melemah, Harga DMC Sedikit Turun] Minggu ini, biaya silikon secara keseluruhan mengalami penurunan, dan biaya produksi komprehensif industri ikut menurun. Hingga 22 Oktober, harga rata-rata logam silikon #421 untuk penggunaan silikon di Tiongkok timur berada di 9.750 yuan/mt, relatif stabil; harga transaksi utama logam silikon #421 di Tiongkok timur rata-rata 9.550 yuan/mt, turun 0,52% WoW, dengan harga logam silikon cenderung menurun minggu ini. Sementara itu, harga pasar metanol mengalami penurunan, sehingga menekan biaya metil klorida. Minggu ini, harga pasar rata-rata metil klorida adalah 3.450 yuan/mt, turun 6,76% WoW.
53 menit yang lalu
【Kilas | Aliran Molibdenum Korea Selatan Berbeda karena Impor Konsentrat Turun 26%】
1 jam yang lalu
【Kilas | Aliran Molibdenum Korea Selatan Berbeda karena Impor Konsentrat Turun 26%】
Baca Selengkapnya
【Kilas | Aliran Molibdenum Korea Selatan Berbeda karena Impor Konsentrat Turun 26%】
Korea Selatan mengimpor 2.707,3 ton konsentrat molibdenum panggang dan lainnya pada September 2026, turun 25,9% YoY, menurut perhitungan SMM berdasarkan data bea cukai. Impor konsentrat panggang turun 28,8% menjadi 1.740,0 ton, termasuk 500,0 ton dari Chile dibandingkan 1.410,7 ton pada tahun sebelumnya. Ekspor konsentrat panggang naik 6,5% menjadi 516,6 ton, terutama ke Jepang, India, dan Vietnam. Ekspor feromolibdenum turun 29,2% menjadi 1.121,1 ton, dengan pengiriman ke China turun dari 580,0 menjadi 70,5 ton. Impor molibdenum oksida dan hidroksida naik 311,0% MoM menjadi 97,2 ton, meskipun volume Januari–September turun 39,2% YoY. Arus bea cukai nasional tidak dapat mengukur throughput pelabuhan Busan atau stok spot gudang.
1 jam yang lalu
Kebuntuan Multi-Segmen Hulu PV Tetap Stabil, Harga Modul Terus Menurun [Tinjauan Mingguan SMM]
1 jam yang lalu
Kebuntuan Multi-Segmen Hulu PV Tetap Stabil, Harga Modul Terus Menurun [Tinjauan Mingguan SMM]
Baca Selengkapnya
Kebuntuan Multi-Segmen Hulu PV Tetap Stabil, Harga Modul Terus Menurun [Tinjauan Mingguan SMM]
[SMM Tinjauan Mingguan: Segmen Hulu PV Bertahan Stabil dalam Kebuntuan, Harga Modul Terus Meluncur] Pekan ini, harga pasar sel surya tetap stabil secara keseluruhan, dengan kuotasi semua ukuran tidak berubah WoW. Pasokan tetap pada level rendah dan inventaris terus berkurang. Pasar menjaga keseimbangan antara dukungan biaya dan divergensi permintaan, dengan tarik-menarik antara hulu dan hilir yang masih berlanjut. Harga diperkirakan tetap stabil dalam jangka pendek. Dari sisi harga, semua ukuran bertahan stabil. Kisaran harga 183 tetap di 0,29-0,301 Yuan/W. Kisaran harga 210R bertahan di 0,305-0,314 Yuan/W, masih didominasi oleh ekspor ke pasar di luar Tiongkok. Jendela ekspor diperkirakan berlanjut hingga awal November, dengan pasokan diprioritaskan untuk pesanan ekspor. Pasokan domestik yang tersedia terbatas, sehingga tidak ada dasar untuk penyesuaian harga. Kisaran harga 210N bertahan di 0,295-0,3 Yuan/W, stabil setelah kenaikan pekan lalu. Meskipun produsen wafer berniat menahan harga, penurunan harga perak yang terus berlanjut baru-baru ini telah mengimbangi dukungan dari sisi biaya, membatasi momentum kenaikan harga. Pada tahap ini, pembeli hilir mengisi ulang stok sesuai kebutuhan, dengan negosiasi pesanan aktual terkunci dalam tarik-menarik yang stabil. Dalam jangka pendek, kebuntuan hulu-hilir dapat berlanjut hingga awal November, dan harga semua ukuran diperkirakan tetap stabil atau bergerak sideways.
1 jam yang lalu

