Zambia plans its first gold ETF
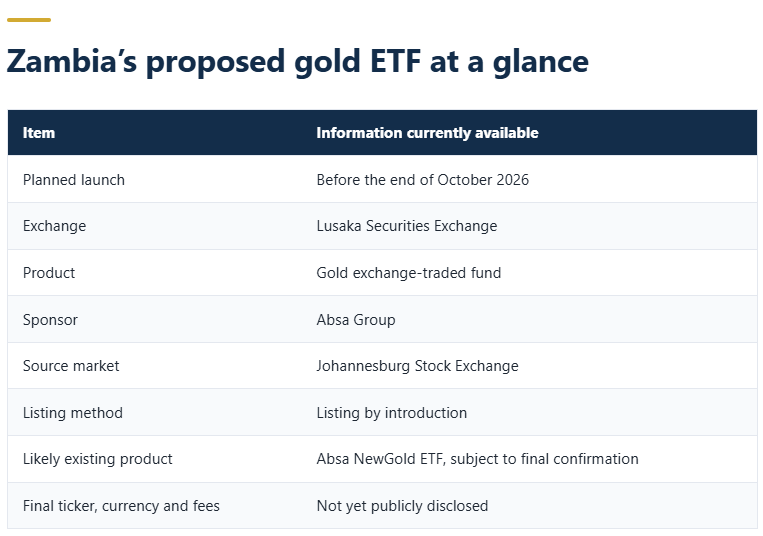
The Lusaka Securities Exchange (LuSE) plans to introduce Zambia's first gold Exchange-Traded Fund (ETF) before the end of October 2026, according to the chief executive Nicholas Kabaso. The proposed Absa-sponsored product would be introduced from the Johannesburg Stock Exchange. As at 15 October, there is no confirmation that trading has begun. [1, 4]
The proposal could give investors a local exchange route to gold-price exposure. Its significance for Zambia's mining sector may also depend on whether any direct link to domestic metal is established.
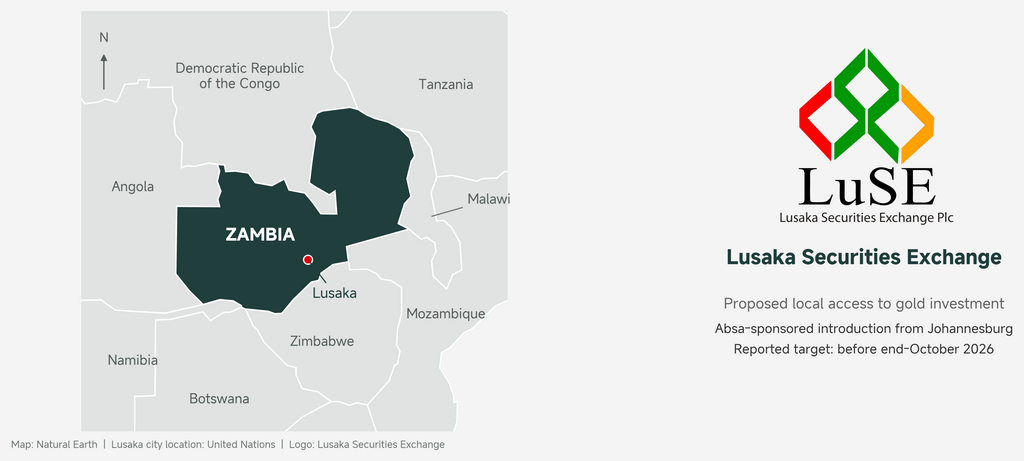
Figure 1. Zambia and Lusaka, with the official LuSE logo. Sources: Natural Earth [9], United Nations [10] and LuSE [11].
How investors would gain exposure to gold
An ETF trades on an exchange much like a share. A gold-linked product allows investors to follow the metal's price without arranging personal bullion storage. [2] Absa's existing NewGold securities are backed by bullion held with a custodian and represent approximately one-hundredth of a troy ounce each. This describes the existing product; Zambia's final listing documents must confirm the security and local terms. [3, 4]
Investors would hold a gold-linked security rather than shares in a mining company. Introducing an existing security also differs from a new public offer: admission to LuSE would not, by itself, establish fresh funding for Zambian mines. [4]
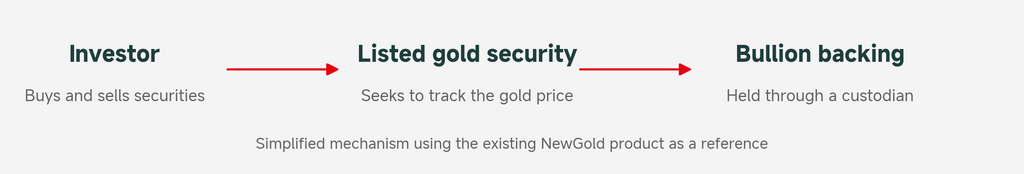
Figure 2. Simplified investment mechanism. Sources: LuSE [2] and Absa [3]. The final Zambian terms remain to be confirmed.
Why it matters for Zambia's investment market
For individuals and institutions, the attraction would be an additional asset alongside company shares and bonds. Gold could help diversify a portfolio, although it offers no guaranteed protection against inflation or losses. The investor's result would depend on gold prices, exchange rates and costs. [4]
Currency effects matter even when the underlying metal is unchanged. A stronger kwacha reduces the local-currency value of a given dollar gold price; a weaker kwacha increases it. In the June–December 2025 comparison below, the dollar gold-price index rose about 29%, while its calculated kwacha equivalent rose about 20%. These are movements between monthly-average values before costs, not realised investment returns. [5, 6]
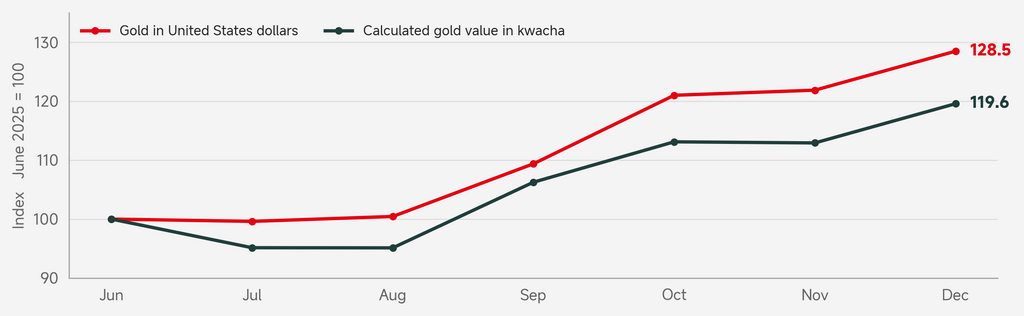
Figure 3. Monthly-average gold values, June–December 2025. Both series start at 100. The kwacha series is calculated from the dollar gold price and the Bank of Zambia monthly-average mid-rate; it excludes fees and spreads and is not an ETF return. Sources: World Bank [5] and Bank of Zambia [6]; author.
What it could mean for Zambia's gold sector
Wider participation in gold investment could develop without additional purchases from Zambian mines. Trading an existing bullion-backed security does not establish where its backing metal was mined. The ETF reports reviewed contain no commitment to source Zambian gold, finance mines or support local refining. [1, 3, 4]
That distinction builds on SMM's earlier analysis of Zambia's gold market. [7] Zambia Gold Company says Kasenseli mine output is sold to the Bank of Zambia, while gold bought from artisanal and small-scale miners is sold through separate offtake agreements, meaning arrangements with buyers. Those physical buying channels should not be treated as part of the proposed ETF. [8]
A direct local benefit would require evidence of sourcing contracts, traceable supply or financing arrangements. Until then, a larger investment audience cannot be counted as increased domestic production or formal gold purchases.
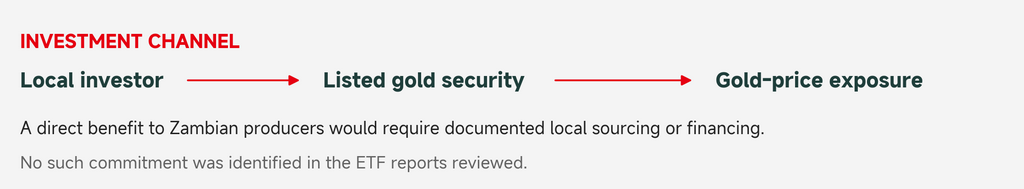
Figure 4. Analytical distinction between investment access and domestic supply benefits, based on [1, 3, 4, 8]. It does not depict a local procurement arrangement.
What will determine its practical impact
Practical access will depend on whether investors can buy and sell at reasonable cost. Liquidity means being able to trade without materially moving the price. Market makers, which quote buying and selling prices, could help narrow the bid–ask spread: the gap between those prices. Fees, minimum trade sizes and clear explanations will also affect accessibility. [4, 12]
Final product documents should confirm the listing date, trading currency, custody arrangements and applicable approvals. [4] Regular disclosure of net asset value, meaning assets minus liabilities divided by securities outstanding, would help investors assess market prices. [12]
LuSE's separate pipeline of five prospective company listings reportedly could raise about one billion United States dollars (US$1 billion); that is not an ETF fundraising target. [1] The ETF's progress should instead be judged by reliable pricing, sustained trading and any documented connection to Zambia's gold producers.
References
[1] Business Insider Africa. 17 September 2026. Zambia targets $1 billion from five new listings as first gold ETF nears launch. Reporting attributed to Bloomberg.
[2] Lusaka Securities Exchange. Equity Securities. Definition and exchange trading of ETFs.
[3] Absa. NewGold ETF. Existing South African product description and bullion backing.
[4] Insight Partners Africa. 29 September 2026. Zambia's First Gold ETF. Proposed listing, unresolved terms and investment risks.
[5] World Bank. Commodity Price Data, updated 2 October 2026. Monthly Prices worksheet, Gold column.
[6] Bank of Zambia. Annual Report 2025, statistical appendix, Table 10, printed page 180. Monthly-average mid-rates.
[7] Shanghai Metals Market. 23 September 2026. A Snapshot of Zambia's Gold Market: From Mine Output to Formal Trade. Background only.
[8] Zambia Gold Company. Gold Trading. Separate routes for Kasenseli output and purchases from small miners.
[9] Natural Earth. Public-domain country boundaries at 1:110 million scale.
[10] United Nations geographical names dashboard. Lusaka location. Map point marks the city, not the exchange building.
[11] Lusaka Securities Exchange. Official logo obtained from the exchange website.
[12] United States Securities and Exchange Commission. Investor Bulletin on ETFs. General explanations of trading costs, spreads and net asset value; not Zambian listing rules.