A Rebound Off a Weak July
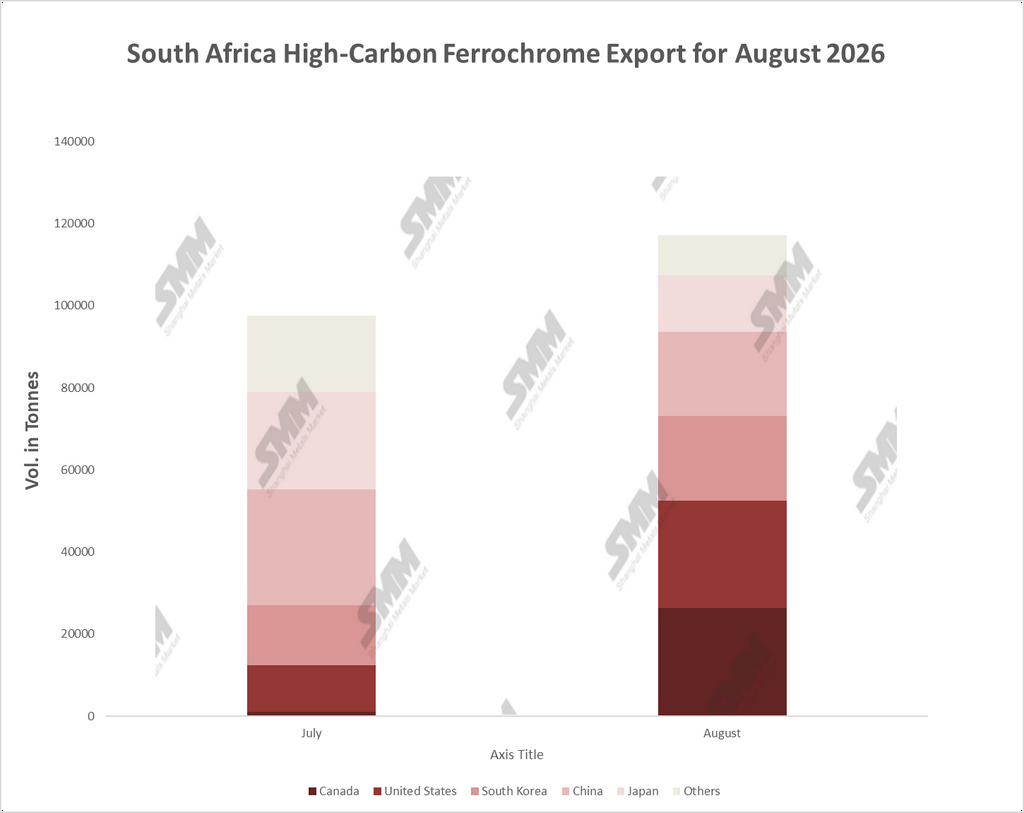
South Africa's high-carbon ferrochrome (HC FeCr) exports rose to 117,180 mt in August 2026, up 20.0% month-on-month from July's restated 97,618 mt, an increase of 19,562 mt. The gain recovers July's slump and returns volumes to about April's level of roughly 117,000 mt. August is still 5.0% below June's 123,310 mt. Against August 2025, shipments were around 45.8% higher, based on the roughly 80,400 mt SARS recorded in that month. That comparison flatters the rebound, because August 2025 was itself 73.7% below August 2024 as smelter shutdowns took hold. The monthly figures have moved within a band of roughly 98,000 to 124,000 mt since April. August's recovery brings them back inside that band without breaking out of it.
North America Takes Over at the Top
The destination mix changed more than the total did. Canada's imports jumped from 1,054 mt in July to 26,373 mt in August, a 25-fold increase that made it the largest single destination, with 22.5% of exports. The United States rose 128.0% to 26,029 mt, lifting its share from 11.7% to 22.2%. Together the two North American markets took 52,401 mt, or 44.7% of exports, against 12,470 mt and 12.8% in July. Their combined gain of 39,931 mt is double the net increase in total exports, which means the rest of the market shrank. A one-month move of this size in Canada points to a small number of large consignments, not a step-change in demand. The next few months will show whether it repeats.
US Buying Holds Up Despite a Higher Tariff
The US increase came with the 12.5% Section 301 duty on South African goods in force. It took effect on July 24 and replaced the 10% global tariff that expired the same day. It applies to most products. Cargoes loaded in August were therefore committed knowing that the higher duty would apply on arrival. That US buyers still took more points to limited alternatives. The US sourced about 41% of its ferrochromium imports from South Africa in the 2021–24 period, according to the US Geological Survey. Monthly volumes in these markets are lumpy, so one month's move should be read with caution.
China's Retreat Deepens
China took 20,505 mt, down 27.5% from July and 47.3% below June's 38,921 mt. Its share of South African exports has fallen from 31.6% in June to 29.0% in July and 17.5% in August, and it now ranks fourth among the destinations reported, behind Canada, the US and South Korea. Shipments to China were also roughly 46% below August 2025's 38,200 mt. The cause is weak demand and ample domestic supply in China. SMM data show Chinese ferrochrome supply grew 12.94% in the first half of 2026, while chrome demand from stainless steel output rose only 2.3%. China Customs data show the same pattern. HC FeCr arrivals from South Africa were 50,316 mt in August after none in July, a recovery that reflects cargoes loaded in June and July. January–August arrivals from South Africa were 181,616 mt, down 78.1% year-on-year. South Africa's share of China's HC FeCr imports fell to 16.3% from 45.4%, while Kazakhstan's rose to 57.1%.
South Korea Steadies, Japan Reverses
South Korea rose 43.3% to 20,790 mt, lifting its share from 14.9% to 17.7%. That is only 1.4% above June's 20,502 mt, so the August figure is a return to normal after July's dip, not new buying. Japan fell 42.1% to 13,727 mt, which is 23.7% below June's 17,988 mt. That more than reversed July's 31.8% surge and indicates that month's gain reflected shipment timing and not a lasting shift in demand. The “Others” grouping, which now includes Italy, fell 47.6% to 9,757 mt, and its share dropped from 19.1% to 8.3%.
Supply Recovery Still Early
The rebound is consistent with the first incremental output from the Glencore-Merafe Chrome Venture's restarted smelters, though the data cannot confirm this. Wonderkop and Boshoek began restarting at the end of June after Eskom finalized the 62 cents/kWh agreements. Merafe expects the ramp-up to be fully complete towards the end of the year. It guides to 2026 ferrochrome production of only 25–29% of installed capacity. Merafe's attributable first-half production (its 20.5% share of the venture) fell 75% to 28,000 mt, and unit production costs rose 61%. Samancor Chrome cancelled its Section 189 retrenchment process in late June and said it intends to resume production at all its smelters within six months. These restarts are still in progress, so export volumes remain a small fraction of earlier levels.
|
Outlook: South African ferrochrome exports should trend higher over the coming months as the restarts at Wonderkop, Boshoek and Samancor's smelters ramp up. The market for that volume is the harder question. China is unlikely to absorb more South African metal while its own supply outgrows stainless steel demand, and Tsingshan and other major mills cut their October ferrochrome tender prices by RMB 200 per 50 mtu unit. Shipments will have to find homes elsewhere, mainly in South Korea, Japan and North America. North American demand is lumpy and now carries a 12.5% tariff on the US side, so it cannot replace China's role reliably. The test is whether September shows Canada and the US sustaining volumes at or near August levels. |