Solid-State Battery Accelerates, Supply Chain Diverge Sharply – Review of Listed Companies' H1 2026 Performance

Published: Aug 17, 2026 15:16 (GMT+8)
H1 2026, performance of listed companies in the solid-state battery supply chain showed stark divergence. Traditional lithium battery material suppliers reaped huge profit growth (Tinci Materials +>900%) due to price rebounds, while overseas start-ups remained deep in the red (QuantumScape net loss $199M).

Key Takeaways :In H1 2026, performance of listed companies in the solid-state battery supply chain showed stark divergence. Traditional lithium battery material suppliers reaped huge profit growth (Tinci Materials +>900%) due to price rebounds, while overseas start-ups remained deep in the red (QuantumScape net loss $199M). Chinese battery giant CATL steadily advanced all-solid-state R&D, while material players like Daoshi Technology and Sinocera achieved small-volume shipments of solid-state electrolytes. Samsung SDI swung to profit, driven by ESS and AI data centre demand. Overall, solid-state battery commercialisation is accelerating, but profitability is still some way off.
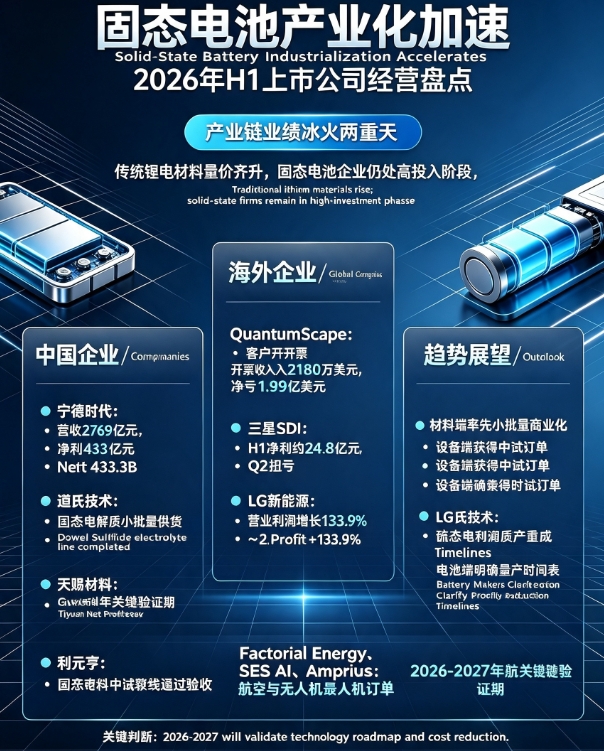


We observed that in the first half of 2026, the operating performance of solid-state battery-related listed companies presented a "fire and ice" divergence. On one hand, traditional lithium battery material producers saw substantial earnings growth driven by rising product prices and demand recovery; on the other hand, start-ups focused purely on solid-state technology remained in loss-making high-investment phases, yet customer collaborations and industrialisation progress significantly accelerated.


1. Chinese Companies: Materials Segment Booms, Battery Players Gather Steam
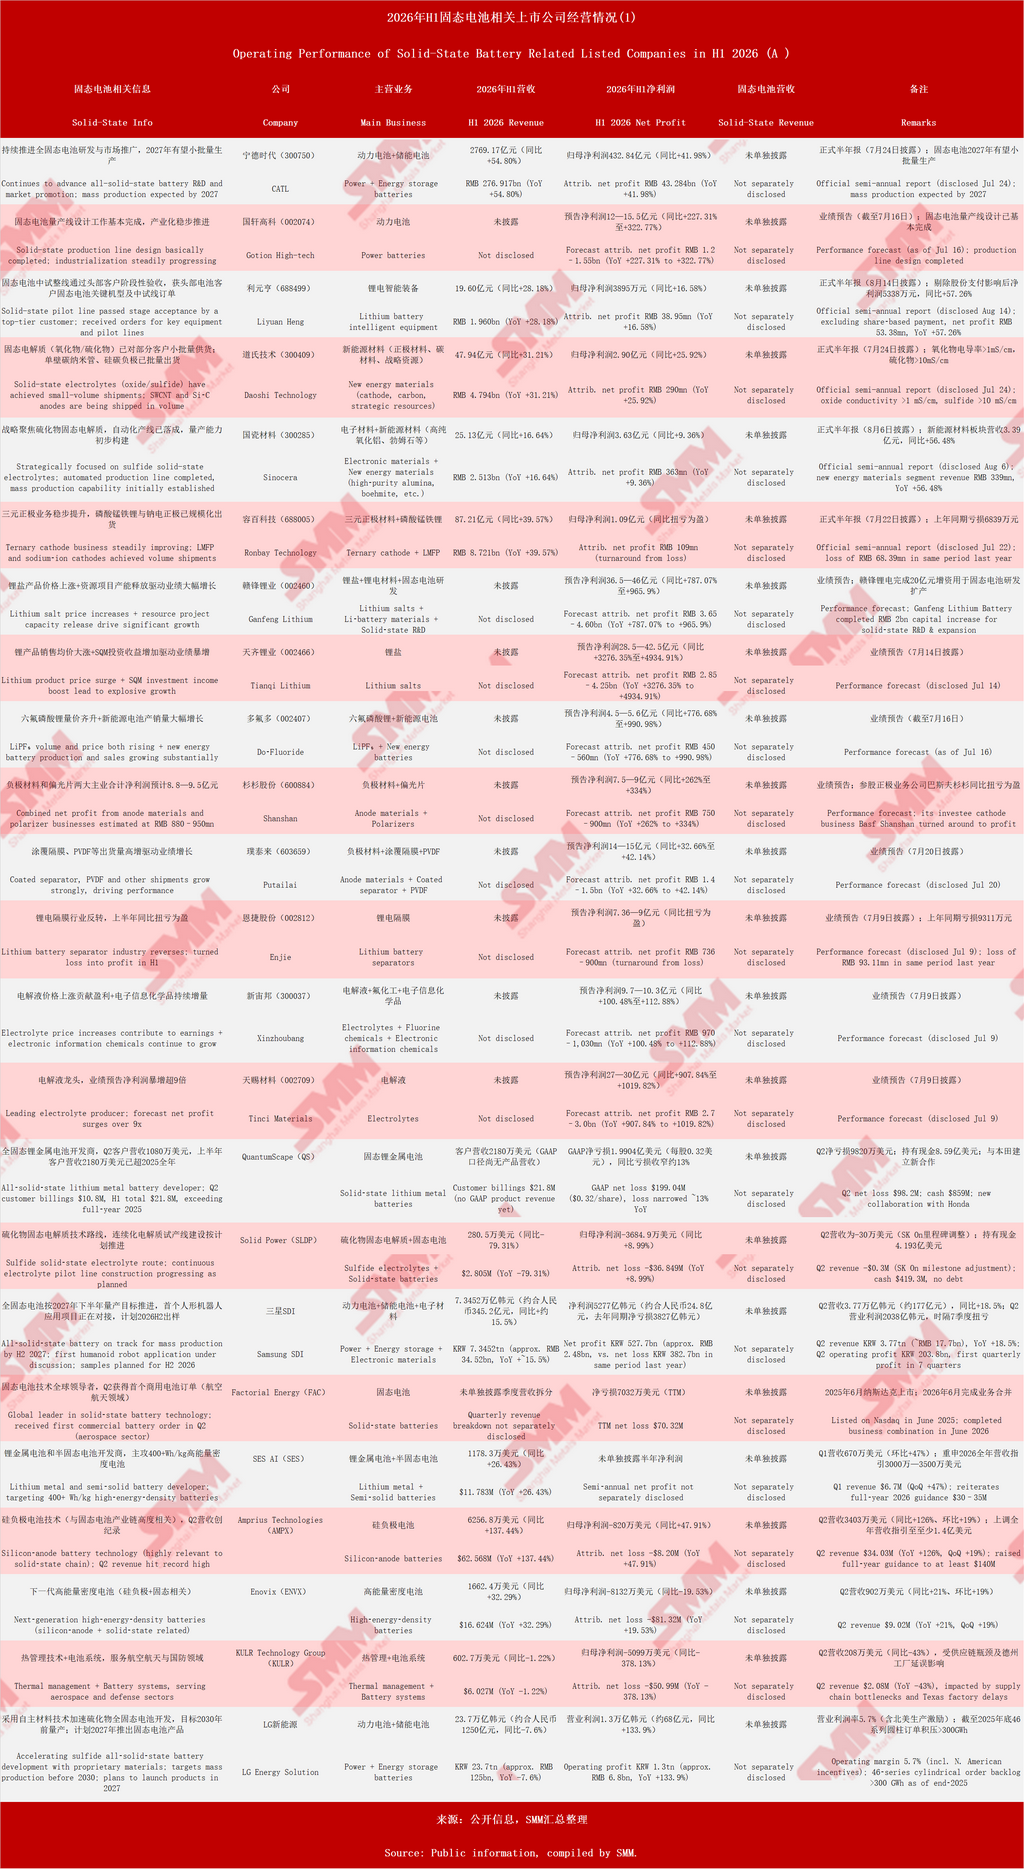
Among Chinese companies that have disclosed official semi-annual reports or performance forecasts, CATL continued its dominance with revenue of RMB 276.9 billion (+54.8%) and attributable net profit of RMB 43.3 billion (+42.0%), while steadily advancing all-solid-state R&D with mass production targeted by 2027. Gotion High-tech and Ronbay Technology also turned losses into profits or achieved high growth. Notably, the materials segment was the brightest spot: Daoshi Technology reported revenue of RMB 4.79 billion (+31.2%), with solid-state electrolytes (oxide >1 mS/cm, sulfide >10 mS/cm) already in small-volume supply, and single-wall carbon nanotubes and silicon‑carbon anodes shipping in volume. Sinocera’s new energy materials revenue surged 56.5%, and its sulfide electrolyte automated line was completed. Traditional lithium chemical players like Tinci Materials and Do‑Fluoride saw net profit multiply by several times (even tenfold) thanks to rising lithium hexafluorophosphate and electrolyte prices. Equipment maker Liyuan Heng secured solid-state battery pilot line orders from top-tier clients and passed acceptance, indicating that equipment suppliers are already benefiting from the solid-state industrialisation wave.
2. Overseas Companies: Losses and Profits Intertwined, Pre‑commercial Stage
US-based QuantumScape, though still without product revenue, achieved customer billings of $21.8M in H1, surpassing full‑year 2025, with a narrowed net loss of $199M and robust cash ($859M), alongside a new collaboration with Honda; its Eagle Line pilot line achieved >90% equipment utilization. Solid Power’s revenue declined but collaborations progressed steadily. Samsung SDI staged a comeback with H1 net profit of KRW 527.7 billion (~RMB 2.48 billion), recording its first quarterly operating profit in seven quarters in Q2, driven by surging demand for high‑power batteries (ESS/UPS/BBU) for AI data centres; it still targets all‑solid‑state mass production by H2 2027. LG Energy Solution’s operating profit soared 133.9%, with 46‑series cylindrical order backlog exceeding 300 GWh. Factorial Energy, SES AI, and Amprius, though unprofitable, secured orders in drones and aviation, with silicon‑anode and lithium‑metal technologies continuously breaking through.
3. Trends and Outlook
Overall, the solid-state battery industry has moved from “concept hype” to “substantive progress.” Material suppliers have taken the lead in partial commercialisation (electrolytes, silicon anodes, carbon nanotubes), equipment makers have received pilot orders, and battery majors have set clear mass‑production timelines. However, it must be recognised that large‑scale solid‑state revenue is yet to materialise, and most companies still rely on traditional businesses for earnings. We believe 2026‑2027 will be a critical validation period for solid‑state batteries – technological certainty and cost reduction speed will determine ultimate winners. Investors should focus on companies with core material patents, equipment capabilities, and deep customer ties, while remaining cautious about over‑valuation risks.

**Note:** For further details or inquiries regarding solid-state battery development, please contact:
Phone: 021-20707860 (or WeChat: 13585549799)
Contact: Chaoxing Yang. Thank you!


 

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
National Day Holiday Solid-State Battery Industry Review: Strong Policy Push but Slow Industrial Progress [SMM Analysis]
17 hours ago
National Day Holiday Solid-State Battery Industry Review: Strong Policy Push but Slow Industrial Progress [SMM Analysis]
Read More
National Day Holiday Solid-State Battery Industry Review: Strong Policy Push but Slow Industrial Progress [SMM Analysis]
[SMM Analysis: Solid-State Battery Industry Review During the National Day Holiday: Strong Policy Push but Slow Industrial Progress] During the National Day holiday, the solid-state battery sector showed a pattern of "hot policies, slow industry." The 15th Five-Year Plan from seven ministries targets full solid-state scale-up by 2030; Guoci's sulphide production line was completed, Chunli's GWh-class polymer line began production, a 100 GWh project was signed, and outside China, Samsung SDI/EcoPro cooperation and BMW real-vehicle validation moved forward. However, materials are seeing "rising volumes and falling prices," and moving from pilot to mass production still requires 2-3 years, with cost reduction, yield, and client validation remaining the three major hurdles yet to be overcome.
17 hours ago
EcoPro BM and Samsung SDI Sign MOU to Develop Solid-State Battery Materials
Oct 06, 2026 12:30 (GMT+8)
EcoPro BM and Samsung SDI Sign MOU to Develop Solid-State Battery Materials
Read More
EcoPro BM and Samsung SDI Sign MOU to Develop Solid-State Battery Materials
EcoPro BM announced on October 6 that it signed an MOU with Samsung SDI to develop materials for solid-state batteries. The collaboration covers cathode materials, cathode electrolytes and separator electrolytes. Samsung SDI will focus on battery cell development and mass-production technology, while EcoPro BM will develop core materials. The companies will cooperate on development, quality assessment and production readiness, targeting commercialisation of sulfide-based solid-state batteries in 2027.
Oct 06, 2026 12:30 (GMT+8)
Solid-State Battery Next Decade Series, Part 7 of 9: Global Competitive Landscape—The "Patent Shadow War" and Industrialisation Race Among China, Japan and South Korea [SMM Analysis]
Oct 05, 2026 08:59 (GMT+8)
Solid-State Battery Next Decade Series, Part 7 of 9: Global Competitive Landscape—The "Patent Shadow War" and Industrialisation Race Among China, Japan and South Korea [SMM Analysis]
Read More
Solid-State Battery Next Decade Series, Part 7 of 9: Global Competitive Landscape—The "Patent Shadow War" and Industrialisation Race Among China, Japan and South Korea [SMM Analysis]
[SMM Analysis: Solid-State Battery Next Decade Series, 7 of 9: Global Competitive Landscape—The "Patent Shadow War" and Industrialisation Race Among China, Japan, and South Korea] Is the development of global solid-state batteries measured by patents, determining the endpoint of each country's technological route? Currently, the global competition features China leading in quantity, while Japan and South Korea hold key patent positions. China is pursuing a dual-track approach, with solid-liquid batteries already in mass production and all-solid-state batteries catching up; Japan is doubling down on sulphide, South Korea is targeting dual markets, and Europe and the US are adopting technology imports plus local manufacturing. 2027-2028 is a critical window, with patents, industrialisation speed, and lithium sulphide capacity deciding the outcome.
Oct 05, 2026 08:59 (GMT+8)

