2026 H1 Antimony Market Trend Overview — Darkness Before Dawn or the Abyss of Endless Decline?

Published: Jul 13, 2026 14:03 (GMT+8)

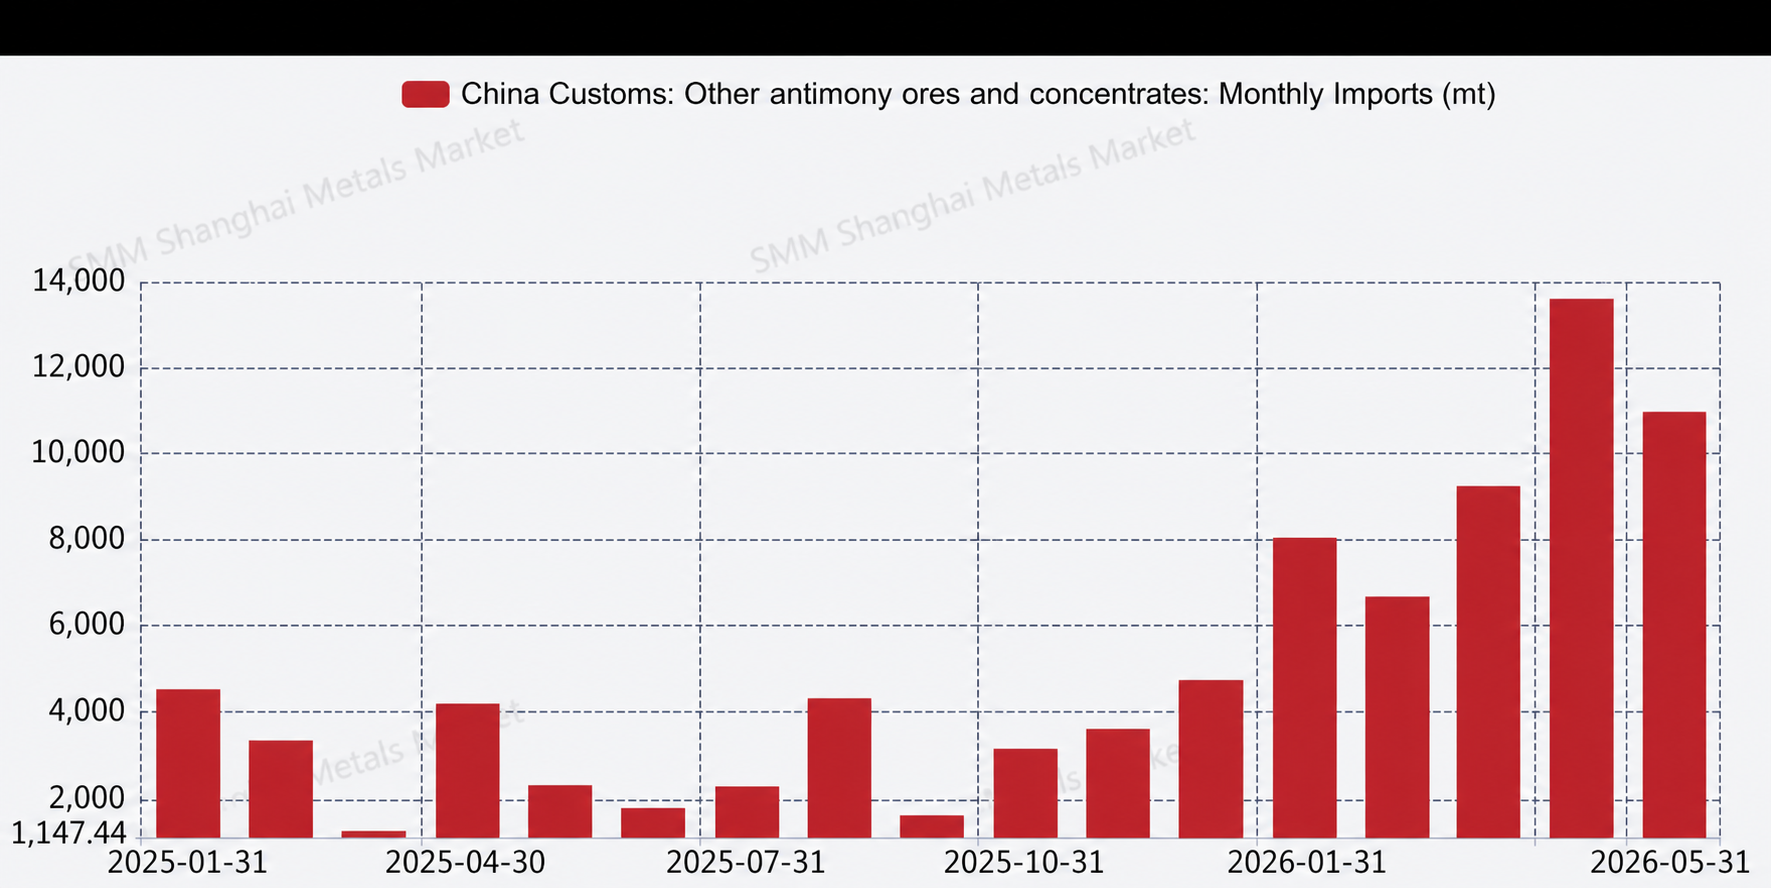
In H1 2026, the antimony market was generally weak and underwent a sustained sharp decline. During H1, cumulative antimony production from January to June was slightly lower than the same period last year, down around 8% YoY; however, imports of other antimony ores and concentrates from January to May amounted to about 48,658 mt, surging 209% YoY. A large volume of antimony raw materials entered China, which will gradually be converted into production supply in the coming period, and as a result, it is expected that the likelihood of higher domestic production in the months ahead may be amplified. Taking domestic #1 antimony ingot as an example, the average spot price is currently about 110,000 yuan/mt, a steep drop of roughly 50,000 yuan/mt from the spot price at the beginning of the year.
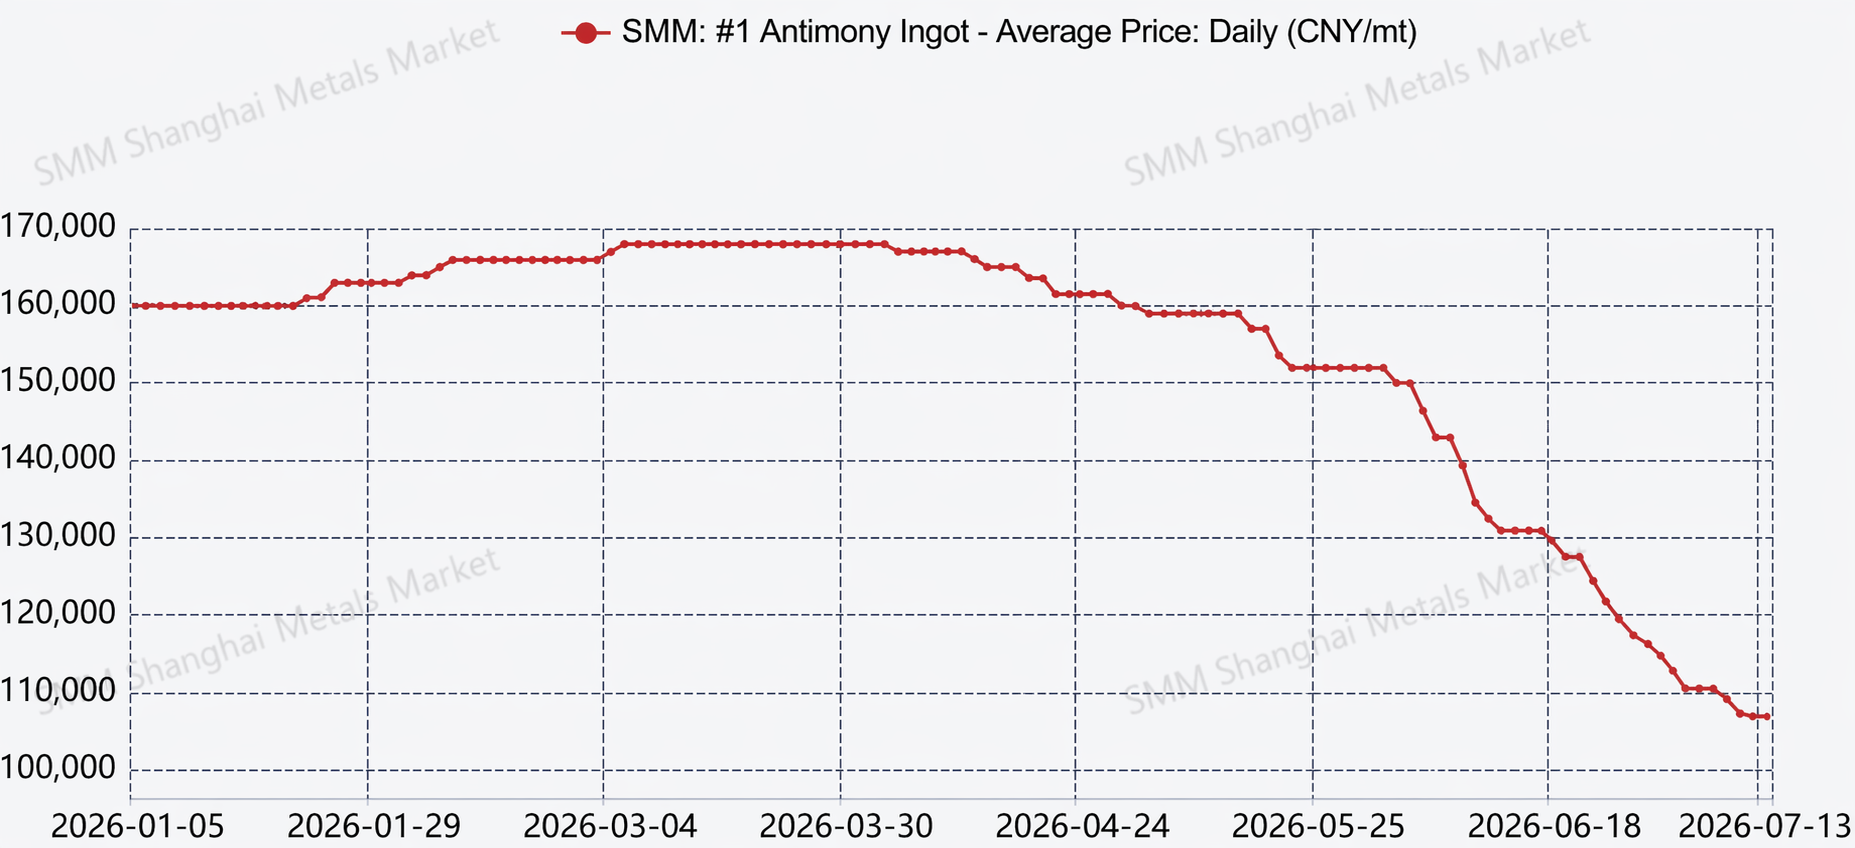
  Supply side, production has not changed much, mainly because the industry's operating rate situation has not shifted significantly. Some enterprises facing tight antimony resources have continued to maintain low operating rates or remain shut down. Over the past six months, as prices kept trending lower, the risk of buying high-priced raw materials and selling products at low prices may arise, further reducing these producers' appetite for buying antimony raw materials and making it difficult for operating rates to improve. Demand side, downstream major consumption sectors such as the flame retardant industry and PV glass industry continued to show mediocre stockpiling sentiment and sluggish buying interest. The main reasons were, on one hand, reduced order volumes due to the relatively sluggish conditions of these industries themselves; more importantly, under the persistent expectation of weak antimony prices, end-user purchases were always made on a hand-to-mouth basis, anticipating further price declines, and a mentality of delaying stockpiling as long as possible prevailed. Meanwhile, speculative forces that were previously active in the market also showed a loss of confidence and temporarily withdrew to the sidelines. On the import and export front, mainly affected by narrowing overseas price spreads, imported antimony ore began to flow into the Chinese market to be monetized quickly. The main import source countries were Southeast Asian nations such as Myanmar and Thailand.
  Looking ahead to H2, full-year production is expected to exceed 80,000 mt, up more than 5% YoY. If antimony prices manage to stop falling, stabilize, and rebound in H2, the full-year average price is expected to be around 140,000 yuan/mt. Close attention should be paid to trends in imported antimony ore, demand-side variables, and potential policy changes regarding exports that may impact the market. In addition, if antimony market prices stabilize and rebound, with current prices having returned to the low platform near levels from three years ago, special attention should be given to the impact of speculative stockpiling purchases on antimony market prices.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Antimony Market Declines, 1# Ingots Drop Below RMB 100,000/ton Post-Holiday Trading Week
Oct 16, 2026 15:05 (GMT+8)
Antimony Market Declines, 1# Ingots Drop Below RMB 100,000/ton Post-Holiday Trading Week
Read More
Antimony Market Declines, 1# Ingots Drop Below RMB 100,000/ton Post-Holiday Trading Week
The first full trading week after the holiday witnessed the antimony market break out of its one‑plus‑month high-level sideways consolidation, with quotes for all products falling across the board. On October 12 (Monday), prices of all grades were broadly cut by RMB 3,000–4,000 per ton. The downward trend accelerated on the 13th, as 1# antimony ingot dipped below the RMB 100,000/ton threshold to RMB 98,000/ton. From October 14 to 15, 1# antimony ingot briefly stabilized around the RMB 95,000/ton level. Prices moved lower again on the 16th, with 1# antimony ingot closing at RMB 92,000/ton and 0# antimony ingot at RMB 94,000/ton.
Oct 16, 2026 15:05 (GMT+8)
Antimony Prices Drop Across the Board [SMM Antimony Market Spot Weekly Review]
Oct 16, 2026 14:28 (GMT+8)
Antimony Prices Drop Across the Board [SMM Antimony Market Spot Weekly Review]
Read More
Antimony Prices Drop Across the Board [SMM Antimony Market Spot Weekly Review]
Oct 16, 2026 14:28 (GMT+8)
China's Sodium Pyroantimonate Output to Drop 25% in Sept 2026 Amid Weak Demand
Oct 10, 2026 13:56 (GMT+8)
China's Sodium Pyroantimonate Output to Drop 25% in Sept 2026 Amid Weak Demand
Read More
China's Sodium Pyroantimonate Output to Drop 25% in Sept 2026 Amid Weak Demand
According to SMM estimates, China’s output of first-grade sodium pyroantimonate in September 2026 is expected to drop by approximately 25% month-on-month. The sharp fall in September output came as a surprise to many market participants, as the traditional peak season of "Golden September and Silver October" failed to materialize. In the short term, demand for antimony from the photovoltaic sector is unlikely to improve. The scenario of weak supply alongside weak demand will persist for some time.
Oct 10, 2026 13:56 (GMT+8)

