Lithium Carbonate Price Outlook from Current Declines

Published: Apr 01, 2022 10:09 (GMT+8)
From July 20, 2021 to March 29, 2022, battery-grade lithium carbonate prices have achieved nearly nine months of continuous gains. On March 30, the average price of battery-grade lithium carbonate dropped for the first time this year, down 1,000 yuan/mt compared to the low on March 29.

SHANGHAI, Apr 1 (SMM) - From July 20, 2021 to March 29, 2022, battery-grade lithium carbonate prices have achieved nearly nine months of continuous gains. On March 30, the average price of battery-grade lithium carbonate dropped for the first time this year, down 1,000 yuan/mt compared to the low on March 29, and stood high as a whole. And the overall average price fell 500 yuan/mt. The reasons behind the decline include more uncertainties at the terminal end, easing supply tightness, and sentiment to sell off. The tug-of-war across the entire industry chain has kept fulling down the bottom line, and the transaction range has expanded.

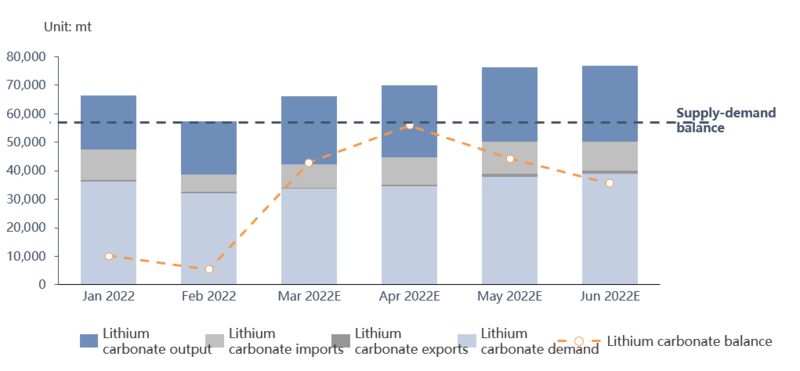
At this stage, the overall production of lithium salt plants has been normal entering March. And coupled with a rebound in brine lake output, the overall output in March rose significantly compared to February. At the same time, considering additional supply from imports, lithium carbonate supply climbed palpably. On the demand side, the second quarter is the traditional seasonal low for car sales, and the sales of some models has been halted due to cost pressure. What’s more, the broad price adjustment of the models has brought great uncertainties to future car sales. Although the car companies are currently making no significant changes to the battery orders, but it is still accompanied by a certain downside risk.

When it comes to the upstream battery sector, the in-plant battery stocks of battery manufacturers have already been high in January and February. And taking into account the possibility of falling battery orders from car companies, some battery companies choose to reduce their finished products and raw material inventories, as well as cathode material outsourcing, and stand wait-and-see. And when it goes even upward to cathode active materials (CAMs) sector, as the orders for April have basically been settled, the CAM orders may be flat or drop slightly. And as more and more material factories receive toll manufacturing orders, their demand for lithium salt will decrease.

In terms of supply and demand, the overall lithium salt supply and demand gap has been gradually narrowing since February, and the gas will be around 70 mt in April. As procurement urgency declines, and the downstream will have a say in pricing. However, the mainstream large plants still hold firm to their offers at 500,000-510,000 yuan/mt, while small ones may be willing to lower the quotations slightly. Nonetheless, the traders continue to force down the prices, and some materials factories are also selling off. As the price bottom line drops even lower, the overall market price range expands. The prices are expected to remain stable in the near future, accompanied by the risk of a small correction.

Looking forward, from the supply and demand side, the supply from spodumene will be limited for lack of ore, while that from mica will stabilise. As such, supplies from brine lake and imports will become the core driver of growth, but with limited upside potential. On the demand side, after the nickel price storm and terminal price hike, the outlook of car sales have turned promising again. And the material side will see rising orders. The supply shortage is expected to re-appear in May and June, which will offer momentum for lithium carbonate prices.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Vulcan Begins VULSORB Production for 24,000 mt/yr Lionheart Lithium Project in Germany, Targets 2028 Launch
9 hours ago
Vulcan Begins VULSORB Production for 24,000 mt/yr Lionheart Lithium Project in Germany, Targets 2028 Launch
Read More
Vulcan Begins VULSORB Production for 24,000 mt/yr Lionheart Lithium Project in Germany, Targets 2028 Launch
Vulcan has started commercial-scale production of VULSORB, its proprietary adsorbent that selectively captures lithium from brine. The company will use VULSORB at its Lionheart lithium production plant, currently under construction in Germany and due for commissioning in the second half of 2028. Vulcan said VULSORB has completed thousands of operating cycles under real-world conditions, achieving lithium extraction efficiency of up to 95%. The adsorbent is aluminate-based, and Vulcan holds both the formulation and the manufacturing method. Vulcan noted that China, the largest global provider of adsorption-type direct lithium extraction (DLE) technology and products, placed export controls and strict licensing arrangements on overseas shipments in early 2025. Lionheart targets annual production of 24,000 mt of lithium hydroxide monohydrate over an estimated 30-year project life. Vulcan will focus on manufacturing VULSORB over the next 18-24 months ahead of Lionheart's commissioning and can license the technology globally through its VULTEC technology arm.
9 hours ago
Anson Resources Inks MoU for 2,000-6,000 mtpa Lithium Carbonate Offtake from Utah's Green River Project
9 hours ago
Anson Resources Inks MoU for 2,000-6,000 mtpa Lithium Carbonate Offtake from Utah's Green River Project
Read More
Anson Resources Inks MoU for 2,000-6,000 mtpa Lithium Carbonate Offtake from Utah's Green River Project
Anson Resources has signed an MoU with metals trader Wogen Resources and financing adviser Xcelsior Capital Advisors to evaluate a long-term offtake of 2,000-6,000 mtpa of lithium carbonate equivalent (LCE) from its Green River lithium project in Utah, US. The proposed initial offtake term is five years, with scope for larger volumes and a longer term. Xcelsior may evaluate investment or financing support for the project, including debt, product prepayment and strategic investment. Anson expects Green River to start production in 2029/30, subject to development, financing, permitting, construction and commissioning. Under the MoU, the parties will review technical information and representative product samples, conduct lithium carbonate product testing and qualification, evaluate logistics, infrastructure and delivered-product costs, assess financing structures, and negotiate one or more definitive agreements.
9 hours ago
[SMM News] Argosy Minerals Completes Rincon Crystallisation Tests, Lithium Chloride Yield Above 99%
9 hours ago
[SMM News] Argosy Minerals Completes Rincon Crystallisation Tests, Lithium Chloride Yield Above 99%
Read More
[SMM News] Argosy Minerals Completes Rincon Crystallisation Tests, Lithium Chloride Yield Above 99%
[SMM News] Argosy Minerals Completes Rincon Crystallisation Tests, Lithium Chloride Yield Above 99%
On the 21st of September, Argosy Minerals completed crystallization test work for its Rincon Lithium Project in Salta Province, Argentina, which has a planned capacity of 12,000 mtpa. The tests showed the process is designed to achieve a lithium chloride yield above 99%. An independent European technology provider ran laboratory scale continuous, semi continuous and discontinuous tests using lithium brine from Argosy's earlier solvent extraction pilot campaign. The tests covered evaporation crystallization and solid liquid separation, with a focus on impurity rejection and product specification. Product quality met proposed specification, and the process route of pre concentration, sodium hydroxide treatment, solid-liquid separation and evaporation crystallization can produce specification-grade anhydrous lithium chloride. The technology provider will use the data to complete the feasibility basic engineering package for the crystallization unit, scheduled for October 2026. Finalizing the Definitive Feasibility Study (DFS) still requires each major unit operation to be validated through laboratory and pilot scale testing, so Rincon's planned 12,000 mtpa capacity has not yet moved to the construction stage. Argosy holds a 77.5% interest in Rincon and 100% of the Tonopah Lithium Project in Nevada, US.
9 hours ago