Manganese Ore Prices Rose Palpably MoM in Feb

Published: Mar 16, 2022 15:35
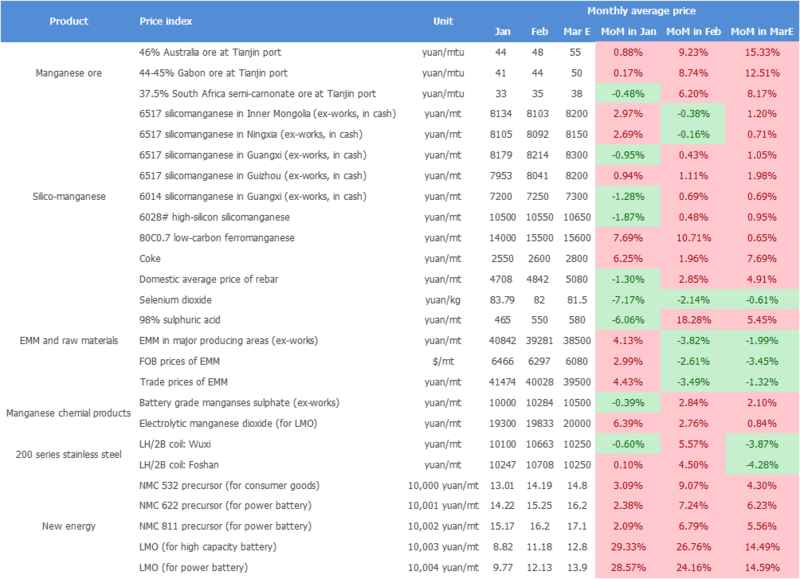
Mainstream quotations of imported manganese ore rose sharply in February, especially manganese oxide ore. Among them, the prices of Australia ore increased 9.23% month-on-month (MoM), Gabon ore rose 8.74% MoM, and South Africa semi-carbonate core added 6.20% MoM.

SHANGHAI, Mar 16 (SMM) - Mainstream quotations of imported manganese ore rose sharply in February, especially manganese oxide ore. Among them, the prices of Australia ore increased 9.23% month-on-month (MoM), Gabon ore rose 8.74% MoM, and South Africa semi-carbonate core added 6.20% MoM. SMM believes that manganese ore prices may continue to rise in March, and Australia ore is expected to rise above 65 yuan/mtu in the case of strong demand and low inventory.

In February 2022, the average ex-factory price of spot EMM (major producing areas) dropped slightly by 3.82% MoM to 39,300 yuan/mt. The main reason is that the domestic manganese prices hovered at a high level ahead of the Chinese New Year (CNY), and the terminal sector was suppressed by such high prices. In addition, the overall social inventory was 70,000 to 90,000 mt more than normal level. After the CNY holiday, some manufacturers faced huge cash turnover pressure, and some spot and futures negotiations and transaction prices gradually dropped to around 38,000 yuan/mt. Some spots were even offered at a low of 36,000 yuan/mt by surrendering part of the profits. It is expected that manganese prices will drop significantly in March.

In February 2022, the average ex-factory price of battery-grade manganese sulphate rose slightly by 2.84% MoM to 10,284 yuan/mt, and the purchasing prices of manganese ore at domestic ports also experienced continuous gains. For manganese sulphate manufacturers, in addition to the increase in cost compared with January, the operating rates in February also dropped from a month ago. In other words, falling supply and rising cost are undoubtedly bullish factors for manganese sulphate prices in this March.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Analysis] Stronger Profits, Yet Limited Supply Elasticity: H1 2026 Americas Molybdenum Mine Review
Sep 12, 2026 00:05
[SMM Analysis] Stronger Profits, Yet Limited Supply Elasticity: H1 2026 Americas Molybdenum Mine Review
Read More
[SMM Analysis] Stronger Profits, Yet Limited Supply Elasticity: H1 2026 Americas Molybdenum Mine Review
[SMM Analysis] Stronger Profits, Yet Limited Supply Elasticity: H1 2026 Americas Molybdenum Mine Review
In H1 2026, Americas moly supply divergence deepened. Despite stronger mining profits, overall output failed to rebound. While H2 may see recoveries at select large mines, supply elasticity remains constrained. Which operations are dragging on supply, and where will incremental growth emerge? SMM data reveals a market entering a new phase of "stronger margins, diverging production, and concentrated incremental gains."...
Sep 12, 2026 00:05
[SMM Chromium Week Review] Chrome Ore Flows Rebound as China Port Stocks Build, Zimbabwe Eyes Ferrochrome Capacity
Sep 11, 2026 20:21
[SMM Chromium Week Review] Chrome Ore Flows Rebound as China Port Stocks Build, Zimbabwe Eyes Ferrochrome Capacity
Read More
[SMM Chromium Week Review] Chrome Ore Flows Rebound as China Port Stocks Build, Zimbabwe Eyes Ferrochrome Capacity
[SMM Chromium Week Review] Chrome Ore Flows Rebound as China Port Stocks Build, Zimbabwe Eyes Ferrochrome Capacity
September 11, 2026.
Sep 11, 2026 20:21
[SMM Chromium Flash] Tharisa's Underground Transition at Its Chrome-PGM Flagship Mine Remains on Track
Sep 11, 2026 20:12
[SMM Chromium Flash] Tharisa's Underground Transition at Its Chrome-PGM Flagship Mine Remains on Track
Read More
[SMM Chromium Flash] Tharisa's Underground Transition at Its Chrome-PGM Flagship Mine Remains on Track
[SMM Chromium Flash] Tharisa's Underground Transition at Its Chrome-PGM Flagship Mine Remains on Track
Tharisa confirmed its transition to underground mining at its flagship Tharisa Mine, on the southwestern limb of South Africa's Bushveld Complex, remains on time and within budget, running in parallel with the Karo Platinum Project's construction financing in Zimbabwe. Development of the Apollo underground complex, which commenced in March 2026, is progressing toward first run-of-mine ore in the current quarter, with steady-state production of 255,000 mt per month targeted by the third quarter of calendar year 2029. The Orion complex is expected to follow, targeting first ore in financial year 2031 and steady-state production by the third quarter of calendar year 2033. Together, Tharisa said the two underground complexes are expected to extend mining at the Tharisa Mine, which co-produces chrome concentrate alongside PGMs from the same orebody, for more than 60 years beyond depletion of the current open pit. The underground project is fully funded through development loans from Absa and Standard Bank and an asset-based revolving facility from Nedbank, funding that sits separately from the US$300 million Nordic bond raised this week for Karo. The company did not break out what share of Apollo or Orion's future run-of-mine ore output will be chrome-bearing material versus PGM-bearing material, leaving the underground transition's specific impact on Tharisa's chrome concentrate volumes still to be clarified as the two complexes ramp up toward steady state.
Sep 11, 2026 20:12


