

News
Exclusive analysis articles with the latest market updates, and real-time news feeds.
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
In August 2026, China's total monthly sulphur imports were 272,323.414 mt in physical content, down 29.34% MoM and down 65.03% YoY, with the main import sources being the UAE, South Korea, Canada, Japan, Kazakhstan, Vietnam, Singapore, and the Philippines. China's total monthly sulphur exports were 48 mt in physical content, down 96.34% MoM and up 26.32% YoY, with the main export destinations being Indonesia and South Korea. China's total monthly sulphuric acid imports were 9,938.436 mt in physical content, up 831.85% MoM and up 1,051.37% YoY, with the main import sources being South Korea, Taiwan, China, Germany, and the US. China's total monthly sulphuric acid exports were 2,474.46 mt in physical content, up 153.47% MoM and down 99.43% YoY, with the main export destinations being Angola, Ghana, Cambodia, Hong Kong, China, Vietnam, Singapore, Malaysia, and Tanzania. China Sulfur Imports China Sulfuric Acid Exports
Sep 20, 2026 11:07 (GMT+8)
DRC Establishes US-DRC Special Working Group to Accelerate Strategic Minerals Partnership
According to foreign media reports, Kinshasa, September 11 — The DRC Cabinet approved the establishment of a DRC-US working group to accelerate the implementation of the bilateral strategic minerals partnership agreement and attract Western investment into the country's copper and cobalt industries. The DRC is the world's largest cobalt producer and the second-largest copper producer and exporter. The two countries signed a minerals cooperation agreement last December, marking the latest move by the country to broaden financing channels and strengthen cooperation with the US. Under the current cooperation framework, Virtus Minerals has already secured US-backed mining investment and is facilitating expanded copper mine cooperation between Gecamines, Mercuria, and Glencore, helping mineral products reach Western markets. The working group was originally scheduled to launch in February this year but was delayed by administrative obstacles, and its members and key projects have not yet been disclosed. The Cabinet meeting also approved a $24.8 billion fiscal budget for 2027, a 12% increase over this year's revised spending, with infrastructure, security, and economic diversification as priority areas.
Sep 21, 2026 10:00 (GMT+8)
Goldman keeps $5,400 gold forecast intact despite Fed hike
Goldman Sachs kept its end-2027 gold forecast at $5,400 an ounce despite this week's Fed hike, saying tighter policy will slow the rally but not derail it. Gold ticked above $4,355 on Friday on a softer dollar and lower oil prices. Goldman Sachs holding its end-2027 gold forecast at $5,400 an ounce despite this week's rate hike is the more notable signal here, since it suggests the bank sees the Fed's tightening path as a headwind that slows gold's rally rather than one that reverses it. That view sits against a backdrop where higher rates would typically curb demand for a non-yielding asset by increasing the appeal of yield-bearing alternatives, yet gold has still edged higher on Friday, helped by a softer dollar and a 1% pullback in oil prices. With 16 of 18 Fed policymakers now pointing to at least one more hike this year, the near-term path for real yields remains a genuine headwind, but Goldman's unchanged long-term call implies the bank sees that pressure as manageable within its broader bullish thesis, likely underpinned by continued central bank buying and ongoing Middle East risk. --- Goldman says the Fed's hike slows gold's rally, but the bank isn't backing off its $5,400 call. Summary: Goldman Sachs kept its end-2027 gold price forecast unchanged at $5,400 per troy ounce despite this week's Federal Reserve rate hike, saying tighter policy ( Goldman ditches one and done call, now sees a second Fed hike in October ) is likely to slow bullion's rally but not derail it Gold rose slightly on Friday to trade above $4,355 an ounce, supported by a 1% fall in oil prices and a subdued US dollar The Fed raised interest rates on Wednesday and signalled further hikes ahead, with updated projections showing 16 of 18 policymakers expecting at least one more quarter-point increase by year end A weaker dollar makes dollar-priced commodities cheaper for holders of other currencies, while higher rates typically curb gold demand by boosting the appeal of yield-bearing assets Market participants remain focused on developments in the Middle East and the broader path for global monetary policy Goldman Sachs kept its end-2027 gold price forecast unchanged at $5,400 per troy ounce on Friday, even after this week's Federal Reserve rate hike, saying tighter monetary policy is likely to slow bullion's rally rather than derail it. The bank's unchanged call comes despite a backdrop that would typically weigh on gold, since higher interest rates increase the appeal of yield-bearing assets and can curb demand for a non-yielding metal, even one traditionally viewed as an inflation hedge. Gold itself ticked higher on Friday, trading above $4,355 an ounce, as lower oil prices and a subdued US dollar offered support. Oil fell around 1% on the day, while the dollar remained soft after retreating from recent highs, a combination that makes dollar-priced commodities less expensive for holders of other currencies and has provided a modest tailwind for bullion. The move comes just two days after the Fed raised interest rates on Wednesday and flagged further hikes in the months ahead. Updated quarterly economic projections showed 16 of the Fed's 18 policymakers now anticipate at least one more quarter-percentage-point increase by the end of this year, a hawkish signal that has kept real yields and the dollar in focus for gold traders. Despite that backdrop, market participants have kept a close eye on developments in the Middle East alongside the broader path for global monetary policy, with geopolitical risk continuing to provide an offsetting source of support for the metal even as the rate outlook turns less accommodative. Source: https://investinglive.com/commodities/goldman-keeps-5-400-gold-forecast-intact-despite-fed-hike/
Sep 18, 2026 15:37 (GMT+8)
Latest News
Western Australia FOB Alumina Price Reaches USD 349/tonne, Surpassing Domestic Index by 334.94 yuan/tonne
4 mins ago
August Aluminum Plate/Sheet and Strip Exports Pull Back at Narrower Pace MoM, Mexico Overtakes US as Top Destination
4 mins ago
Unions at Antofagasta's Centinela Copper Mine Call Strike Vote as Labour Talks Reach Impasse
5 mins ago
Alumina Warrants Volume Remains Unchanged at 231,500 Tonnes Across Major Regions in China
On September 23, the total registered volume of alumina warrants stood at 231,500 tonnes, flat from the previous trading day. By region, the total registered volume of alumina warrants in Shandong stood at 3,897 tonnes, flat from the previous trading day; Henan stood at 0 tonnes, flat from the previous trading day; Guangxi stood at 48,999 tonnes, flat from the previous trading day; Gansu stood at 24,868 tonnes, flat from the previous trading day; and Xinjiang stood at 153,800 tonnes, flat from the previous trading day.
9 mins ago
Pre-holiday Stockpiling Falls Short of Expectations, Magnesium Industry Chain Diverges and Runs in the Doldrums [SMM Magnesium Weekly Review]
[SMM Magnesium Weekly Review: Pre-Holiday Stockpiling Falls Short of Expectations, Magnesium Industry Chain Diverges and Runs in the Doldrums] This week, the magnesium industry chain showed a divergent and weak-stable trend. On the supply side, the large dolomite mine in Wutai, Shanxi remained shut down, tightening the supply of high-grade ore in the region. Enterprises expanded procurement channels externally, and after external supplies arrived, the overall supply pressure for dolomite eased, with quotations remaining stable. Primary magnesium producers maintained basically stable output, while inventories continued to accumulate. As the two holidays approached, some producers cut prices to recover funds, and magnesium prices hit bottom before stabilizing with support from costs. Magnesium powder and magnesium alloy followed raw material prices and ran in the doldrums, while downstream processing enterprises saw finished product inventories rise and reduced operating rates to ease shipment pressure.
11 mins ago
2026 Secondary Aluminum Alloy Enterprises Mid-Autumn Festival and National Day Holiday Survey [SMM Analysis]
[SMM Analysis: 2026 Mid-Autumn Festival and National Day Holiday Survey of Secondary Aluminum Alloy Enterprises] According to the SMM survey, during the 2026 Mid-Autumn Festival and National Day holidays, secondary aluminum alloy enterprises generally maintained continuous production or had brief shutdowns, but some enterprises extended their holiday time compared with 2025.
15 mins ago
[SMM Stainless Steel Daily Review] SS Futures Consolidate and Close Higher, Spot Cargo Transactions Weak with Prices Pulling Back
[SMM Stainless Steel Daily Review] SS futures consolidate higher, spot trading weak with offers pulling back
According to SMM on September 24, SS futures consolidated on a strong note. Although the night session weakened at one point, prices gradually recovered and strengthened after the morning open. By the close, the most-traded SS contract settled at 13,815 yuan/mt. In the spot market, as the last trading day before the Mid-Autumn Festival, most downstream end-users had already completed pre-holiday stockpiling. Combined with the weak sentiment carried over from the night session, spot inquiries and trading were sluggish in the morning, and trader offers pulled back slightly as a result.
SS futures most-traded contract. At 10:15 a.m., SS2611 was at 13,760 yuan/mt, down 95 yuan/mt from the previous trading day. Spot premiums for 304/2B in Wuxi were in the 460-810 yuan/mt range. In the spot market, the average price of Wuxi cold-rolled 201/2B coil was flat; for cold-rolled mill-edge 304/2B coil, the Wuxi average price fell 25 yuan/mt, while the Foshan average price was flat; Wuxi cold-rolled 316L/2B coil prices were flat; for hot-rolled 316L/NO.1 coil, Wuxi offers were flat; cold-rolled 430/2B coil in both Wuxi and Foshan was flat.
This week, stainless steel futures showed a pattern of rebounding from lows and consolidating in recovery, with improving macro sentiment driving the pace of futures. Earlier, under macro headwinds and sluggish demand, futures fell sharply and hit a year-to-date low of 13,290 yuan/mt. Following the US Fed's rate hike, the previously accumulated macro headwinds were largely priced in, market pessimism eased, and SS futures saw a sustained recovery and rise, overall breaking away from the prior one-sided decline...
15 mins ago
High Copper Prices Deter Buyers, Wire and Cable Demand Rebounds Amid Stockpiling
[SMM Copper Cathode Rod Flash] High copper prices and high premiums kept downstream buyers on the sidelines, with new orders pulling back notably. Only end-users in wire and cable and enamelled wire saw operating rates rebound, driven by stockpiling. Inventories: Tight spot copper cathode supply combined with pre-holiday restocking pushed raw material inventories up MoM. Downstream cargo pick-up slowed, leading to a passive increase in finished product inventories MoM.
16 mins ago
High Copper Prices and Holidays Prompt Production Cuts, SMM Predicts 10.77% Drop in Operating Rate
[SMM Copper Cathode Rod Flash] High copper prices and the dual pressure of the Mid-Autumn Festival and National Day holidays led enterprises to take holidays and cut production one after another. SMM expects the operating rate to pull back 10.77 percentage points WoW next week.
18 mins ago
Gunnison Copper's Johnson Camp Mine Achieves Commercial Production, Ramp-Up Continues
Gunnison Copper announced that its Johnson Camp Mine in Arizona achieved commercial production in September 2026, following record monthly copper cathode production in August and sustained operations above the company's required operating threshold during the first half of September.
Johnson Camp produced 1.30 million lb, or approximately 592 mt, of copper cathode in August, marking its highest monthly production since operations restarted. The mine subsequently produced another 894,767 lb, or approximately 406 mt, of copper cathode between September 1 and September 17.
Gunnison said the sustained operating performance in September supported its determination that Johnson Camp had reached commercial production. The operation is continuing to ramp up toward its nameplate production capacity of up to 25 million lb/year, equivalent to approximately 11,340 mt/year, of copper cathode.
Johnson Camp produces 99.999% pure copper cathode directly from ore mined in Arizona, with copper processed into finished cathode at the site without requiring external smelting and refining. The operation is fully funded by Nuton LLC, a Rio Tinto venture.
The achievement of commercial production follows the restart and subsequent ramp-up of Johnson Camp, while Gunnison continues to advance its larger flagship Gunnison Copper Project in Arizona.
The achievement of commercial production at Johnson Camp marks a further step in the ramp-up of US domestic copper supply. August production reached a record level since the restart, while sustained output through the first half of September supported the company's declaration of commercial production. Attention will now turn to the pace of the remaining ramp-up toward the mine's nameplate copper cathode capacity of approximately 11,340 mt/year.
19 mins ago
Smelters show little willingness to further cut TCs, awaiting post-holiday pricing results [SMM Zinc Concentrates Weekly Review]
22 mins ago
Copper Cathode Rod Producers' Operating Rates Up 4.08% WoW, Down 3.88% YoY Amid Pre-Holiday Stockpiling
22 mins ago

Jinfeng Precious Metals Materials Supports SMM in Creating the "2026 SMM Platinum Group Metals and Precious Metals Industry Chain Distribution Map"
23 mins ago
Higher freight costs drive up quotes; Shanghai spot premiums rise this week [SMM Shanghai Spot Weekly Review]
[Higher freight costs drive offers up, Shanghai premiums rise this week]: This week, average spot premiums in Shanghai rose 25 yuan/mt WoW. As of Thursday this week, mainstream domestic brands were offered at premiums of 70-80 yuan/mt against the 2610 contract, while no offers were available for the high-priced Shuangyan brand against the 2610 contract.
23 mins ago
Downstream active restocking during the Mid-Autumn Festival and National Day holiday drove spot premiums sharply higher; premiums are expected to decline next week [SMM South China copper cathode spot weekly review]
23 mins ago
Downstream purchases on demand, premiums consolidate within the week [SMM Ningbo Spot Weekly Review]
[Downstream Purchases on Demand; Spot Premiums Consolidate During the Week]: This week, spot premiums in Ningbo consolidated, with the overall average price up 25 yuan/mt WoW. As of Thursday this week, spot prices in Ningbo against the 2610 contract were quoted at a premium of 10 yuan/mt, and at a premium of 15 yuan/mt against the Shanghai premium.
24 mins ago
[SMM Steel] HRC Prices Remain Stable, with No Movement at All
[Indonesia] Currently, HRC prices remain stable at 523 USD/tonne FOB. There has been no change over the last three days, despite some steel mills having lowered their prices. Since then, there has been little or no movement in the market. At present, and possibly in the future, we need to monitor the impact of the long public holiday in China, as Chinese steel products are one of the biggest drivers of the steel market in South-East Asia. Freight costs also need to be monitored as oil prices are rising, although it is unlikely that prices will rise too sharply.
27 mins ago
[HKM Shuts Down 53-Year-Old Blast Furnace A in Duisburg, Advancing Shift to Electrometallurgy]
German steelmaker Hüttenwerke Krupp Mannesmann (HKM) has permanently shut down Blast Furnace A at its Duisburg plant, marking the start of a major transformation as German heavy industry moves toward more environmentally friendly production. HKM shut down the furnace on September 20, after it had produced cast iron continuously since 1973. The move comes against a backdrop of structural change, with HKM becoming wholly owned by the Salzgitter Group in July 2026. Blast Furnace B remains in operation for now, but the strategic plan calls for a gradual phase-out of traditional blast furnace production in favor of electrometallurgy, with Germany's largest electric arc furnace planned for the site. This follows HKM's earlier decommissioning of coke oven battery No. 2 at the same plant in September.
28 mins ago
National Building Materials Inventory Overview on September 24
Total rebar inventory this week was 571.73 mt, down 408,200 mt WoW, or -6.66% WoW, and -4.13% YoY on a lunar calendar basis. Total wire rod inventory this week was 1.2978 million mt, down 106,900 mt WoW, or -7.61% WoW, and -3.33% YoY on a lunar calendar basis.
29 mins ago
[B5Plus Group Taps Danieli for New Bar and Wire Rod Mill in Côte d'Ivoire]
Steel manufacturing and downstream industrial group B5Plus Group has selected Danieli to supply the technological equipment for a new bar and wire rod mill in Abidjan, Côte d'Ivoire. The mill will produce rebar in straight lengths from 8 to 32 mm diameter and smooth wire rod from 5.5 to 16 mm, with a capacity of 50 metric tons per hour, or 300,000 metric tons annually. All technological equipment, including the laying head and fast finishing block, will be manufactured at Danieli's headquarters workshop in Italy, with the mill operated through integrated in-house automation systems. The layout allows for future connection to a continuous casting machine, with start-up planned for Q3 2027.
29 mins ago
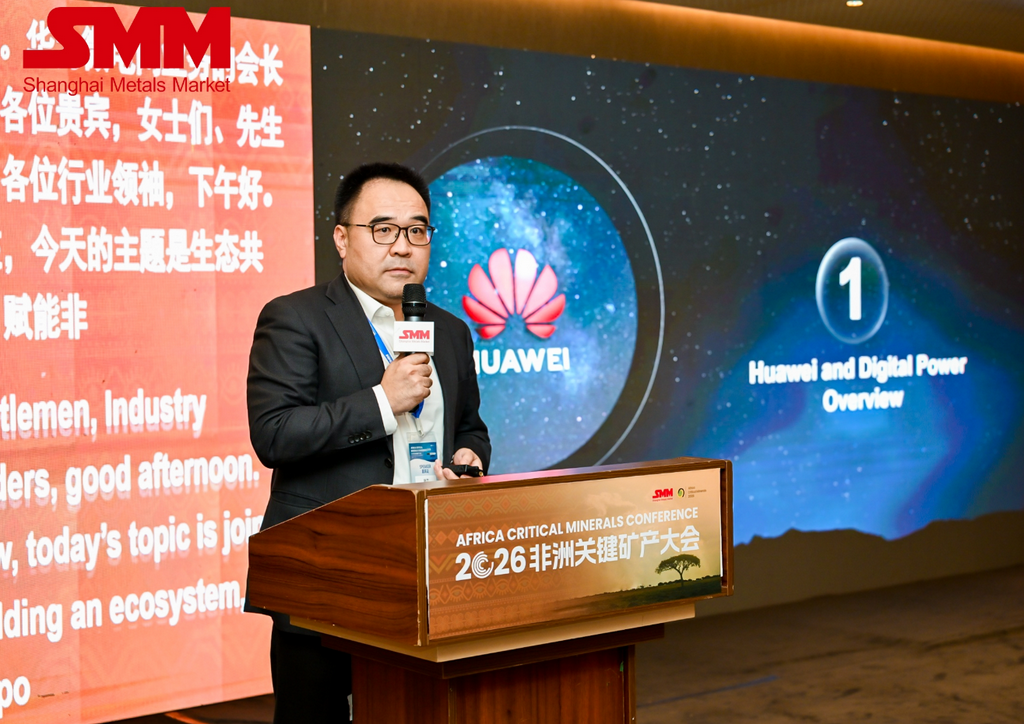
Huawei Pursues Africa Green‑Mining Partnerships and Holds Business Talks with ZESCO at SMM ACM 2026
The SMM Africa Critical Minerals Conference 2026 (ACM2026) , hosted by Shanghai Metals Market (SMM), wrapped up with great success in Lusaka, Zambia on September 15‑16. Focusing on the development of strategic minerals such as copper, cobalt, lithium, and tin in Africa, local deep-processing transformation, green mine construction and energy infrastructure upgrading, this premium event has brought together 400+ industry representatives from Chinese and African government agencies, top miners, commodity traders, investors, and technical service providers to jointly explore high-quality development paths for Africa's critical minerals industry chain. Huawei presented its mine microgrid solution at this conference. Joseph Yao, President of Mining Micro-Grid Business at Huawei Digital Power , delivered a keynote speech titled "Eco‑Partnerships for Green African Mines: Huawei's Mine Microgrid Practices under the IPP‑PPA Model". Huawei's delegation also held business talks with ZESCO, Zambia's national power utility, covering mine energy supply, new‑energy deployment and collaborative power‑infrastructure build‑out. As the global energy transition continues to advance, the new energy industry is steadily boosting demand for critical minerals such as copper and cobalt. Africa is rich in strategic mineral resources and is accelerating its upgrade from exporting mineral raw materials to a high-value-added industry chain encompassing local smelting and deep processing. Mines, as power-intensive sites, require stable and low-cost green power supply, which has become a core factor constraining the implementation of mining projects and the release of capacity in Africa. Leveraging the IPP-PPA (independent power producer investment + long-term power purchase agreement) cooperation model, distributed new energy microgrids can provide reliable power nearby for open-pit mines and smelter sites, helping mines reduce electricity costs and carbon emissions, and supporting the implementation of Zambia's strategy for local copper ore processing. (Joseph Yao, President of Mining Micro-Grid Business at Huawei Digital Power) Joseph Yao shared an overview of Huawei and its Digital Energy business, introducing Huawei as a leading provider of ICT infrastructure and smart terminals, a technology-driven enterprise with operations across many countries worldwide, focusing on core business segments such as smart PV and grid-forming ESS. He noted that Africa's mining sector is generally plagued by power shortages. High diesel costs erode mine profit margins, unstable power supplies risk production disruptions, while ESG requirements also impose constraints on mineral exports. He proposed a three-step path for the sustainable development of African mining: Firstly, supply green electricity to mines through digital energy infrastructure to reduce carbon emissions; Secondly, electrification transition of mining equipment; Thirdly, reshape production processes through AI platforms and intelligent management systems, optimize equipment scheduling, and improve mine capacity and production efficiency. He also highlighted Huawei's mine microgrid system. Rather than a standalone piece of equipment, it is a complete energy solution integrating photovoltaic‑storage systems, intelligent dispatching, diesel backup power supplies, control systems and management software. It breaks the conventional single‑power‑source model to enable energy self‑sufficiency and efficient energy management at mining sites. Citing the large‑scale microgrid project for Saudi Arabia's Red Sea Global as a case study, he explained that this city‑level microgrid achieved major technical breakthroughs underpinned by Huawei's robust in‑house R&D capabilities and power‑simulation laboratories. Huawei possesses independent R&D capacity for core power‑electronic components such as IGBTs, and delivers one‑stop services covering design, simulation and project delivery. Together with ecosystem partners, it also provides full‑lifecycle engineering consultation and on‑site implementation support. The successful delivery of this project has laid a solid foundation for microgrid deployment in mining scenarios. He specifically addressed the widespread funding pain points confronting African mining projects. Under the IPP‑PPA ecosystem model, domestic and international investors can be brought in to finance mine‑energy projects. Mining companies, as power purchasers, sign long‑term power‑purchase agreements to secure stable mine operations, while investors obtain steady returns, forming a sustainable commercial closed‑loop. In his speech, Joseph cited several African mine microgrid implementation cases. Among them, after the completion of the Kamoa-Kakula mining microgrid project in the DRC, green electricity will replace a large amount of diesel power generation, significantly reducing mine electricity costs and carbon emissions, and delivering a good return on investment. For this Chinese-funded miner's copper mine project in the DRC, microgrid upgrades sharply reduced electricity costs and significantly improved the mine's capacity utilization rate, verifying the practical value of green electricity microgrids in African mine scenarios. He summarized Huawei's three core capabilities: a globalized business platform, end-to-end one-stop microgrid solutions, and a diverse ecosystem partner system that includes investors, EPCs, and design consulting agencies. He added that Huawei is looking forward to establishing partnership with more investors to develop energy projects across Zambia and wider Africa, secure power supplies for critical‑mineral industries including copper and lithium, jointly foster green mines in Africa, and build a low‑carbon and sustainable industrial future. During the conference, the Huawei delegation held a business meeting with representatives from Zambia's national power utility ZESCO. Against the backdrop of accelerating green transformation in African mining and continuously growing power demand in mining areas, the two sides exchanged views on topics of common concern such as power infrastructure construction and new energy support, and expressed their intention to jointly explore potential areas for cooperation. Africa's mineral industry is at a critical window for industry chain upgrading. Huawei, drawing on its technological strengths in new energy and smart power, will partner with IPP investors, local power authorities and mining operators to build an open‑cooperation ecosystem. Leveraging its proven mine microgrid solutions, Huawei aims to deliver green, reliable power supplies for African mining and smelting projects, advance the low‑carbon transition of Africa’s critical minerals industry, and deepen practical China‑Africa cooperation across the mining and energy sectors.
23 hours ago
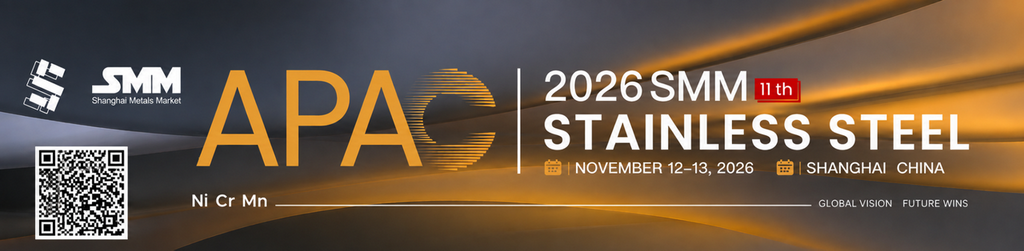
SMM to Host SMM (11th) Annual Nickel Conference 2026 - Ni Cr Mn Stainless Steel Event , Shanghai, Nov. 12–13
Sep 20, 2026 10:33 (GMT+8)
Canada Lifts Solar Trade Duties: Can Chinese Modules Win a Bigger Share? [SMM Analysis]
Sep 21, 2026 18:03 (GMT+8)
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
Sep 20, 2026 16:38 (GMT+8)
[SMM Analysis] China Sulphur and Sulphuric Acid Import and Export Data for August
Sep 20, 2026 11:07 (GMT+8)
DRC Establishes US-DRC Special Working Group to Accelerate Strategic Minerals Partnership
Sep 21, 2026 10:00 (GMT+8)

Goldman keeps $5,400 gold forecast intact despite Fed hike
Sep 18, 2026 15:37 (GMT+8)
Latest News
Western Australia FOB Alumina Price Reaches USD 349/tonne, Surpassing Domestic Index by 334.94 yuan/tonne
4 mins ago
August Aluminum Plate/Sheet and Strip Exports Pull Back at Narrower Pace MoM, Mexico Overtakes US as Top Destination
4 mins ago
Unions at Antofagasta's Centinela Copper Mine Call Strike Vote as Labour Talks Reach Impasse
5 mins ago
Alumina Warrants Volume Remains Unchanged at 231,500 Tonnes Across Major Regions in China
9 mins ago
Pre-holiday Stockpiling Falls Short of Expectations, Magnesium Industry Chain Diverges and Runs in the Doldrums [SMM Magnesium Weekly Review]
11 mins ago
2026 Secondary Aluminum Alloy Enterprises Mid-Autumn Festival and National Day Holiday Survey [SMM Analysis]
15 mins ago
[SMM Stainless Steel Daily Review] SS Futures Consolidate and Close Higher, Spot Cargo Transactions Weak with Prices Pulling Back
15 mins ago
High Copper Prices Deter Buyers, Wire and Cable Demand Rebounds Amid Stockpiling
16 mins ago
High Copper Prices and Holidays Prompt Production Cuts, SMM Predicts 10.77% Drop in Operating Rate
18 mins ago
Gunnison Copper's Johnson Camp Mine Achieves Commercial Production, Ramp-Up Continues
19 mins ago
Smelters show little willingness to further cut TCs, awaiting post-holiday pricing results [SMM Zinc Concentrates Weekly Review]
22 mins ago
Copper Cathode Rod Producers' Operating Rates Up 4.08% WoW, Down 3.88% YoY Amid Pre-Holiday Stockpiling
22 mins ago
Jinfeng Precious Metals Materials Supports SMM in Creating the "2026 SMM Platinum Group Metals and Precious Metals Industry Chain Distribution Map"
23 mins ago
Higher freight costs drive up quotes; Shanghai spot premiums rise this week [SMM Shanghai Spot Weekly Review]
23 mins ago
Downstream active restocking during the Mid-Autumn Festival and National Day holiday drove spot premiums sharply higher; premiums are expected to decline next week [SMM South China copper cathode spot weekly review]
23 mins ago
Downstream purchases on demand, premiums consolidate within the week [SMM Ningbo Spot Weekly Review]
24 mins ago
[SMM Steel] HRC Prices Remain Stable, with No Movement at All
27 mins ago
[HKM Shuts Down 53-Year-Old Blast Furnace A in Duisburg, Advancing Shift to Electrometallurgy]
28 mins ago
National Building Materials Inventory Overview on September 24
29 mins ago
[B5Plus Group Taps Danieli for New Bar and Wire Rod Mill in Côte d'Ivoire]
29 mins ago