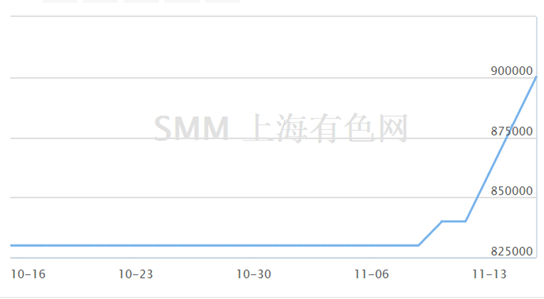
SHANGHAI, Nov.16 (SMM)-Previously, Ganfeng Lithium announced to raise price of metal lithium by 100,000 yuan per tonne. Concerning this, SMM analyst of cobalt and lithium says this action is mainly caused by two factors. One is one supplier plant has reduced production since August. The other one is rising cost of lithium slat. Currently, SMM price of metal lithium is still rising gradually, which is closed to offer of Ganfeng Lithium.
As one of the components of Li-battery, metal lithium has a good fundamentals. But concerning Li-battery concept stocks on Nov.15th, we found frustrated market on that day.
So what’s the reason of this slump of Li-battery stocks?
Market Insides says, this slump is probably related to news that the government is researching on new subsidy policy on new-energy cars, saying to bring forward 20% drop of subsidy from 2019 to 2018.
Probably caused by same news, auto stocks also slumps on Nov.15th. Up to closure, king Long Motors fell staying and FAW Car went down.
Sinolink Securities remarks on this rumor that this maybe the worst situation. Actually it should be better. Even if the rumor is true, the negative effect is far less influential than subsidy drop in 2017. Those companies having good prospect is still to be profitable with buoyant stock price.
Reasons are as follows:
Firstly, in 2017 after the subsidy dropped, the market spent quite a long time coordinating between upstream and downstream plants. It is estimated to have a much higher efficiency for this time.
Secondly, the cost of upstream plants are declining continuously with rigid demand and high price acceptance of downstream clients. Output in 2017 is expected to rise greatly compared with 2017. Gross profit rate of companies will not change a lot.
Thirdly, dropping subsidy is overall a negative news to the industry but it may lead to an intensive assembly of new-energy cars in the fourth quarter. Also, the demand of new-energy coach is expected to improve greatly next year.
Besides, Cui Dongshu, industrial analyst says, national subsidy for new-energy cars during recent years drives output of new-energy cars, especially for coach. Hence participants and capacity of new-energy cars surges greatly but technical progress is not apparent. In 2018 the core adjustment of subsidy policy is about key indicators as battery energy density and endurance mileage rather than the drop amount of subsidy. The key of new-energy cars is improvement of battery and overall design to realize high-energy-density, long life, high efficiency, low internal resistance and good conformity.
If new subsidy policy can facilitate enterprises to choose better battery and improve technical level as subsidy drops in 2018, this will be the best way to strengthen new-energy cars enterprises. Otherwise domestic new-energy cars will face fierce competition with high-level products of foreign brands.
For news cooperation, please contact us by email: gaotian@smm.cn or service.en@smm.cn.