September Price Review:
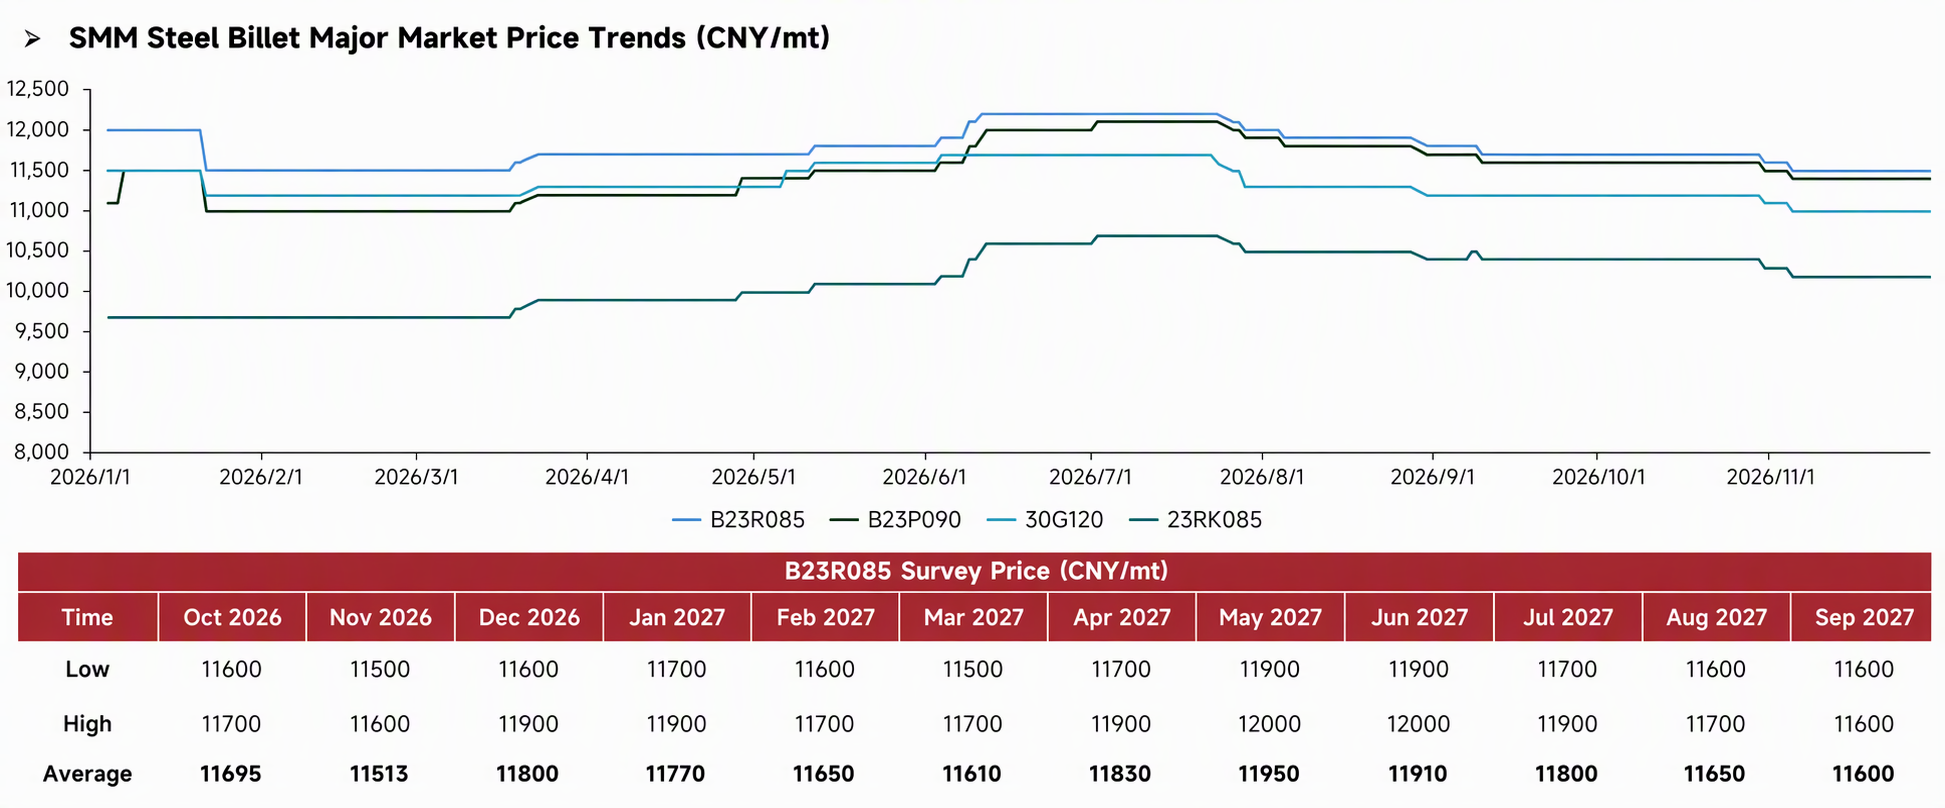
Source: SMM
In September, mainstream grades of grain-oriented silicon steel (GO silicon steel) showed a weak and stable trend, with fluctuations narrowing for grades such as B23R085, B23P090, and 30G120, and the price center holding steady. The core benchmark B23R085 saw its monthly average price move sideways, with ample supply in the market and no significant improvement in the loose supply-demand pattern, which continued to weigh on prices. Based on the price forecast curve, there was insufficient momentum for a short-term upward rebound. Overall, demand for GO silicon steel in September lacked a strong boost, as downstream transformer enterprises mostly made just-in-time procurement with cautious stockpiling sentiment, resulting in a moderate pace of market transactions, persistent wait-and-see sentiment, and a market characterized mainly by weak and stable consolidation.
Fundamental Analysis:
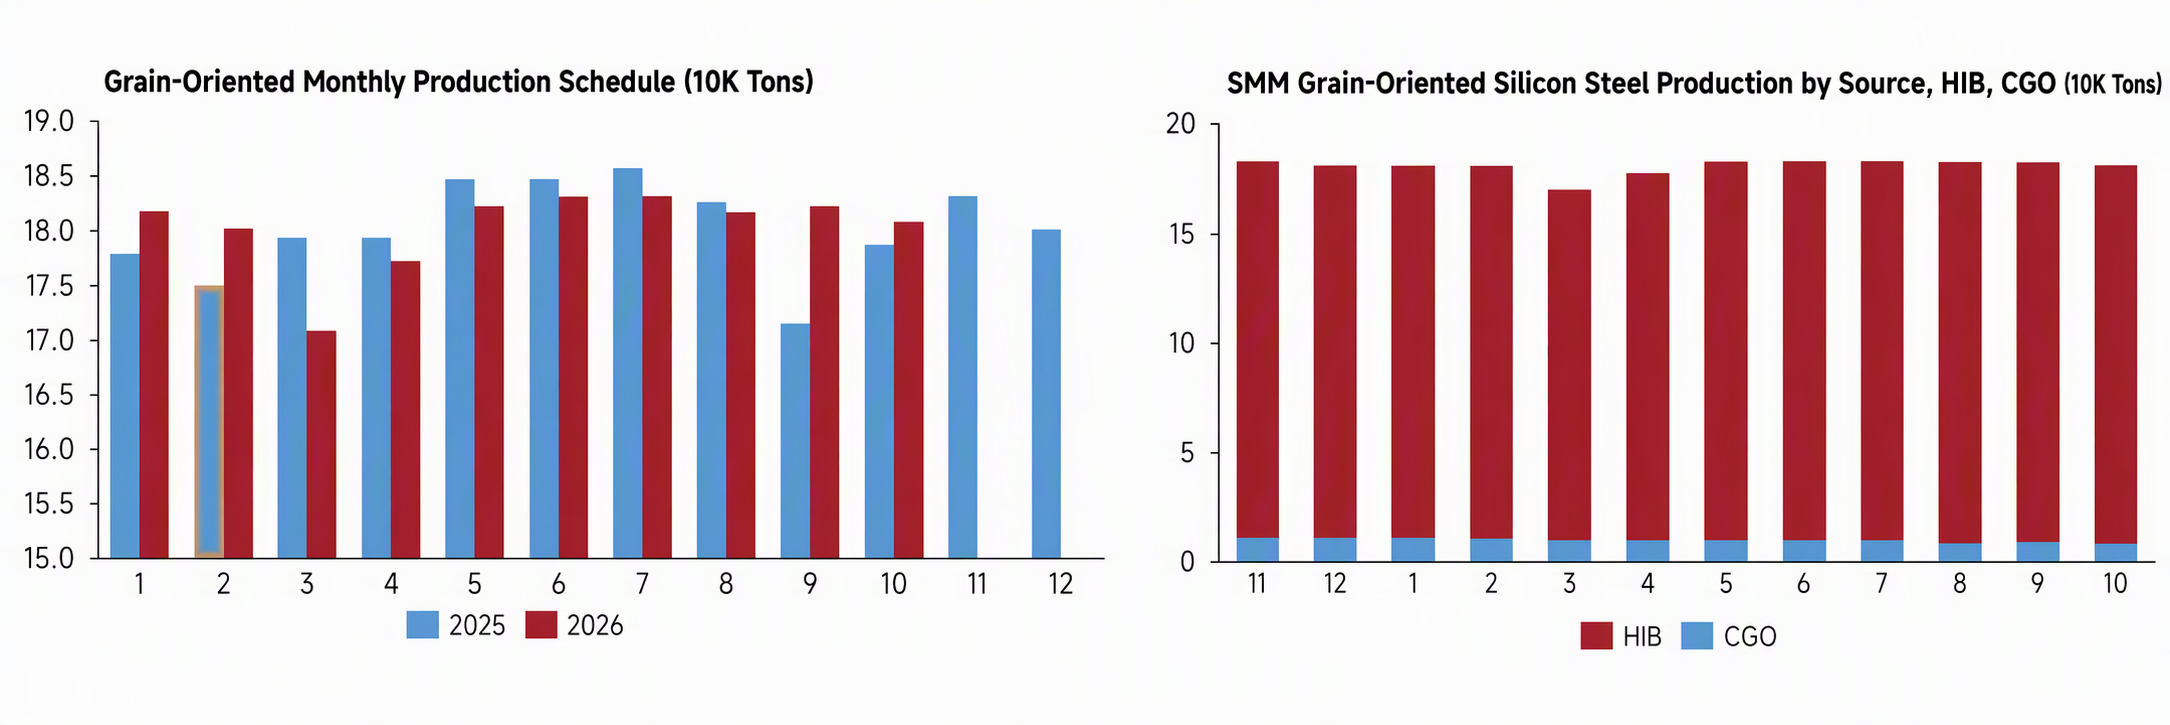
Source: SMM
In September, China's GO silicon steel production schedule edged up MoM, with steel mills raising their production plans and overall scheduled production remaining in a high range. In terms of product mix, HIB high-permeability GO silicon steel maintained its dominant position in production, while CGO conventional GO silicon steel remained at low output, as steel mills continued to shift production resources toward high-value-added HIB grades. Overall, September production schedule increased slightly, capacity deployment for HIB grades remained stable, and supply of high-permeability products was ample. New orders in the transformer industry were insufficient, downstream stocking willingness was weak, and supply growth further amplified supply pressure. With no significant contraction on the supply side, the loose supply-demand pattern was difficult to improve, exerting sustained pressure on spot prices.
In October, China's GO silicon steel production schedule pulled back slightly MoM, with steel mills moderately lowering production plans based on downstream order conditions. In terms of product mix, HIB high-permeability GO silicon steel continued to dominate output, while CGO conventional GO silicon steel output remained low, with no significant change in the production structure. Overall, in October steel mills proactively fine-tuned their production schedules, making modest production cuts to ease supply pressure, but the adjustment was limited and HIB spot inventory remained ample. Transformer enterprises saw weak order follow-through, with procurement mostly consisting of just-in-time restocking, and demand showed no notable improvement. The modest production cuts were insufficient to drive effective inventory destocking, the loose supply-demand pattern persisted, and spot market conditions lacked upward momentum.
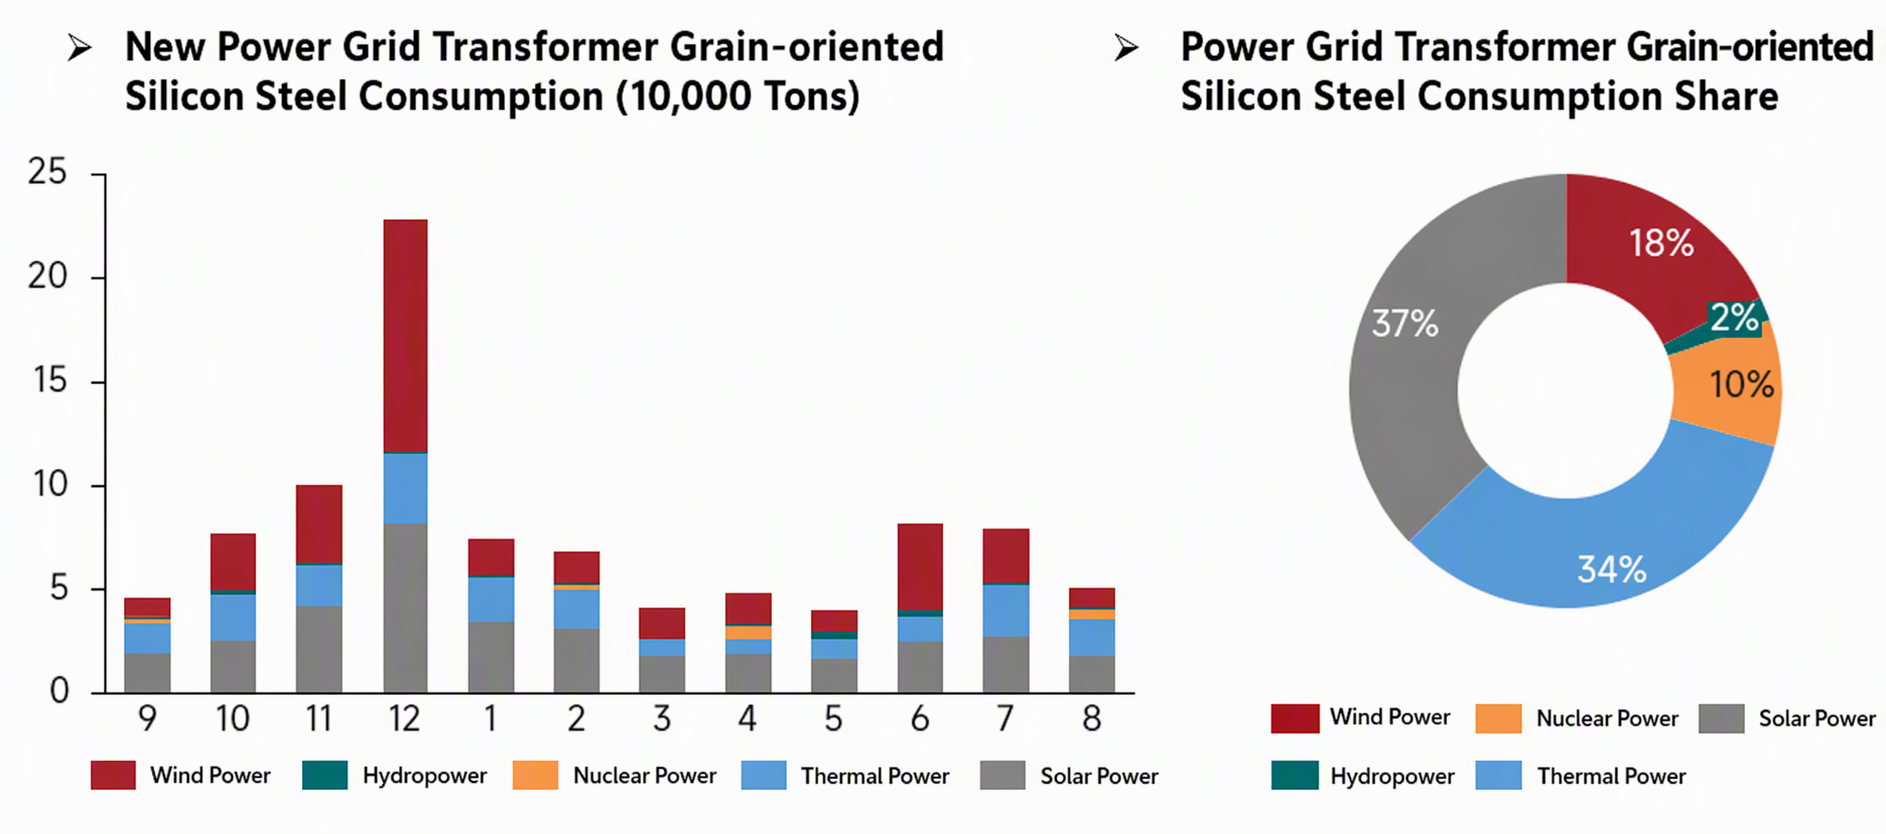
Source: Public data, SMM
In August 2026, new installations across power supply sources in the power grid continued to show a divergent pattern, with wind power and solar power remaining the core sources of demand for GO silicon steel, together accounting for the majority of total GO silicon steel consumption in the grid sector. Thermal power ranked second, while hydropower and nuclear power remained at low shares. In August, new wind power installations pulled back, while new solar installations held steady, providing only basic demand support for transformers and GO silicon steel. Growth in new installations of hydropower, thermal power, and nuclear power was weak, offering limited boost to GO silicon steel. Overall, in August, demand for grain-oriented silicon steel from the power grid still relied on wind and solar power installations as the demand base, but new installations were generally weak. Transformer manufacturers saw insufficient follow-up in new orders, and downstream continued the pattern of purchasing small orders as needed, with weak willingness to stockpile proactively. Overall demand lacked a strong boost, making it difficult to drive grain-oriented silicon steel prices upward.
October price outlook:
Looking ahead to October 2026, in terms of supply, China's total grain-oriented silicon steel production is expected to decline slightly. Mainstream state-owned steel mills will maintain normal production on their lines, with operating rates basically unchanged. High-end grades will be released in an orderly manner, while ordinary grades will remain in ample supply. On the demand side, China's "15th Five-Year Plan" ultra-high voltage projects continue to advance. In October, State Grid and China Southern Power Grid will continue to fulfill earlier tender orders. Downstream will shift from proactive stockpiling to purchasing as needed, with rigid demand support still present, but new purchasing momentum will weaken. In addition, the EU's new provisional safeguard measures on Chinese grain-oriented silicon steel will cause export cargoes to continue flowing back into the domestic market, impacting the market. On the cost side, the October hot-rolled coil market lacks a trending one-sided driver and is overall expected to maintain a weak consolidating pattern. Subsequent focus will be on post-holiday steel mill production cut pace, post-holiday end-user transaction recovery, and the latest policy developments. In summary, SMM expects grain-oriented silicon steel prices in October 2026 to remain in a consolidating and stable range overall, with insufficient momentum for either rise or fall.
Data source statement:
(Except for public information, all other data in this report are derived from public information (including but not limited to industry news, seminars, exhibitions, corporate financial reports, broker reports, National Bureau of Statistics data, customs import and export data, and various data published by major associations and institutions), market communication, and SMM's internal database models. They are produced through comprehensive analysis and reasonable inference by the research team, and are for reference only and do not constitute decision-making advice.
Shanghai Metals Market reserves the final right of interpretation of the terms of this statement and retains the right to adjust and modify the content of the statement based on actual circumstances.