September Price Review
Source: SMM
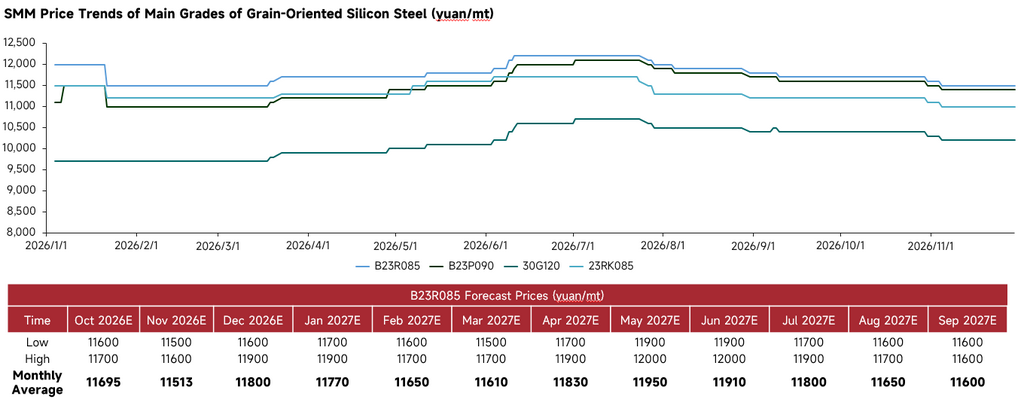
Prices of mainstream grain-oriented silicon steel grades posted a weak and stable performance in September. Price fluctuations for grades including B23R085, B23P090 and 30G120 narrowed, with price centres temporarily steady. The monthly average price of the benchmark grade B23R085 fluctuated within a range. Ample supply kept the loose supply-demand dynamic largely unchanged, continuing to cap prices. The price forecast curve indicated limited momentum for a near-term rebound. Overall, grain-oriented silicon steel lacked strong demand traction in September. Downstream transformer manufacturers mostly purchased only to meet rigid demand and remained cautious over restocking. Market trading pace was slow amid lingering wait-and-see sentiment, and the market mainly saw weak consolidation with volatility.
Fundamental Analysis
Source: SMM
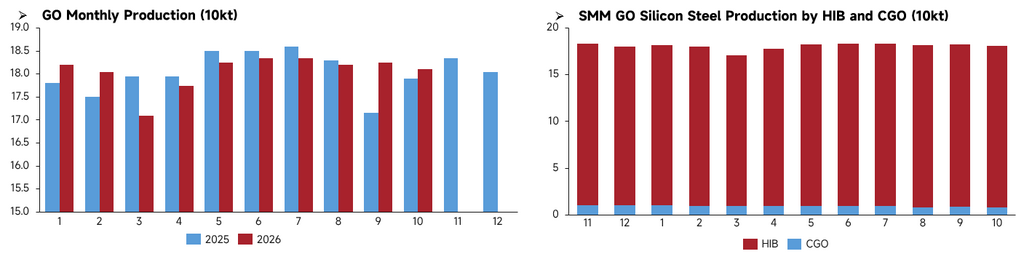
Domestic grain-oriented silicon steel production schedules edged up month-on-month in September. Steel mills raised output plans, and overall production stayed within a high range. By product mix, high-induction grain-oriented (HIB) silicon steel remained the primary output category, while conventional grain-oriented (CGO) silicon steel output stayed low. Steel mills kept channelling production resources to high-value-added HIB grades. On balance, September output rose modestly, with steady capacity release for HIB grades and sufficient supply of high-induction products. Transformer manufacturers suffered from insufficient new orders and weak inventory-building appetite. The supply increase further exacerbated supply pressure. Without a meaningful supply contraction, the loose supply-demand balance could not improve, which continuously weighed on spot prices.
Planned domestic grain-oriented silicon steel production will edge down month-on-month in October. Steel mills will moderately lower output plans in light of downstream order conditions. In terms of product structure, HIB silicon steel will still dominate output, CGO silicon steel output will remain low, and no material changes will be seen in the production mix. Overall, mills will fine-tune schedules and slightly curb output to ease supply pressure, yet the adjustment will be limited and spot inventories of HIB grades will stay ample. Transformer enterprises have seen sluggish order follow-up and mostly carry out rigid-demand restocking. Demand shows no notable improvement. The modest production cut will not drive effective inventory destocking. The loose supply-demand pattern will persist, leaving spot prices without upward momentum.
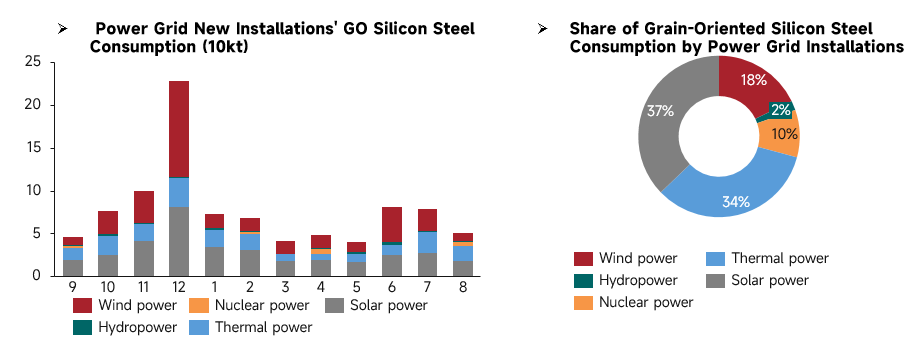
Source: Public Data, SMM
Newly installed capacity across power sources on China’s power grid continued to diverge in August 2026. Wind and solar power remained the core sources of grain-oriented silicon steel demand; together they accounted for the bulk of grid-side consumption, followed by thermal power, while hydropower and nuclear power took relatively small shares. New wind installations declined in August and new solar installations stayed flat, providing only basic demand support for transformers and grain-oriented silicon steel. Incremental installations for hydropower, thermal power and nuclear power were muted, offering limited lift to grain-oriented silicon steel consumption. Overall, grid demand for grain-oriented silicon steel in August was underpinned by wind and solar installations as the fundamental demand base. However, total new capacity additions were weak. Transformer manufacturers recorded slow new order intake, and downstream buyers stuck to small-batch, as-needed purchases with little willingness for proactive stockpiling. The absence of strong demand traction prevented grain-oriented silicon steel prices from moving higher.
October Price Outlook
Looking ahead to October 2026, on the supply side, total domestic grain-oriented silicon steel output will dip slightly. Major state-owned steel mills will maintain regular production with largely stable operating rates. High-end grades will be released in an orderly fashion and conventional grades will remain well-supplied. On the demand side, China’s 15th Five-Year ultra-high voltage (UHV) projects continue to move forward. Pre-awarded tender orders from State Grid and China Southern Power Grid will keep being fulfilled in October. Downstream buyers have shifted from proactive stockpiling to purchase-on-demand. Rigid demand support remains in place, yet incremental buying has weakened. In addition, the EU has imposed provisional safeguard measures on Chinese grain-oriented silicon steel, causing export cargoes to flow back into the domestic market and disrupting the domestic market. On the cost side, the hot rolled coil market lacks a clear directional driver in October and is expected to stay weak and range-bound. Market participants will closely track post-holiday production cuts by steel mills, the recovery of terminal spot transactions and the latest policy updates. In summary, SMM forecasts that grain-oriented silicon steel prices in October 2026 will generally oscillate and hold steady, with limited upside or downside momentum.