SHANGHAI, Apr 7(SMM) - This is a roundup of China's metals weekly inventory as of April 7.
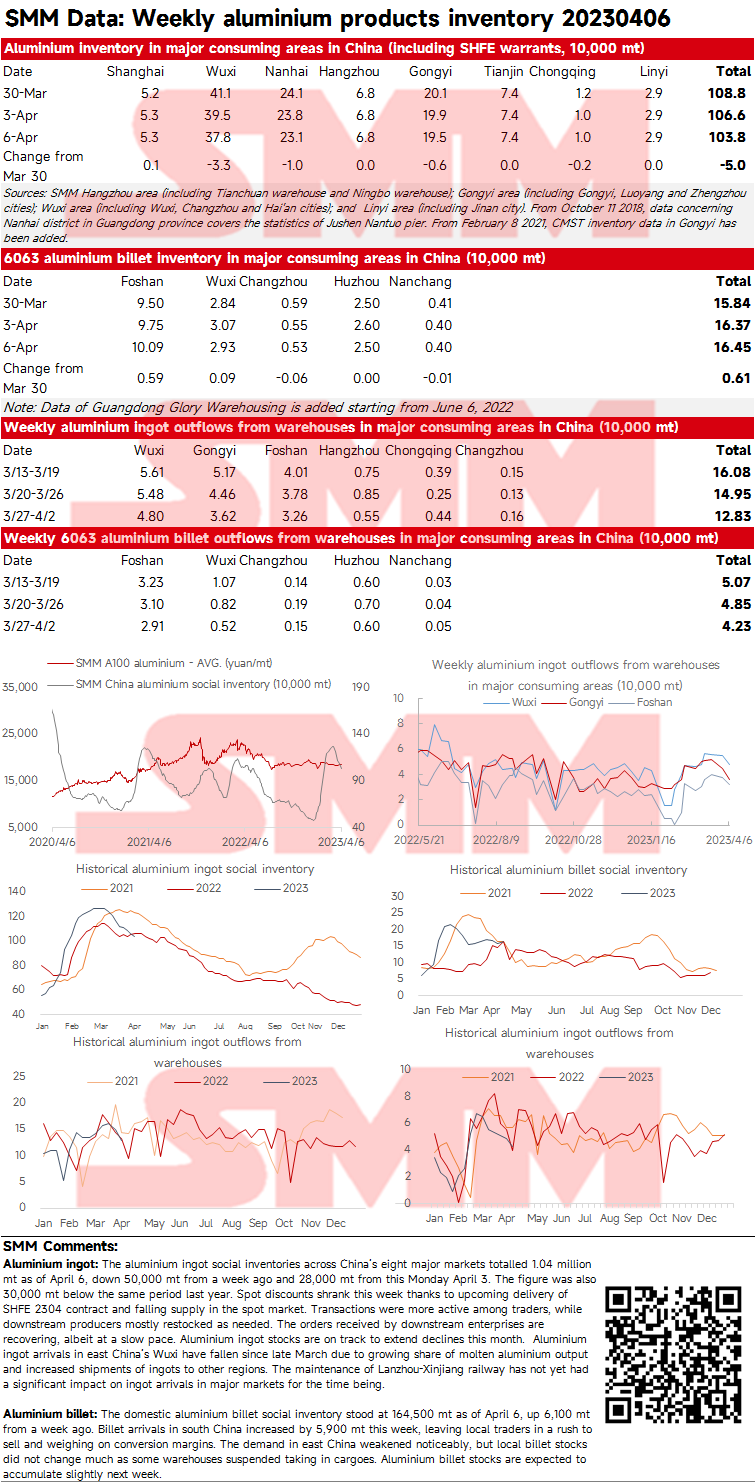
SMM Updates on China Aluminium Ingot and Billet Inventory in Week Ending April 6
Aluminium ingot: The aluminium ingot social inventories across China’s eight major markets totalled 1.04 million mt as of April 6, down 50,000 mt from a week ago and 28,000 mt from this Monday April 3. The figure was also 30,000 mt below the same period last year. Spot discounts shrank this week thanks to upcoming delivery of SHFE 2304 contract and falling supply in the spot market. Transactions were more active among traders, while downstream producers mostly restocked as needed. The orders received by downstream enterprises are recovering, albeit at a slow pace. Aluminium ingot stocks are on track to extend declines this month. Aluminium ingot arrivals in east China’s Wuxi have fallen since late March due to growing share of molten aluminium output and increased shipments of ingots to other regions. The maintenance of Lanzhou-Xinjiang railway has not yet had a significant impact on ingot arrivals in major markets for the time being.
Aluminium billet: The domestic aluminium billet social inventory stood at 164,500 mt as of April 6, up 6,100 mt from a week ago. Billet arrivals in south China increased by 5,900 mt this week, leaving local traders in a rush to sell and weighing on conversion margins. The demand in east China weakened noticeably, but local billet stocks did not change much as some warehouses suspended taking in cargoes. Aluminium billet stocks are expected to accumulate slightly next week.
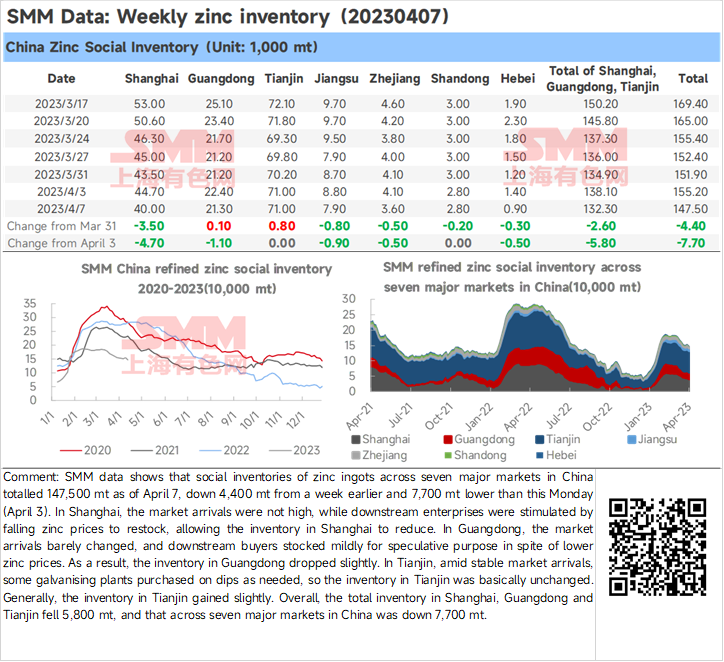
Zinc Ingot Social Inventory Down 7,700 mt from Monday
SMM data shows that social inventories of zinc ingots across seven major markets in China totalled 147,500 mt as of April 7, down 4,400 mt from a week earlier and 7,700 mt lower than this Monday (April 3).
In Shanghai, the market arrivals were not high, while downstream enterprises were stimulated by falling zinc prices to restock, allowing the inventory in Shanghai to reduce. In Guangdong, the market arrivals barely changed, and downstream buyers stocked mildly for speculative purpose in spite of lower zinc prices. As a result, the inventory in Guangdong dropped slightly. In Tianjin, amid stable market arrivals, some galvanising plants purchased on dips as needed, so the inventory in Tianjin was basically unchanged. Generally, the inventory in Tianjin gained slightly.
Overall, the total inventory in Shanghai, Guangdong and Tianjin fell 5,800 mt, and that across seven major markets in China was down 7,700 mt.
Silicon Metal Stocks Decline, Contributed by Kunming
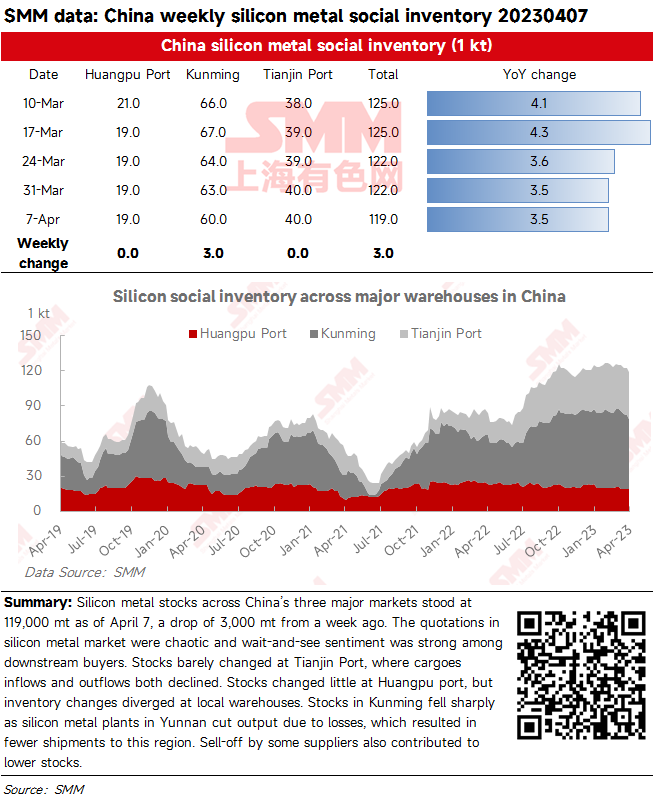
SHANGHAI, Apr 7 (SMM) – Silicon metal stocks across China’s three major markets stood at 119,000 mt as of April 7, a drop of 3,000 mt from a week ago. The quotations in silicon metal market were chaotic and wait-and-see sentiment was strong among downstream buyers. Stocks barely changed at Tianjin Port, where cargoes inflows and outflows both declined. Stocks changed little at Huangpu port, but inventory changes diverged at local warehouses. Stocks in Kunming fell sharply as silicon metal plants in Yunnan cut output due to losses, which resulted in fewer shipments to this region. Sell-off by some suppliers also contributed to lower stocks.
Social Inventory of Lead Ingot Falls Further amid Maintenance at Main Production Regions
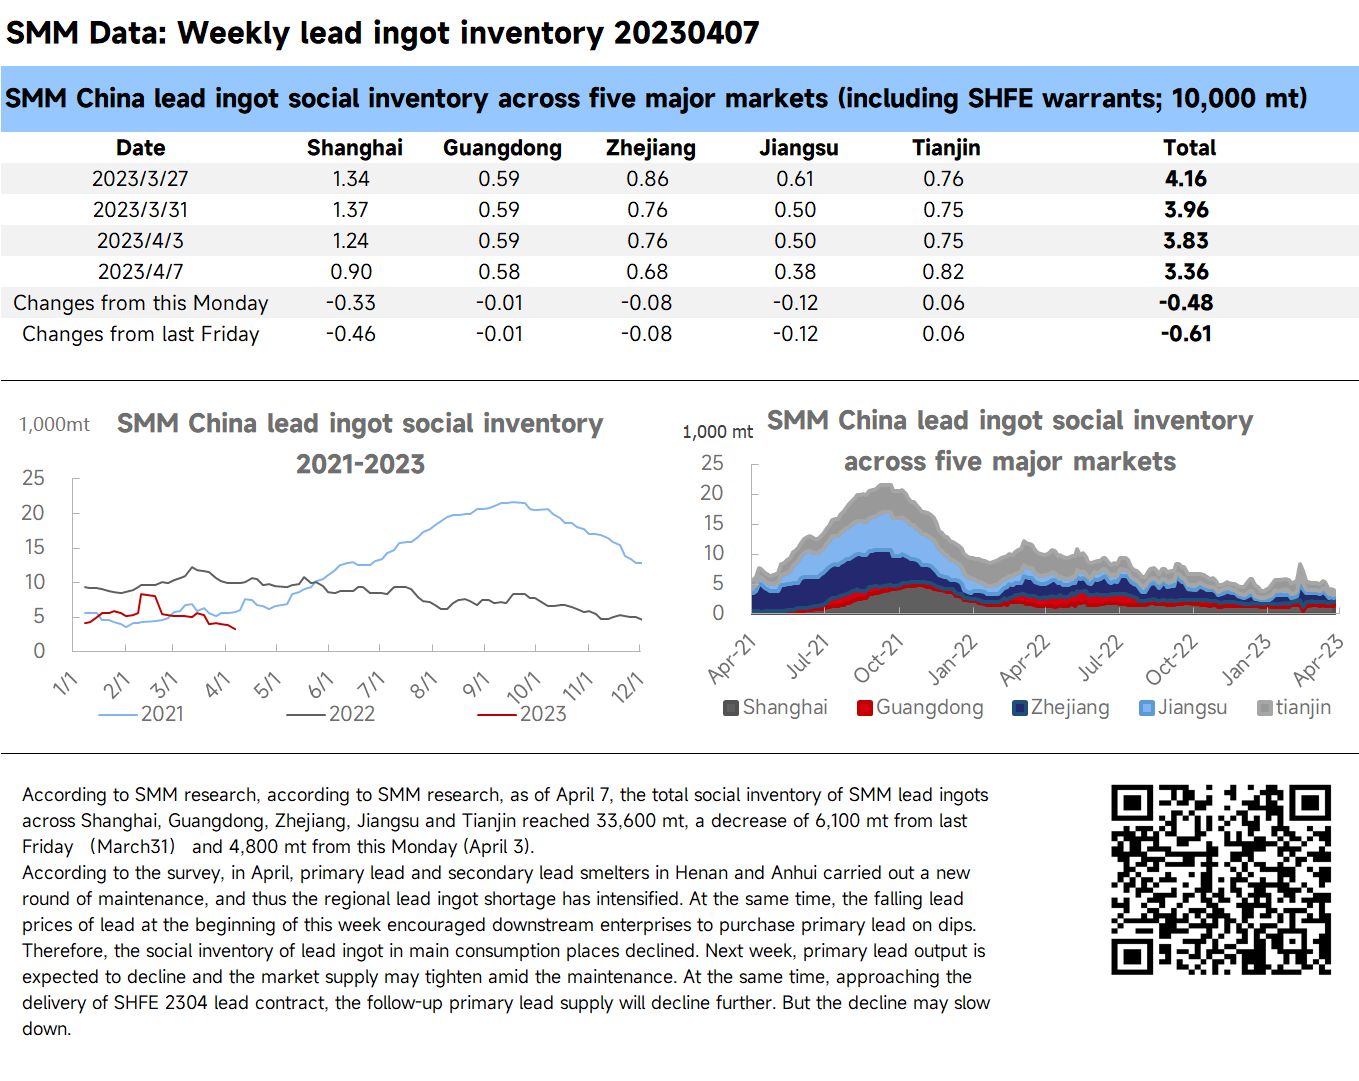
According to SMM research, according to SMM research, as of April 7, the total social inventory of SMM lead ingots across Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin reached 33,600 mt, a decrease of 6,100 mt from last Friday (March31) and 4,800 mt from this Monday (April 3).
According to the survey, in April, primary lead and secondary lead smelters in Henan and Anhui carried out a new round of maintenance, and thus the regional lead ingot shortage has intensified. At the same time, the falling lead prices of lead at the beginning of this week encouraged downstream enterprises to purchase primary lead on dips. Therefore, the social inventory of lead ingot in main consumption places declined. Next week, primary lead output is expected to decline and the market supply may tighten amid the maintenance. At the same time, approaching the delivery of SHFE 2304 lead contract, the follow-up primary lead supply will decline further. But the decline may slow down.
Bonded Zone Inventory of Nickel Drops Slightly from March 31
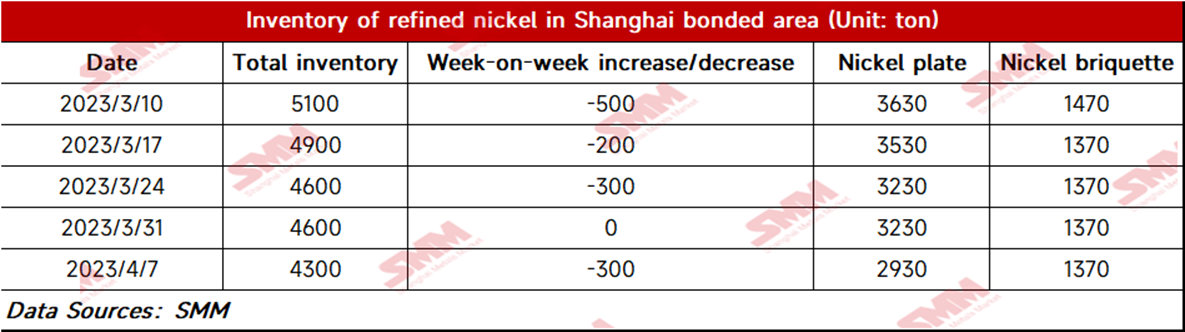
Bonded zone inventory of nickel dropped 300 mt to 4,300 mt WoW as of April 7, with the inventory of nickel briquettes and nickel plates standing at 1,370 mt and 2,930 mt respectively. SHFE/LME price ratio fell, and the import window remained closed this week. A small amount of NORNICKEL nickel was cleared during the week as some traders locked the price ratio. The spread between nickel briquette and nickel sulphate shrank on the fall in pure nickel prices, but the new energy sector did not release any nickel briquette demand.
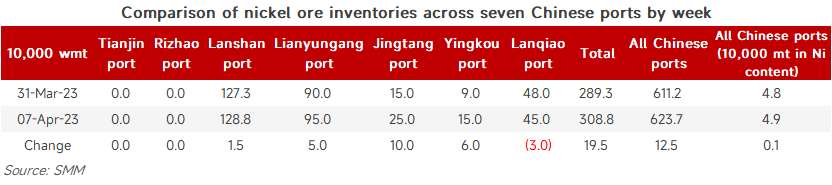
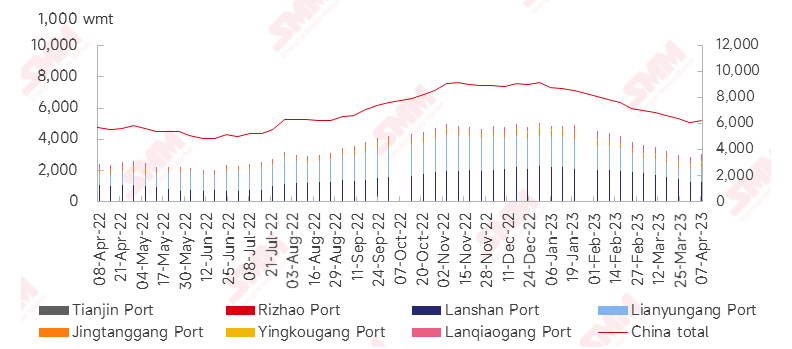
Nickel Ore Inventories at Chinese Ports up 125,000 wmt WoW
As of April 7, port inventories of nickel ore in China added 125,000 wmt to 6.24 million wmt compared with the previous week. The total Ni content stood at 49,000 mt. The port inventory of nickel ore across seven major Chinese ports stood at 3.09 million wmt, 195,000 wmt higher than last week. Nickel ore prices trended lower this week, and the NPI prices dropped to 1,042.5 yuan/mtu. The nickel ore buyers held a wait-and-see attitude since the NPI price trend was unclear, resulting in a sluggish nickel ore market. NPI plants were reluctant to purchase nickel ore due to the dropping NPI prices. The port inventory will grow with the subsided impact of the poor weather condition in the Philippines.