

SMM Network News: as of September 4, copper prices showed an obvious situation of external strength and internal weakness. Of this total, COMEX copper rose 7.2 per cent, while LME copper rose 5.72 per cent, while Shanghai copper rose only 0.02 per cent. The reason for this may be the inflow of American copper and Lun copper into China, and the recent appreciation of the RMB has also contributed to this trend. With the arrival of the peak consumption season, the long logic of Shanghai Copper will face verification.
The scissors gap between social integration and M2 growth is still optimistic.
From a macro point of view, in July, the scale of social financing was 22.53 trillion yuan, totaling 212.546 trillion yuan for the whole year, and the stock of social financing was 273.33 trillion yuan, an increase of 12.9 percent over the same period last year. M2 was 212.546 trillion yuan, an increase of 10.70 percent over the same period last year. The scissors gap between social integration stock and M2 growth rate is 2.2%, which continues to expand, which means that compared with idling in the financial system, funds enter the real economy more smoothly and the degree of economic activation increases. This index is a relatively reliable leading indicator of non-ferrous metals, the general inflection point will be about 2 months ahead of the copper price, the index is currently very healthy. Over the past month, liquidity has tightened significantly and capital prices have risen significantly. It is expected that the M2 year-on-year growth rate to be announced this week will slow somewhat, while the year-on-year growth rate of social financing is expected to maintain.
The influence of epidemic situation on Copper Industry chain
After about 10 years of rebalancing, the profit level of both copper mines and smelting enterprises is tight. Especially on the copper side, the costs of the world's major copper producers are mostly higher or unchanged than they were 10 years ago, while long-term downward copper prices continue to erode corporate profits. On the smelting side, the cost of refining and refining is at a historically low level due to relative overcapacity.
Fundamentals are changing in favor of doing long. In late March, when the epidemic was more severe, the price of COMEX copper fell below $2 per pound, which corresponds to about 12 million tons of fire production, according to the cost curve of S & P research. In 2019, the copper ore contains 20 million tons of copper. The implicit assumption at the time was that demand would fall by about 40%. Judging from the shrinking demand, copper prices at that time already had a considerable margin of safety. Copper has been the best-performing non-ferrous metal since April, especially since late June, when prices soared as a result of a simmering epidemic in South America.
The direct impact of the epidemic on copper prices is mainly two points, one is the direct impact on the production efficiency of copper scrap. After the epidemic, the disturbance of the scrap copper industry chain has always existed, whether it is the waste copper recycling system in developed countries or the waste copper processing plants in Southeast Asia, are affected by the epidemic. As a result, refined copper has partially replaced scrap copper, so we can see a substantial increase in refined copper imports.
Another impact of the outbreak on copper prices is that a large number of copper mine development projects have been delayed for at least three quarters. A typical example is the Oyu Tolgoi project. The mine is a mixed open-pit and underground mine, and the underground mining part is being expanded. it was originally planned to increase the production capacity from 125000-150000 tons to 560000 tons in 2025. Its grade and reserves are very considerable in recent years. In 2019, Rio Tinto confirmed that the project had been delayed by 160,30 months and exceeded the standard by US $1.2 billion to US $1.9 billion. In mid-April 2020, Rio Tinto lowered its production target for the mine. At present, there has been a new postponement of the project due to the epidemic situation of novel coronavirus. Originally, 2022 will be a big year for copper production, but after the outbreak, a large number of similar copper mine expansion projects will be postponed to 2023, and now we can be more optimistic about the curve before 2022.
In addition, the epidemic has led to a surge in the US fiscal deficit, which usually leads to a weak dollar, which means that the price of copper will be revalued. In addition, a weak dollar is generally conducive to a significant increase in capital expenditure in developing countries, which usually means buying plant, Electroweb and equipment, which is also good for demand for copper.
Inventory moving is strong on the outside and weak on the inside.
Last week, Shanghai copper fell slightly by 0.14%. LME copper rose 1.69%. As of September 4, copper stocks in the previous period stood at 176870 tons, an increase of 17360 tons, or 10.88 percent, compared with 159500 tons at the end of July. As of Sept. 7, LME copper stocks stood at 77550 tons, a sharp drop of 49130 tons, or 38.78 percent, from 126675 tons at the beginning of August. As of September 4, COMEX inventories stood at 83650 tonnes, down 5396 tonnes, or 6.05 per cent, from 89050 tonnes at the end of July. Non-commercial long positions in American copper have decreased, while COMEX copper has entered a crowded phase on a seasonal basis and continues to increase this week to hit a new high for the year. Shanghai copper funds have fallen. Keep the water near the level water. The spot has poor digestibility for high copper prices.
China's imports of refined copper totaled 2.55 million tons as of July, up 34.44 percent from a year earlier, according to the General Administration of Customs. Of this total, imports rose 127.55% in June from a year earlier, falling slightly in July, but still 91.18%. Since the second half of the year, due to the strong demand for copper and the limited supply of scrap copper, the import window of refined copper has been opened frequently. However, imports are expected to be slightly lower in August than in July, as the import window has narrowed since mid-July and is now almost closed. China's copper stocks continue to rise due to rising imports and weak demand in the domestic market, which is likely to depress domestic prices in the coming months. The current strength of copper implies that some of the peak season demand is expected to improve, which depends on the data verification.
The factors supporting the copper bull are weakening. The driver of copper price rise is fundamentally different from that of 2005-2010. It is less demand-driven and more supply-side-driven, so its durability should be weaker than that of 2009-2010. From the spot discount, as of September 7, Shanghai goods trade spot discount for 20 yuan, the index has maintained a weak premium or discount state for nearly a month, the spot end for high copper price indigestion. In terms of COMEX positions, as of Sept. 1, there were 104091 non-commercial bulls, 50975 short positions and 53116 net positions, an increase of 10626, or 25 per cent, from a month ago. From a seasonal point of view, non-commercial net positions are at a higher level than in the past five years. The author believes that the trading of multi-copper is already crowded, but it has not yet reached an all-time high level.
Since August, the opening frequency of the import window has decreased significantly, and with the arrival of the peak consumption season, the long logic of Shanghai copper will face verification.
"Click to sign up: 2020 Fifth China Electrotechnical Materials supply and demand Trade Summit
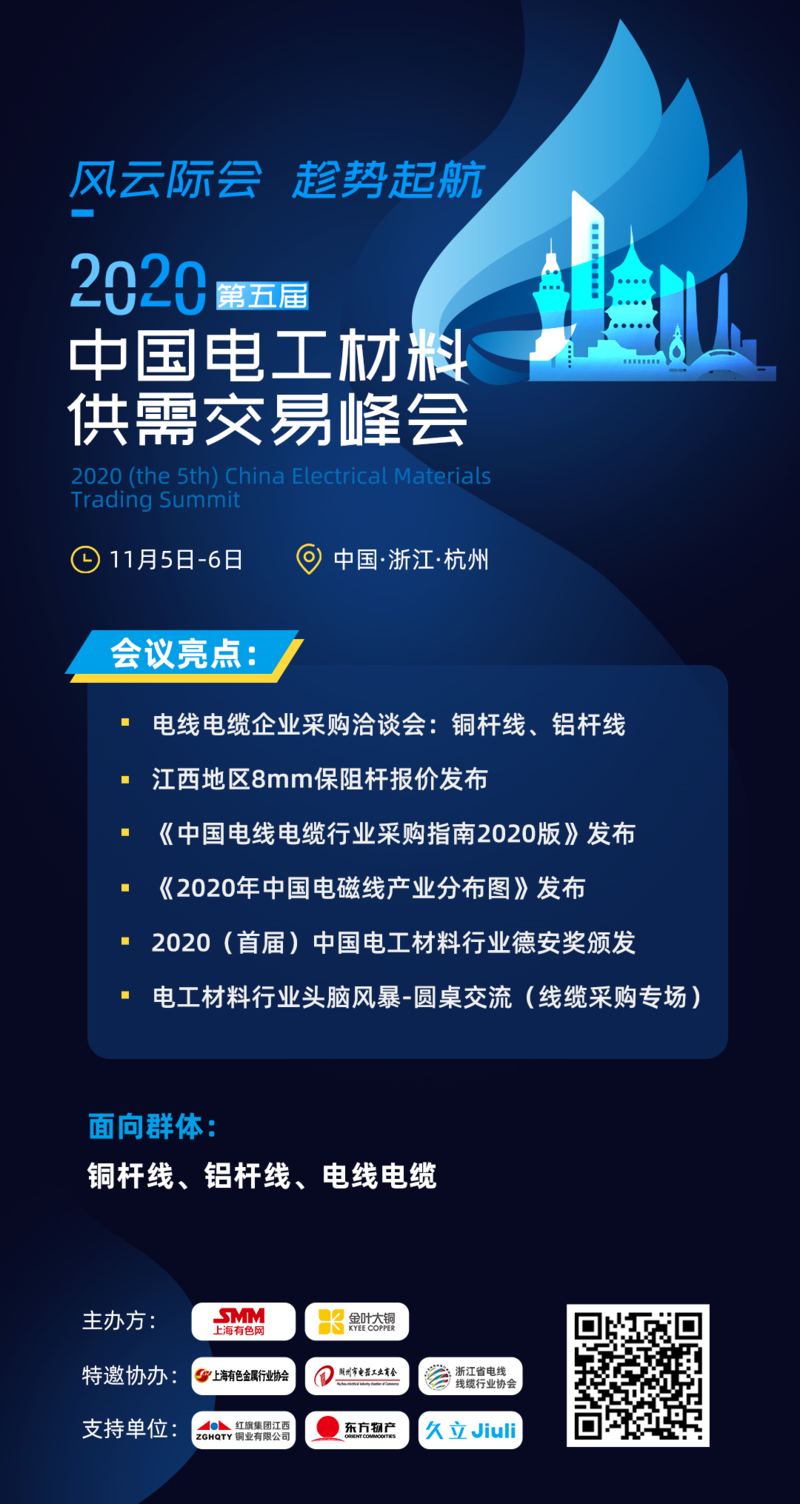
Scan the code to participate in the meeting or apply to join the SMM Electrical Industry Exchange Group



