The Role of Ferrous Metals in Steel Production
Understanding Ferrous Metals
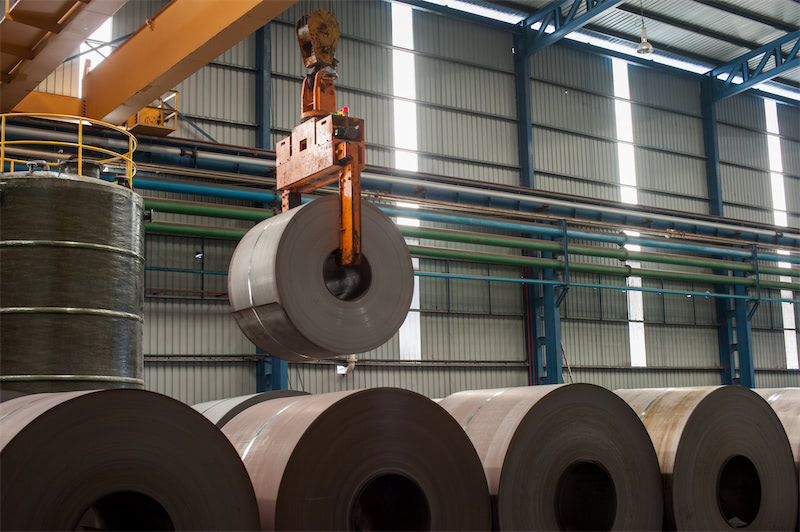
Ferrous metals, characterized by their iron content, play a vital role in steel production. Steel, an alloy composed primarily of iron and carbon, derives its strength and durability from ferrous metals. The ferrous metals industry encompasses several vital components, including iron ore, coking coal, and scrap metal, each contributing uniquely to the steel-making process. As the steel demand continues to rise globally, understanding the nuances of ferrous metals is essential for industry stakeholders and investors alike.
Importance of Iron Ore and Coking Coal
Iron ore is the primary raw material for steel production, accounting for a significant portion of the industry's overall costs. The quality and purity of iron ore directly affect the efficiency and output of steel manufacturing. Coking coal, on the other hand, is indispensable in the steel-making process as it is used in the production of coke, which is a crucial component in blast furnaces. The interplay between iron ore and coking coal prices influences the overall cost of steel production, thereby affecting market dynamics.
Essential Role of Scrap Metal
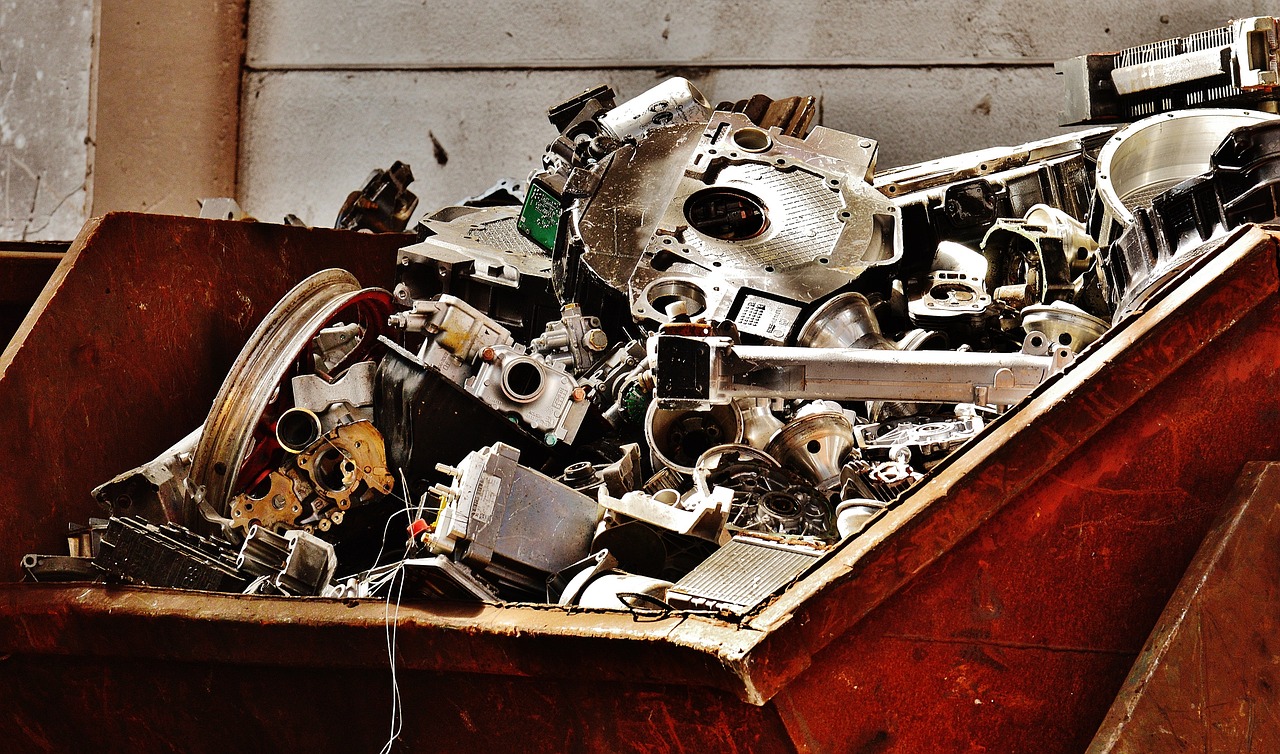
Scrap metal serves as an important secondary raw material in steel production, constituting a significant alternative to virgin materials. The recycling of scrap metal not only lowers production costs but also diminishes the environmental impact of steel manufacturing. Market prices for scrap metal can fluctuate based on availability and demand, which in turn influences the pricing strategies of steel producers. As the world shifts toward more sustainable practices, the role of scrap metal in the ferrous metals landscape is gaining prominence.
Market Volatility and Its Impact on Steel Prices
Sensitivity of Steel Prices to Market Changes
Steel prices are incredibly sensitive to fluctuations in the prices of ferrous metals. When ferrous metal costs rise, this often leads to an increase in the production costs of steel, prompting manufacturers to adjust their prices accordingly. Conversely, a drop in ferrous metal prices may create a competitive pricing environment within the steel market. This cyclical relationship underscores the importance of monitoring ferrous metal pricing trends closely, as they can dramatically affect supply chain dynamics and profitability for steel manufacturers.
Demand and Supply Dynamics in the Steel Industry
The steel industry operates within a complex framework of demand and supply dynamics that are intrinsically linked to the prices of ferrous metals. An increase in construction and infrastructure projects typically elevates the steel demand, which in turn drives up the demand for ferrous metals. However, if the supply of ferrous metals cannot meet this burgeoning demand, prices are likely to escalate, further straining steel prices. Understanding these dynamics is crucial for stakeholders seeking to navigate the intricate relationship between ferrous metals and the steel market.
Raw Material Price Fluctuations and Their Effects
Trends in Iron Ore Pricing
Recent trends in iron ore pricing reveal a volatile landscape shaped by factors such as geopolitical issues, changes in production capacity, and fluctuations in global demand. For example, production cuts in key exporting countries can lead to supply shortages, thereby driving up prices. Conversely, increased production from emerging markets may lead to a surplus, subsequently lowering prices. Analyzing these trends is critical for steel manufacturers who depend on stable pricing patterns to forecast their operational budgets and financial planning.
Impact of Coking Coal Costs on Steel Production
Coking coal prices have a direct and significant effect on steel production costs. As one of the primary inputs in the steel-making process, any rise in coking coal prices can lead to higher expenses for steel manufacturers. This can result in an overall increase in steel prices, diminishing competitiveness in global markets. Stakeholders must keep a close eye on developments in the coking coal market, as unexpected price hikes can disrupt production schedules and financial forecasts for steel producers.
Trade Dynamics in the Ferrous Metals Sector
Overview of Trade in Emerging Markets
The trade dynamics of ferrous metals are increasingly becoming significant, especially in emerging markets. Countries like Brazil, India, and China have witnessed a surge in both production and consumption of ferrous materials, affecting global pricing and trade routes. As these markets continue to develop, they also influence the steel demand, as infrastructural projects require substantial amounts of this versatile material. Understanding the intricacies of ferrous metals trade within these markets can provide insights into future trends and opportunities for growth.
Implications for Global Steel Production
The interplay between ferrous metal pricing and trade dynamics has far-reaching implications for global steel production. Increasingly, countries are relying on imports to meet their domestic steel requirements, leading to a more interconnected global market. As trade policies and tariffs shift, the competitive landscape of the steel industry will also evolve, potentially altering production costs and pricing strategies. Stakeholders in the steel sector need to analyze these implications carefully to make informed decisions regarding investments, production capacities, and market positioning.
Key Factors Determining Steel Prices
Cost of Raw Materials
The costs associated with raw materials directly influence steel pricing structures. The reliance on ferrous metals as the predominant input in steel manufacturing sets the stage for price volatility. Variations in the prices of these raw materials can cause fluctuations in production expenses, ultimately resulting in a ripple effect on the final cost of steel products. Moreover, as the demand for ferrous metals rises commensurately with increased steel production, manufacturers must adapt their pricing strategies to account for these heightened costs.
Influence of Scrap Metal Prices
The pricing of scrap metal serves as a critical component of the overall cost structure for steel production. As a significant contributor to the steel-making process, fluctuations in scrap metal prices can substantially affect production costs and profit margins. When demand for scrap metal surges—driven by recycling efforts and sustainable practices—prices tend to increase. Conversely, when the availability of scrap metal outpaces demand, it can lead to decreased prices, providing opportunities for steel producers to reduce costs and potentially lower the prices of their finished products.
Effect of Iron Ore Quality and Cost
Iron ore quality and its associated costs are pivotal in determining not only the efficiency of steel production but also the overall market price of steel. Higher-grade iron ore is linked to superior steel quality, yet it often comes at a premium. As industry standards evolve and demand for higher-quality steel increases, steel manufacturers find themselves navigating the intricate balance between raw material costs and product quality. Consequently, fluctuations in iron ore costs can dictate pricing strategies, influencing competitiveness within the steel marketplace.
Role of Coking Coal Prices
Coking coal, essential for producing the coke utilized in blast furnaces during steelmaking, plays a significant role in steel pricing dynamics. Variations in coking coal prices can have a direct impact on production costs, necessitating adjustments in steel pricing as manufacturers strive to maintain margins. Furthermore, the intertwined nature of coal and steel prices makes it essential for industry stakeholders to monitor this market closely, especially as regulatory frameworks continue to shift toward sustainable energy sources.
How Shanghai Metals Market (SMM) Tracks Industry Changes
Introduction to Shanghai Metals Market (SMM)
Shanghai Metals Market (SMM) has established itself as a leading provider of industry intelligence and data on metals, including ferrous metals. As an essential resource for industry professionals, SMM provides insights into market trends, pricing, supply and demand metrics, and specific reports pertinent to the steel industry. This platform helps stakeholders make informed decisions by offering timely updates, analysis, and the latest news, fostering an environment of transparency in the often volatile metals market.
Benefits and Features of Using SMM for Industry Insights
Utilizing SMM's resources can significantly benefit industry players by providing data analytics that help in forecasting price trends and managing risks. The platform's comprehensive coverage of market intelligence allows stakeholders to gain deeper insights into supply chain dynamics and identify emerging opportunities. Additionally, SMM’s data-driven approach aids stakeholders in strategizing for cost management and pricing, in conjunction with understanding the potential impacts of raw material cost fluctuations on their operations. Access to SMM's analytics and reports can empower stakeholders to develop proactive measures against market volatility in the ferrous metals and steel segments.
Implications for Industry Stakeholders
Strategies for Managing Cost Volatility
The volatility inherent in ferrous metals pricing necessitates that steel manufacturers devise strategies to mitigate its impacts on their operations. Effective management of raw material costs can involve developing long-term supplier contracts to lock in pricing or investing in technologies that enhance production efficiencies. Additionally, embracing alternative materials—including increased usage of scrap metals—could provide a buffer against rising costs. Furthermore, regular market analysis and the employment of hedging strategies can empower stakeholders to navigate price uncertainties while remaining competitive in the marketplace.
Long-Term Trends and Future Predictions
The future trajectory of ferrous metals pricing and its implications on the steel market is shaped by several long-term trends. The global push toward sustainability and the corresponding shift in demand toward recycled steel versus virgin materials are poised to redefine market dynamics. Furthermore, advancements in manufacturing technologies may enable cost reductions in steel production, fostering a competitive edge for companies able to adapt quickly. As the landscape evolves, continuous monitoring of market indicators will be crucial for stakeholders to predict shifts in pricing structures and align their strategies accordingly.
Through thorough analysis and comprehensive strategies, industry stakeholders can position themselves to leverage trends in ferrous metals pricing, ultimately shaping the future of the steel industry. The interrelation of raw material costs, supply and demand dynamics, and the evolution of global trade patterns will continue to influence the strategic decisions of manufacturers, traders, and investors alike. By understanding these complexities, stakeholders will be better equipped to navigate an increasingly interconnected and fluctuating marketplace.