In October 2026, SMM 1# silver production fell 5.03% MoM; cumulative production in 2026 was approximately 16,000 mt, up 3.72% YoY.
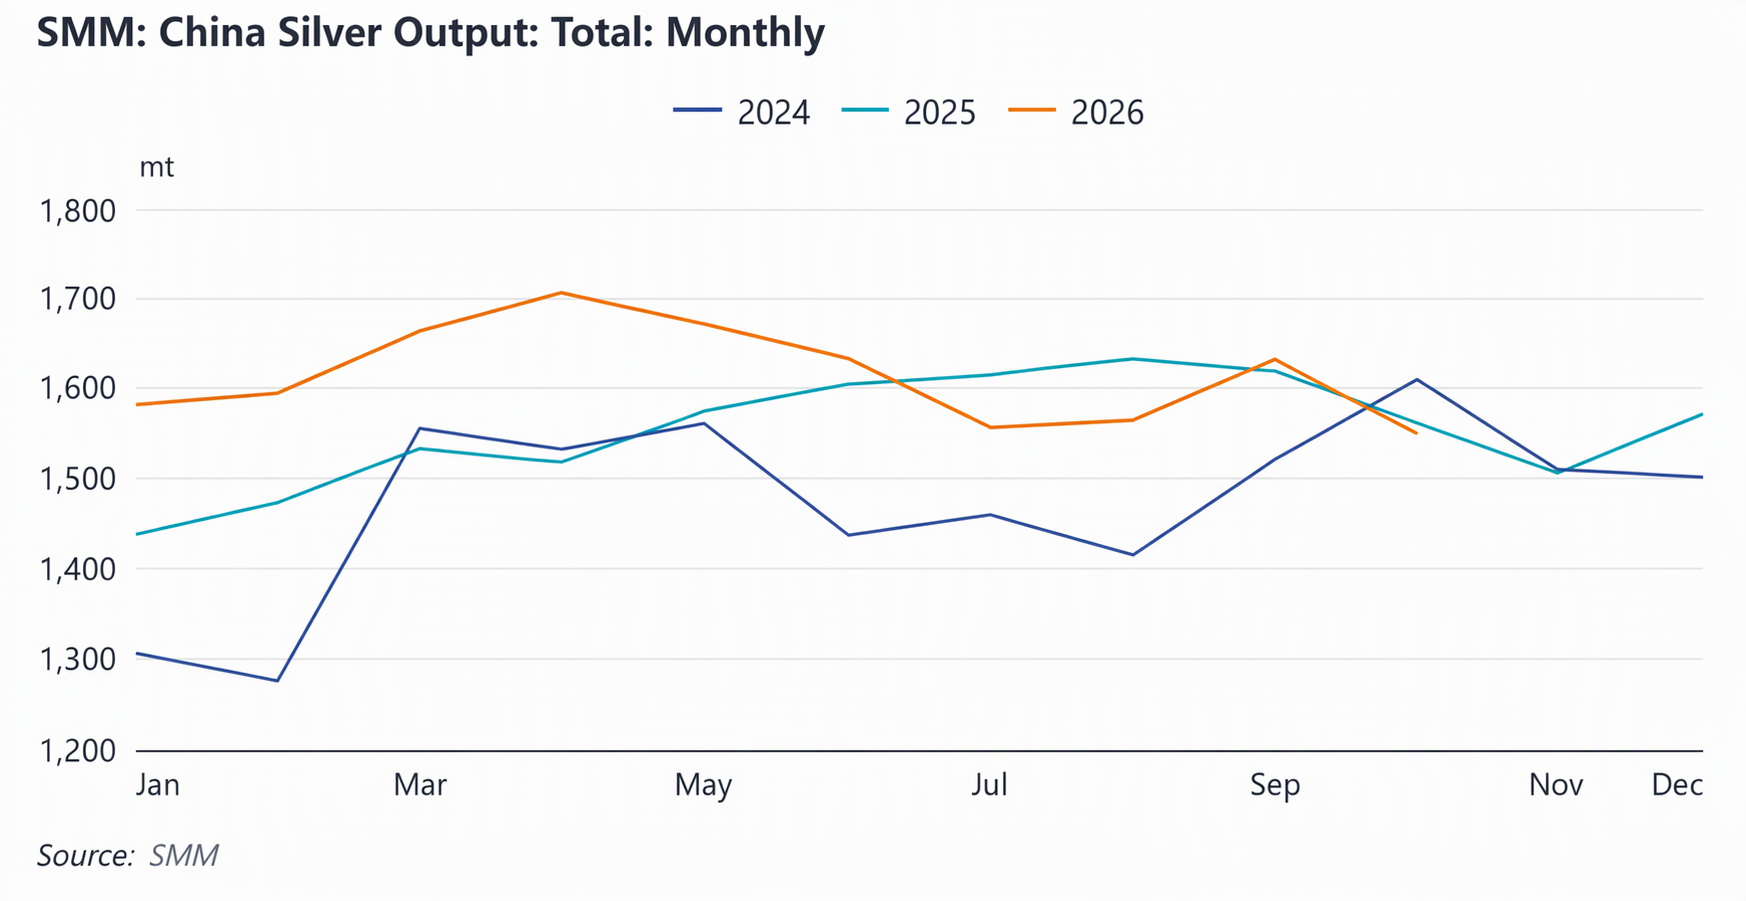
The decline in silver ingot production this month came mainly from two sources: first, non-mineral silver, as recycled silver production was largely halted during the National Day holiday; second, by-product mineral silver from copper concentrates, as some copper smelting regions underwent maintenance shutdowns, leaving certain plants without silver output during the month and shipments lower. Some copper smelters are expected to carry out maintenance shutdowns in November and December, which may cause slight fluctuations in production; meanwhile, silver ingot production at lead-zinc smelters has been gradually recovering since September. Overall, the increase in silver ingot production this year was mainly driven by higher imports of silver-bearing concentrates.
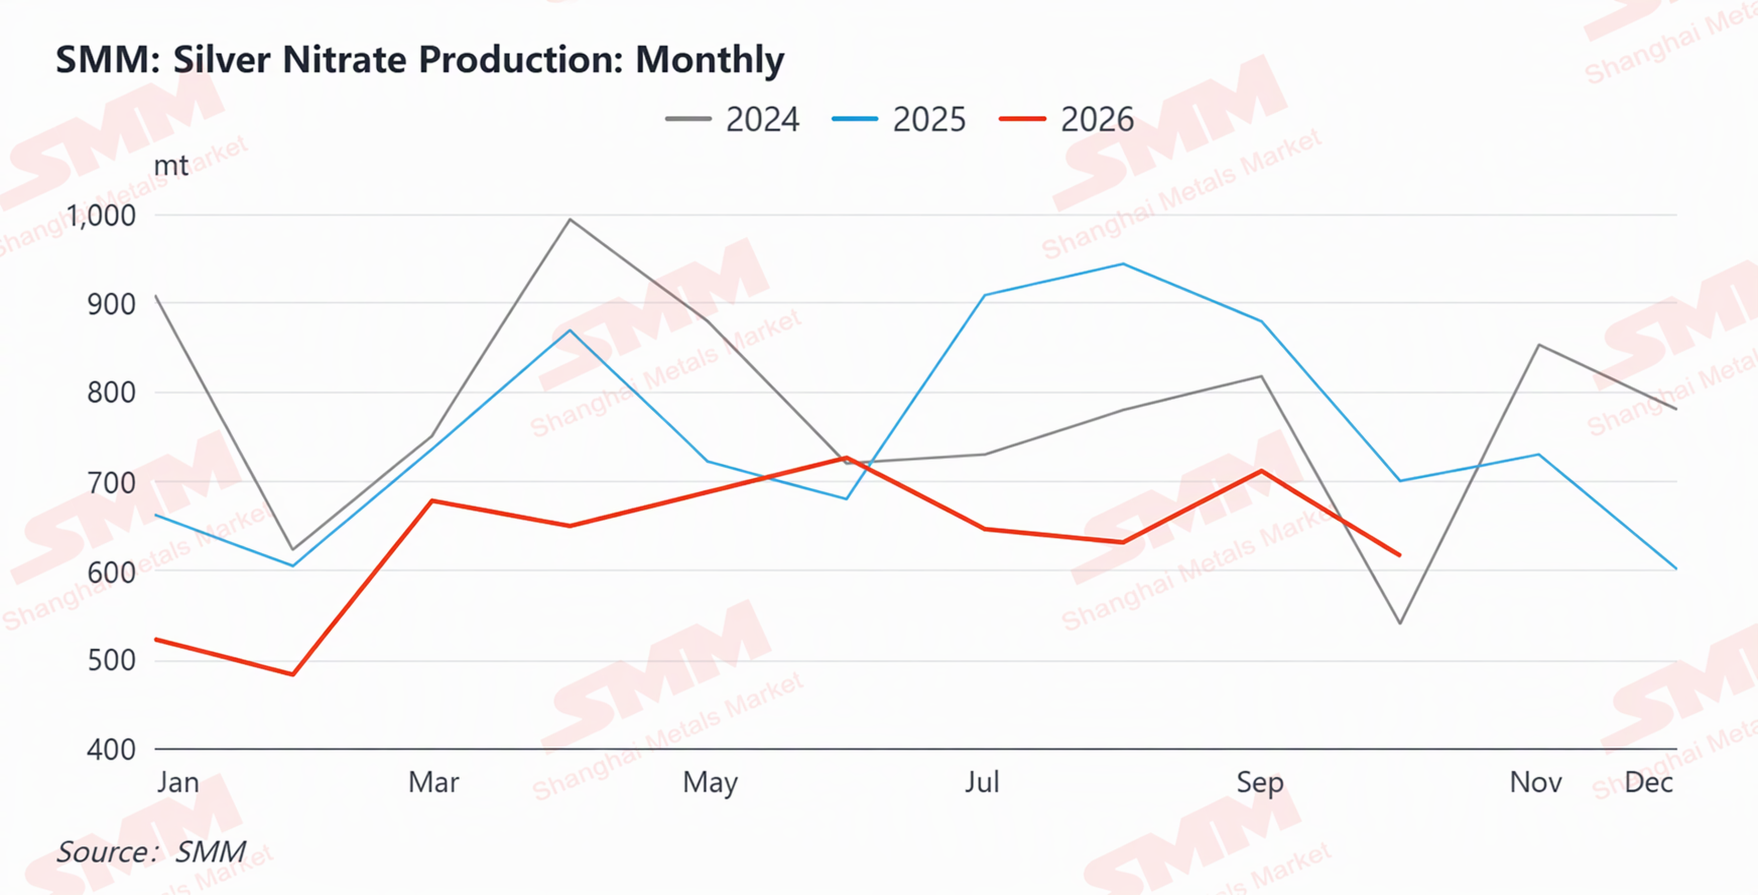
In the PV sector, SMM silver nitrate production fell 13.48% MoM in October, with cumulative 2026 production at approximately 6,000 mt, down 17.59% YoY. The decline this month was mainly due to pre-holiday stockpiling in late September, which pulled forward about one week of demand. For the full year, silver usage in the PV industry remains on a downtrend.
In terms of spot silver ingot trading in October, the market maintained transaction prices at a slight premium to the SGE Ag (T+D), supported mainly by several waves of concentrated consumption: first, heavy stockpiling before the National Day holiday in late September; second, seasonal jewelry demand during the National Day holiday, led by Shenzhen, which persisted throughout October; third, after mid-month CPI data was released, silver prices fell sharply, stimulating downstream restocking; fourth, at month-end, escalating geopolitical conflicts drove silver prices to hit bottom again, triggering another wave of buying. However, by the month-end period, downstream consumption momentum weakened somewhat, and silver ingot producers began to resume production and shipments. SHFE inventory showed a sustained decline followed by stabilization; as of October 29, SMM social inventory had destocked by approximately 68 mt from the previous month-end.
The market expects that the consumption recovery in October was driven more by seasonality and the sharp price decline, which prompted early stockpiling and to some extent pulled forward consumption in Q4. If the PV sector continues to weaken and seasonal consumption gradually fades, market trading will likely return to a sluggish state.