September Price Review
Source: SMM
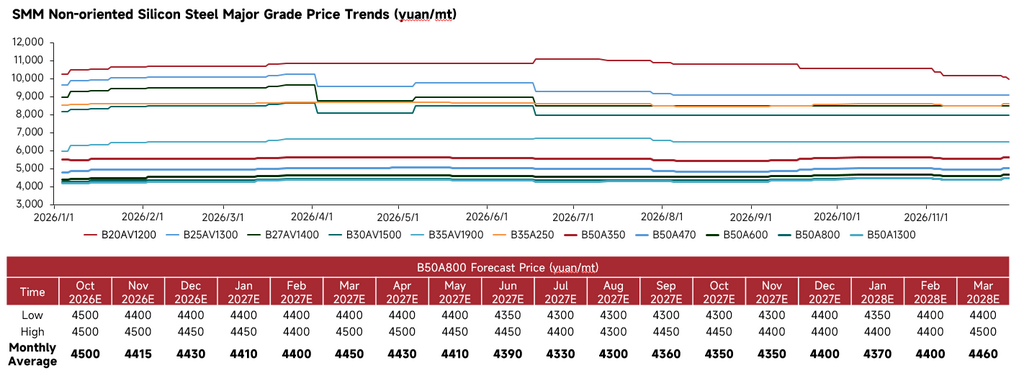
Non-oriented silicon steel prices trended generally stronger in September. Price data showed that price centers of mainstream grades edged higher, with high-grade and medium-low grade products firming in tandem. The monthly average price of the benchmark grade B50A800 rose month-on-month from August. Steel mills lifted ex-factory quotations, supported by hot rolling cost support on the raw material side. Some suppliers proactively cut output, easing the loose supply situation. Downstream motor and home appliance sectors gradually entered their traditional peak season, boosting rigid-demand spot purchases. Trader sentiment improved, and low-level restocking picked up in the market. Overall, the market shifted from early low-level consolidation to steady-to-strong performance, registering a phased price recovery. Nevertheless, incremental downstream demand remained constrained, so the upside was relatively moderate without a sharp rally.
Fundamental Analysis
Source: SMM
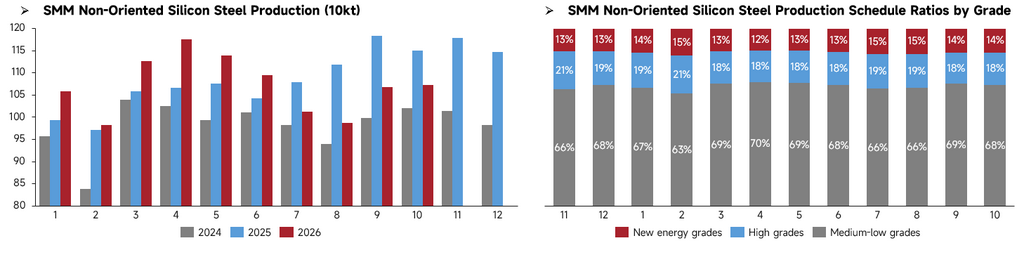
Domestic non-oriented silicon steel production schedules rose month-on-month in September, as steel mills raised production plans in anticipation of the peak season. Grade differentiation persisted. Compared with August, mills moderately increased output of medium-low grades while reducing the proportion of high-grade production. August production cuts relieved earlier supply pressure to a certain extent, yet the obvious rebound in medium-low grade output in September reflected steel mills’ improved expectations for the traditional peak season. Backed by recovering rigid downstream demand and firmer prices, producers were more willing to ramp up production. That said, incremental demand for high-grade grades was limited, slowing the pace of high-grade production release.
Planned domestic non-oriented silicon steel output will remain at a high level in October, keeping overall production volume elevated. The grade structure will adjust again: compared with September, mills will moderately reduce medium-low grade output and restore the proportion of new-energy grades, reallocating production resources to high-grade varieties. Following concentrated supply releases in September, spot supply pressure for medium-low grades has emerged. Together with slower downstream restocking, this has prompted steel mills to fine-tune their production mix. New-energy motor orders remain resilient, supporting stable high-grade output. Overall supply stays relatively loose, and supply pressure has not seen fundamental relief.
Source: Public Data, SMM
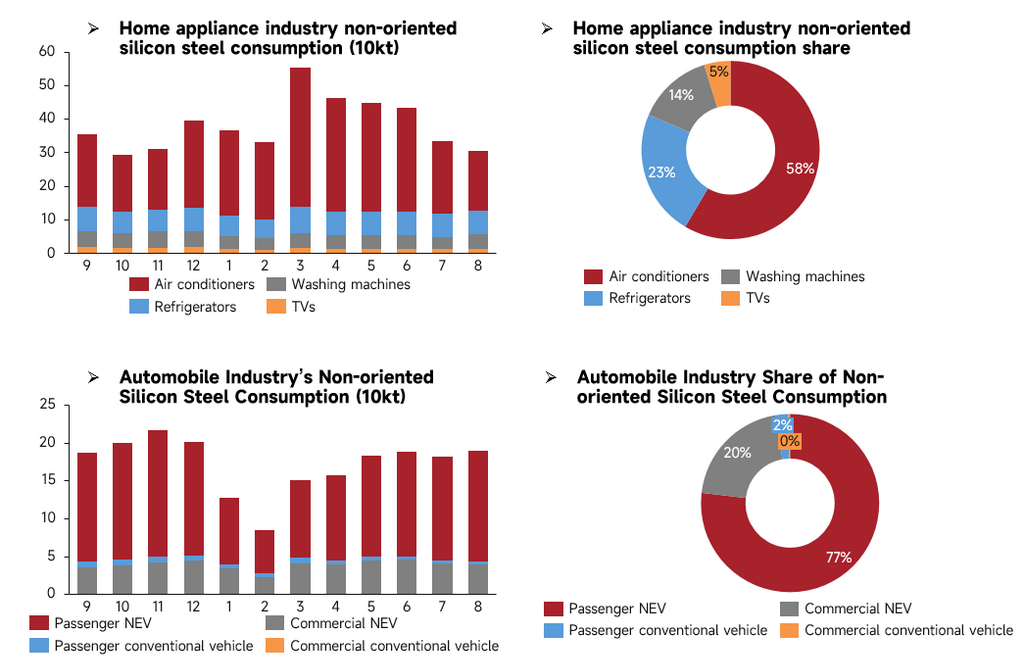
Output of major domestic home appliance categories continued to weaken seasonally in August. Production of air conditioners, refrigerators, washing machines and color TVs fell further, and the monthly consumption of non-oriented silicon steel by the home appliance sector declined accordingly. In terms of consumption structure, air conditioners remained the main silicon steel consumer in home appliances, while refrigerators, washing machines and color TVs maintained stable consumption shares. Total non-oriented silicon steel consumption by home appliances dropped further month-on-month in August, mainly dragged down by weak air-conditioner demand in the traditional off-season.
New-energy vehicle output stayed high in China’s auto sector in August. Output of new-energy passenger and commercial vehicles remained resilient, while production of traditional fuel vehicles fluctuated slightly. As a core consumption sector for non-oriented silicon steel, new-energy vehicles accounted for an overwhelming share of silicon steel consumption within the auto industry. Monthly silicon steel consumption by the auto sector edged up month-on-month in August. Stable production schedules for new-energy vehicles supported silicon steel demand, partially offsetting consumption declines in home appliances. However, limited demand gains in the auto segment failed to reverse the downturn in home appliances, leaving the overall downstream comprehensive demand for non-oriented silicon steel weak.
October Price Outlook
Looking ahead to October 2026, on the supply side, China’s planned non-oriented silicon steel output will record only a modest increase, mainly among medium-low grades. For one thing, the traditional peak season has underperformed expectations with limited improvement in downstream orders, so overall demand growth is capped and there is little room for output expansion. For another, leading producers including Baowu kept November base prices unchanged, showing limited willingness to push prices higher. Poor profit margins at steel mills have curbed production enthusiasm.
On the demand side: For home appliances, some manufacturers maintained maintenance on air-conditioner production lines in September, pushing operating rates to a relatively low level for the whole year. Refrigerator and washing machine performance was relatively stable; some producers raised output to build inventories for Q4 promotional campaigns, while others cut production due to high pre-existing inventory. For the auto sector, new orders rose month-on-month in September. Trade-in programmes and local subsidy policies continued, alongside frequent new vehicle launches, lifting terminal foot traffic and orders sequentially. New-energy vehicles remain the mainstay of consumption, while fuel vehicle sales saw no notable improvement. Persistent fluctuating rises in oil prices are the primary factor dampening consumers’ willingness to purchase fuel vehicles.
On the cost side, the hot rolled coil market lacks a clear directional driving factor in October and is expected to stay weak and range-bound. Market participants will keep a close eye on post-holiday steel mill output adjustments, the recovery of terminal spot transactions and the latest policy developments. In summary, SMM forecasts that medium-low grade non-oriented silicon steel prices in October 2026 will generally follow a trend of strength first, then stabilization.