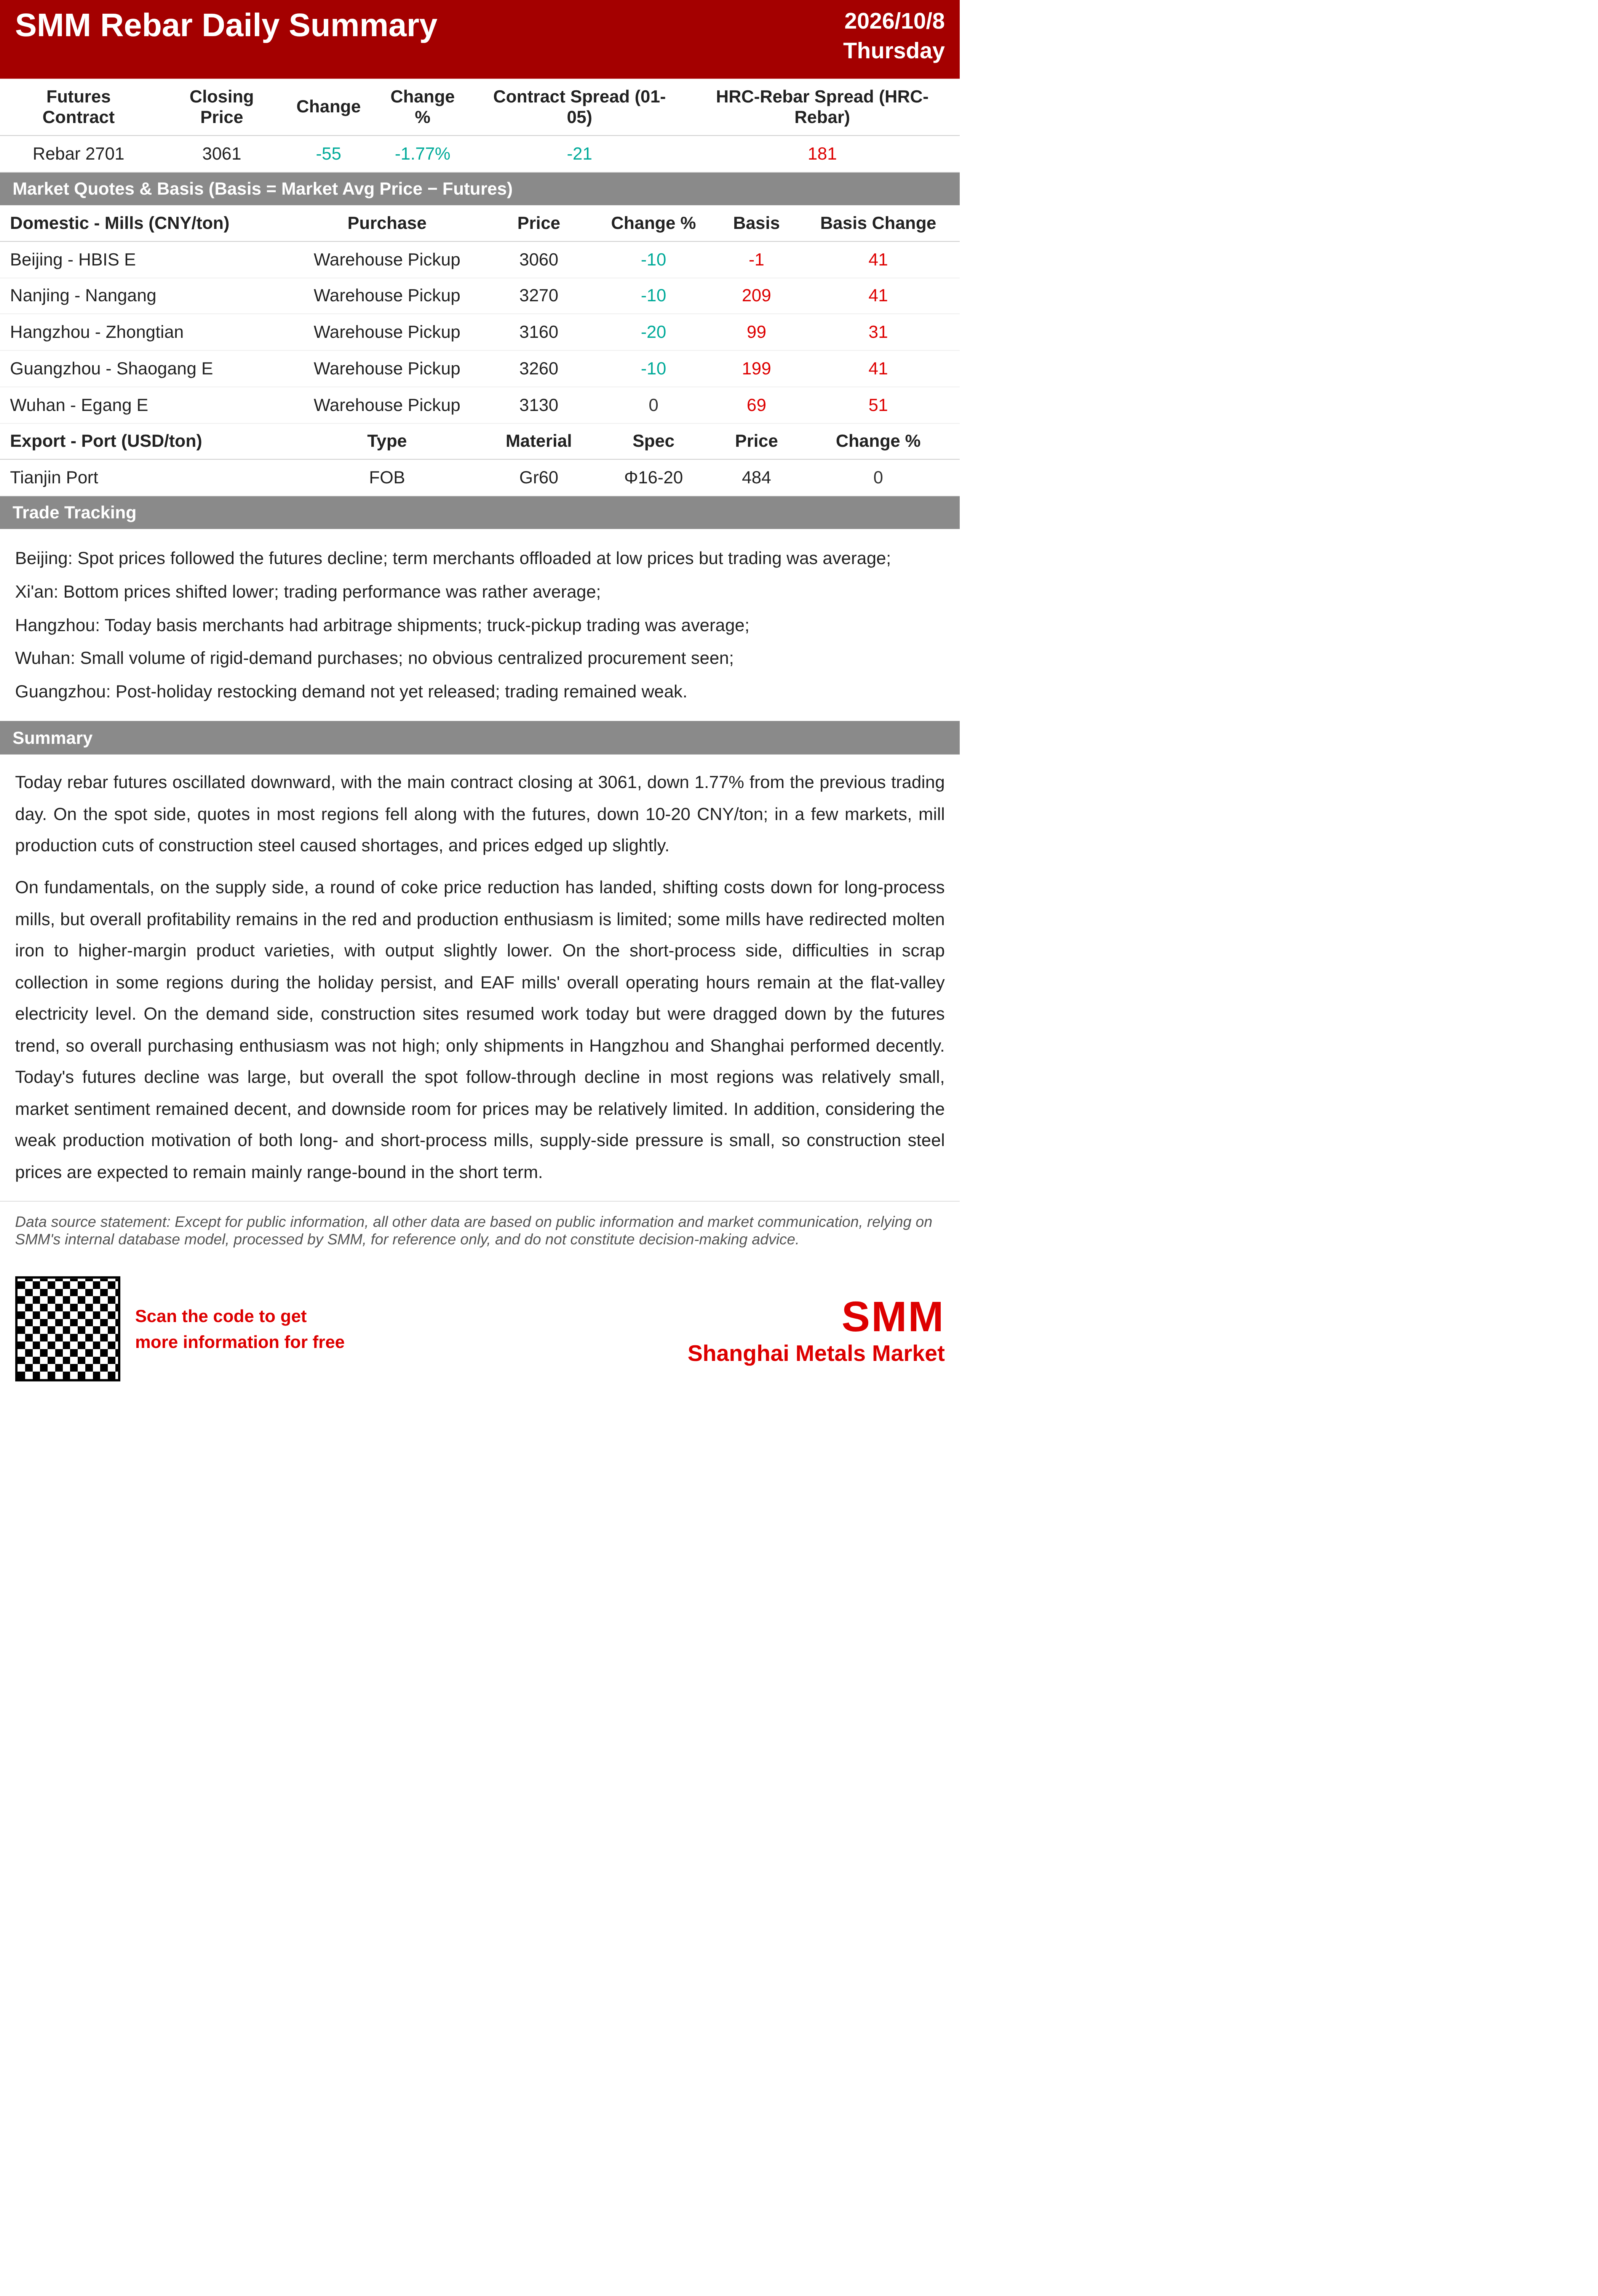
Today, rebar futures drifted lower, with the most-traded contract closing at 3,061, down 1.77% from the previous trading day. In the spot market, most regional prices followed the futures decline, falling by 10-20 yuan/mt, while a few markets saw slight price increases due to shortages of construction steel caused by production cuts at steel mills.
From a fundamental perspective, on the supply side, the first round of coke price cuts was implemented, lowering costs for blast furnace steel mills, but overall margins remained in loss-making territory, limiting production enthusiasm. Some mills diverted hot metal to higher-margin products, leading to a slight decline in output. For EAF steel mills, scrap collection difficulties persisted in some regions during the holiday, and overall operating hours remained at off-peak and flat electricity tariff levels. On the demand side, construction sites gradually resumed work today, but overall purchasing enthusiasm was subdued due to the weak futures trend, with only Hangzhou and Shanghai showing moderate shipment performance. Despite the sharp decline in futures today, spot prices in most regions fell by a relatively small margin, market sentiment remained moderate, and downside room for prices may be relatively limited. Additionally, considering the lack of production motivation at both BF and EAF steel mills, supply-side pressure is relatively small, so construction steel prices are expected to consolidate in the short term.