LME Copper Recovers Early Holiday Losses, With China's Stock Build in Focus
LME copper ended China's October 1–6 National Day holiday almost exactly where it began. Prices fell early in the break, then recovered as LME inventories continued to decline. With SHFE closed throughout the holiday, attention now turns to how much copper accumulated in China and whether buying resumes as fabricators return to work.
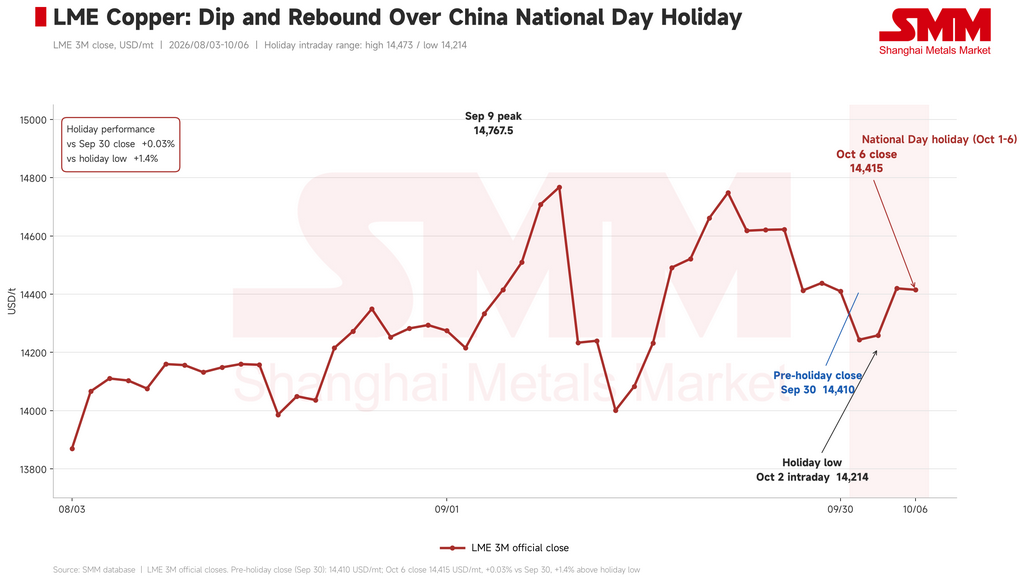
The SHFE November copper contract closed at RMB 109,680/tonne (approximately US$16,359/tonne) before the holiday, while LME copper finished September 30 at US$14,410/tonne. LME copper slipped to US$14,243.5/tonne on October 1 and reached a holiday low of US$14,214/tonne on October 2. It subsequently recovered, closing at US$14,420/tonne on October 5 and US$14,415/tonne on October 6—just 0.03% above its pre-holiday close. The holiday high was US$14,473/tonne. At around 3:00 p.m. Beijing time on October 7, it was trading near US$14,405/tonne.
 Macro-side
US data released during the holiday gave the Federal Reserve less reason to raise rates immediately, although the outlook for the rest of the year remains unsettled. Annual core PCE inflation slowed to 3% in August, its lowest reading since February 2026. At the same time, nonfarm payrolls rose by only 29,000, pointing to a sharp loss of momentum in hiring. There is little sign of widespread layoffs, however. Initial jobless claims unexpectedly fell to 197,000, against expectations of 200,000, and continuing claims dropped to 1.701 million, their lowest level since April 2023. The unemployment rate edged up to 4.2%. Taken together, the figures suggest employers are reluctant to hire but are also holding on to existing staff. The US trade deficit provided another sign of strain. It widened to US$105.6 billion in August, up 13.7% from July’s revised US$92.8 billion and 77.2% from US$59.6 billion a year earlier. The deficit exceeded market expectations and was the largest since March 2025, when a rush to import ahead of tariffs pushed it to a record US$140.5 billion.
As of October 7, CME FedWatch put the probability of no rate change by October at 79.5%, versus 20.5% for a cumulative 25-basis-point increase. By December, those probabilities were 15.5% for no change, 68.0% for a 25-basis-point increase and 16.5% for a 50-basis-point increase. The latest inflation and employment figures have eased fears of an imminent escalation in tightening, but they have not resolved the question of where rates will stand at year-end.
In China, the official manufacturing PMI rose 0.3 percentage points to 50.1 in September, returning to expansion territory. That modest improvement supports the demand outlook, though the stronger test will be whether it translates into orders and copper purchases after the holiday.
Geopolitical and policy risks remain in the background. Iran's interior minister arrived in Doha for talks, offering a tentative sign of easing US–Iran tensions, but the issue of passage through the Strait of Hormuz remains unresolved. A renewed rise in oil prices could revive inflation concerns. Meanwhile, the absence of a clear decision on US refined copper tariffs after the late-September checkpoint has taken some momentum out of the tariff trade.
Fundamental-side
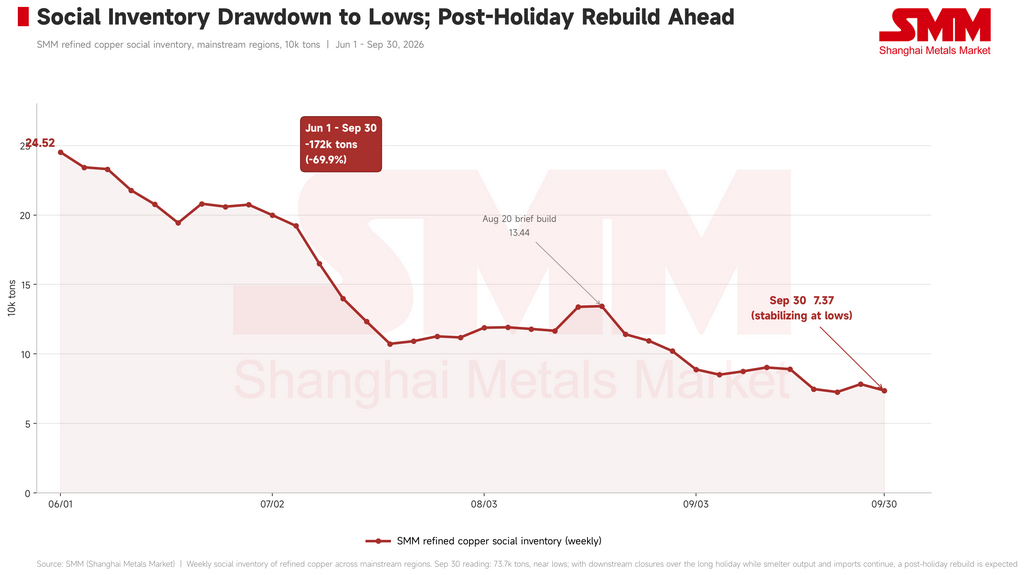
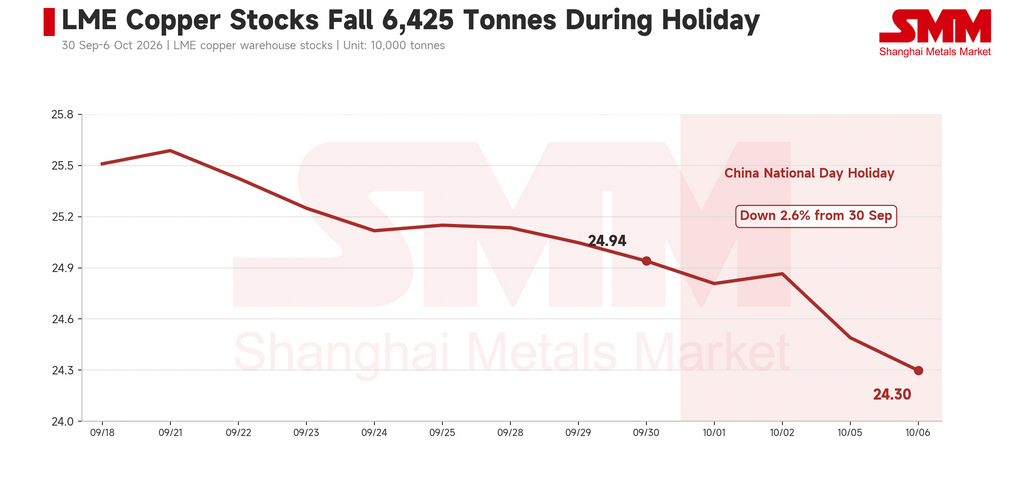
LME copper stocks fell by 6,425 tonnes during the holiday, from 249,400 tonnes on September 30 to 242,975 tonnes on October 6—a decline of about 2.6%. The draw helped prices recover from their early-October low. The inventory picture in China is beginning to move the other way. SMM recorded 73,700 tonnes of copper stocks across major domestic markets on September 30. That remains a low level, but stocks had started to edge higher as imported and domestically produced metal arrived in the spot market. Further arrivals are expected to lift social inventories after the holiday.
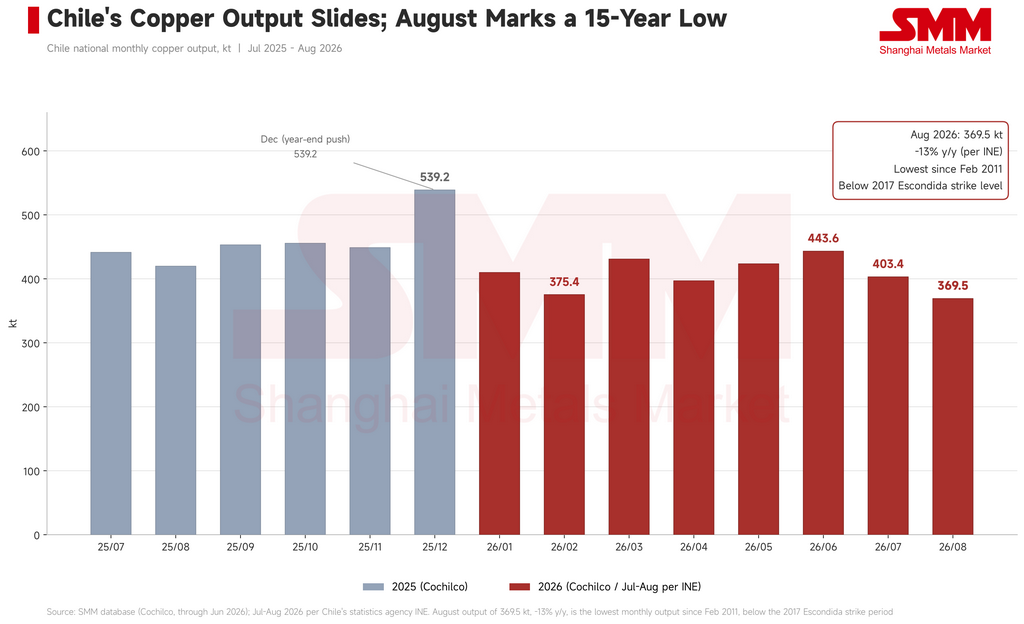
Supply developments in Chile offered additional support. The country’s National Statistics Institute reported August mine copper production of 369,500 tonnes, down about 13% year on year. Cochilco’s figures, which bear more directly on refined copper supply, showed January–July refined production of 889,500 tonnes, down 10.4%. Labour negotiations at Centinela and Escondida add to uncertainty over subsequent mine output, particularly if either dispute disrupts operations.
Demand-side
Near-term demand looks less firm. Restocking ahead of the National Day and Mid-Autumn Festival holidays has ended, while high prices and steep backwardation are discouraging downstream purchases. More fabricators also paused production during the extended break. As the market moves towards its seasonal demand lull, buyers are likely to focus on immediate requirements. The AI investment theme has not disappeared. Expectations of higher copper use in future infrastructure projects helped support prices before the holiday. During the break, however, Hong Kong-listed AI stocks generally declined while US AI-related stocks broadly rose. Given that divergence, the early weakness in copper cannot be convincingly attributed to a broad retreat in AI-related equities.
Outlook
The minutes of the Fed’s September meeting, due early on October 8 Beijing time, may clarify how officials are weighing slower hiring against inflation. A renewed oil-price rally would be a risk for copper if it pushed inflation expectations and US Treasury yields higher. For the physical market, the immediate questions are whether the Centinela and Escondida negotiations affect production, how quickly Chinese inventories build, and how much copper fabricators buy once operations resume. With LME stocks still falling and Chinese stocks expected to rise, LME copper is likely to hold up better than SHFE copper. The scale of China’s post-holiday inventory build and the recovery in downstream purchasing will be the clearest tests of that view.
Currency conversion for the SHFE price: US$1 = RMB 6.7046 on October 7, 2026. The original RMB quotation is retained above.