

SMM ANALYSIS | GLOBAL COPPER
What Could a Cobre Panamá Restart Mean for Global Copper Supply?
Panama’s latest recommendation to negotiate a new operating framework has revived the prospect of fresh mining at one of the world’s largest copper assets. Historical output shows why the mine matters, but current stockpile processing should not be confused with a full restart.
5 October 2026 | SMM Analysis
|
330.9 kt Cobre Panamá 2023 copper output Production halted in November |
46.8% Share of FQM 2023 copper output SMM calculation |
70 kt Recoverable copper in stockpile First Quantum estimate |
A Panamanian government commission has recommended opening formal negotiations with First Quantum Minerals on a new framework for Cobre Panamá. The September 30 recommendation envisages renewed operations under new conditions that would also fund a long-term, phased closure. President José Raúl Mulino has not yet approved a restart, meaning the recommendation should be viewed as a potential pathway rather than a final reopening decision.
The distinction matters for the copper market. Cobre Panamá was producing more than 330,000 tonnes of copper annually before operations stopped in November 2023 and was responsible for around 1% of global copper production at the time of closure. A return of fresh mine production would therefore be material to global supply, but the timing and scale of any restart remain subject to political, legal and operating conditions.
|
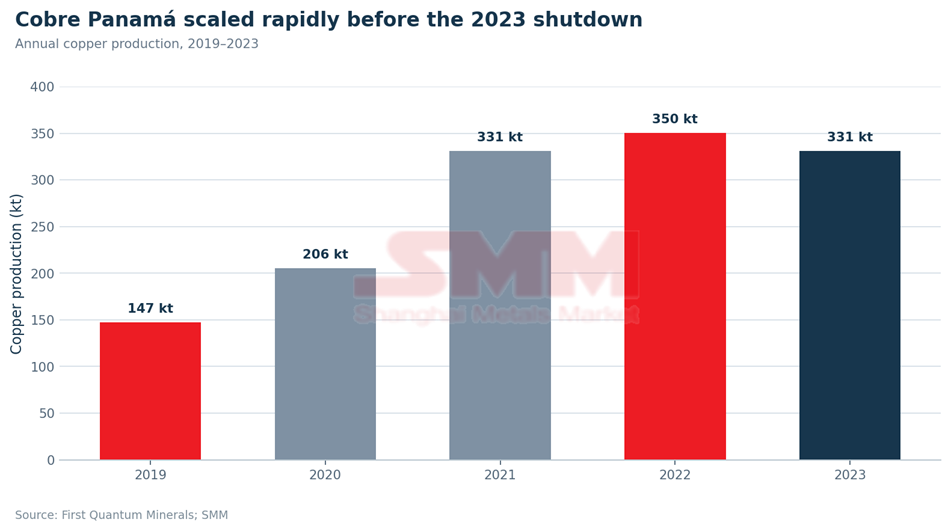
Historical production shows the scale of the suspended supply |
Cobre Panamá moved from ramp-up to large-scale production in only a few years. First Quantum reported 147.5 kt of copper production in 2019, including pre-commercial output, rising to 205.5 kt in 2020 and 331.0 kt in 2021. Production reached a record 350.4 kt in 2022 before easing to 330.9 kt in 2023 as operations were halted in November.
The 2023 figure is particularly notable because it was achieved despite the mine being unable to operate for the full year. This historical range provides a useful indication of Cobre Panamá’s potential supply significance, although it should not be interpreted as an immediate post-restart forecast.
|
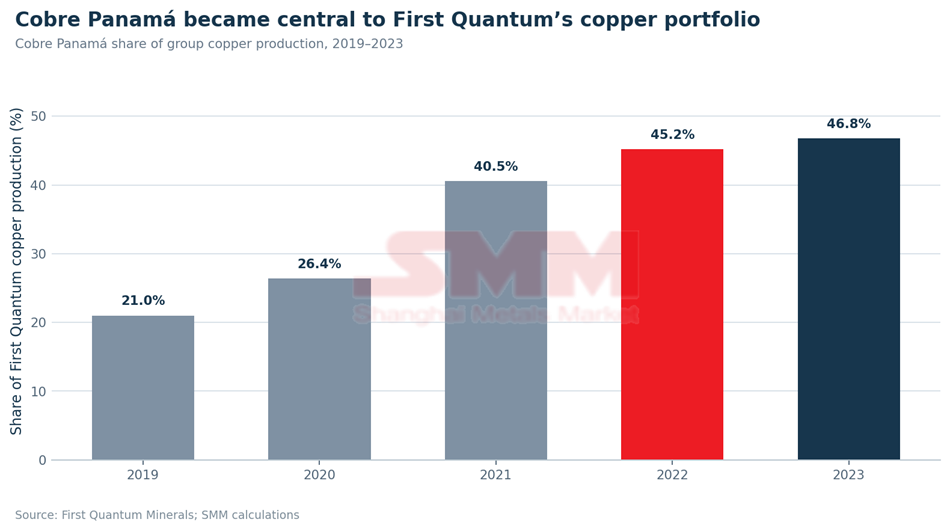
The mine had become central to First Quantum’s copper portfolio |
Cobre Panamá’s importance was not limited to global supply. The mine also became First Quantum’s single largest copper contributor. Its share of group copper production rose from about 21.0% in 2019 to 26.4% in 2020, 40.5% in 2021 and 45.2% in 2022. In 2023, Cobre Panamá accounted for approximately 46.8% of First Quantum’s total copper production, based on SMM calculations from company data.
That concentration helps explain why the closure materially changed First Quantum’s production profile and why a negotiated restart would be strategically important to the company. It also means that any return of fresh mining would affect not only global copper supply but the balance of First Quantum’s own asset portfolio.
|
Stockpile processing is testing the plant, but it is not a mine reopening |
Cobre Panamá has already resumed limited processing activity in 2026, but this should be separated from the question of restarting mining. Panama authorised the removal, processing and export of ore that had been mined before the 2023 suspension. First Quantum estimates the stockpile at approximately 38 million tonnes containing around 70,000 tonnes of recoverable copper.
The first milling circuit was restarted in May 2026. During Q2, the operation processed approximately 2.1 million tonnes of stockpiled ore at an average grade of 0.23% Cu and a recovery rate of 67%, producing 3,216 tonnes of copper. First Quantum maintained 2026 guidance of 30–40 kt of copper from stockpile processing, with the remaining recoverable metal expected to be processed in 2027.
This programme demonstrates that parts of the processing complex can be recommissioned after the prolonged shutdown, while also rebuilding workforce and supply-chain capability. However, no new extraction, drilling or blasting is permitted under the stockpile programme. For the copper market, current output is therefore temporary inventory conversion rather than a return of mine supply.
|
Cobre Panamá: operating and restart reference points |
|
Indicator |
Latest / historical figure |
|
2023 copper production |
330.9 kt |
|
Record annual copper production |
350.4 kt (2022) |
|
Mineral reserve (Dec. 31, 2024) |
2.73 Bt at 0.38% Cu |
|
Current stockpiled ore |
~38 Mt |
|
Recoverable copper in stockpile |
~70 kt |
|
2026 stockpile-processing guidance |
30–40 kt Cu |
|
Q2 2026 stockpile output |
3,216 t Cu |
|
Current fresh-mining status |
Suspended; no restart decision |
|
Latest policy development |
Commission recommends negotiations on a new framework |
|
A restart could return material supply, but the path is unlikely to be immediate |
Historical production suggests that a fully operating Cobre Panamá could ultimately return several hundred thousand tonnes of annual copper supply. At its 2022–2023 operating rate, the mine contributed roughly 330–350 kt per year. That scale would be meaningful in a market where new large copper mines are difficult to permit, finance and build.
However, the September commission recommendation does not yet provide a restart date, operating agreement or production schedule. Any new framework would have to resolve the legal structure under which the mine operates, establish acceptable economic and environmental terms, address outstanding disputes and maintain political legitimacy after the controversy that led to the 2023 shutdown.
Operationally, the stockpile programme provides useful evidence on plant readiness, but it is being run on previously mined material and at lower grades than the mine’s historical reserve grade. A transition from stockpile processing to fresh ore would require the mining fleet, pits, waste movement, drilling and blasting systems, contractors and supporting supply chains to be remobilised. As a result, historical output should be treated as an indication of potential scale rather than a near-term supply assumption.
|
SMM outlook |
For the remainder of 2026, the copper contribution from Cobre Panamá is likely to be defined primarily by the stockpile-processing programme rather than a full mining restart. First Quantum’s 30–40 kt guidance for 2026 is small relative to the mine’s historical annual production but is still relevant because it introduces additional concentrate into the market after more than two years without normal mine output.
The more important supply question moves into 2027. If negotiations between Panama and First Quantum produce an acceptable new framework, the market will begin to focus on the sequencing of fresh-mining activities, the time required to remobilise the mine and the shape of any production ramp-up. A negotiated agreement would therefore improve the medium-term copper-supply outlook before it necessarily changes physical mine supply immediately.
A phased restart would be the more prudent base case than an immediate return to the 330–350 kt annual rates achieved before closure. The current processing campaign can help restore plant familiarity, rebuild staffing and reconnect supply chains, but the mining side of the operation has remained suspended since November 2023. The longer that suspension persists, the more important workforce readiness, mobile-equipment condition, mine planning and contractor mobilisation become to the restart schedule.
From a global-market perspective, Cobre Panamá remains one of the few suspended assets capable of adding copper supply on a scale comparable with a major new mine without requiring construction of an entirely new processing complex. That gives the negotiations unusual importance at a time when the industry is seeking additional mine supply. Nevertheless, SMM considers it important to distinguish between three separate stages: temporary stockpile processing, a political and legal agreement to permit fresh mining, and the subsequent physical ramp-up of mined production.
If a restart framework is agreed and execution proceeds smoothly, Cobre Panamá could re-emerge as a material source of copper concentrate and gradually reduce part of the supply gap created by its 2023 closure. If negotiations stall, the current stockpile will eventually be depleted and the operation could again contribute little or no copper. The direction of Panama’s negotiations, rather than the current stockpile programme alone, will therefore be the key indicator for the mine’s longer-term impact on global copper supply.



