September TiO2 production rebounded with inventory destocking, prices stable with slight improvement
In September 2026, China's TiO2 production rebounded 0.09% MoM. Coupled with pre-holiday phased restocking, enterprise inventory destocked by 4.8%, and industry fundamentals saw a modest recovery. On the pricing front, the market remained broadly stable, with divergence emerging across product categories: as of September 30, the average price of rutile TiO2 stood at 13,650 yuan/mt, while anatase TiO2 averaged 12,500 yuan/mt. Chloride-process TiO2 was quoted at 16,050 yuan/mt, edging down 0.62% MoM, while sulphate-process product quotes remained largely unchanged. However, this round of inventory destocking was driven more by phased pre-holiday demand, with insufficient growth in sustained end-use orders. The industry's upward momentum remained weak, limiting room for a market rebound.
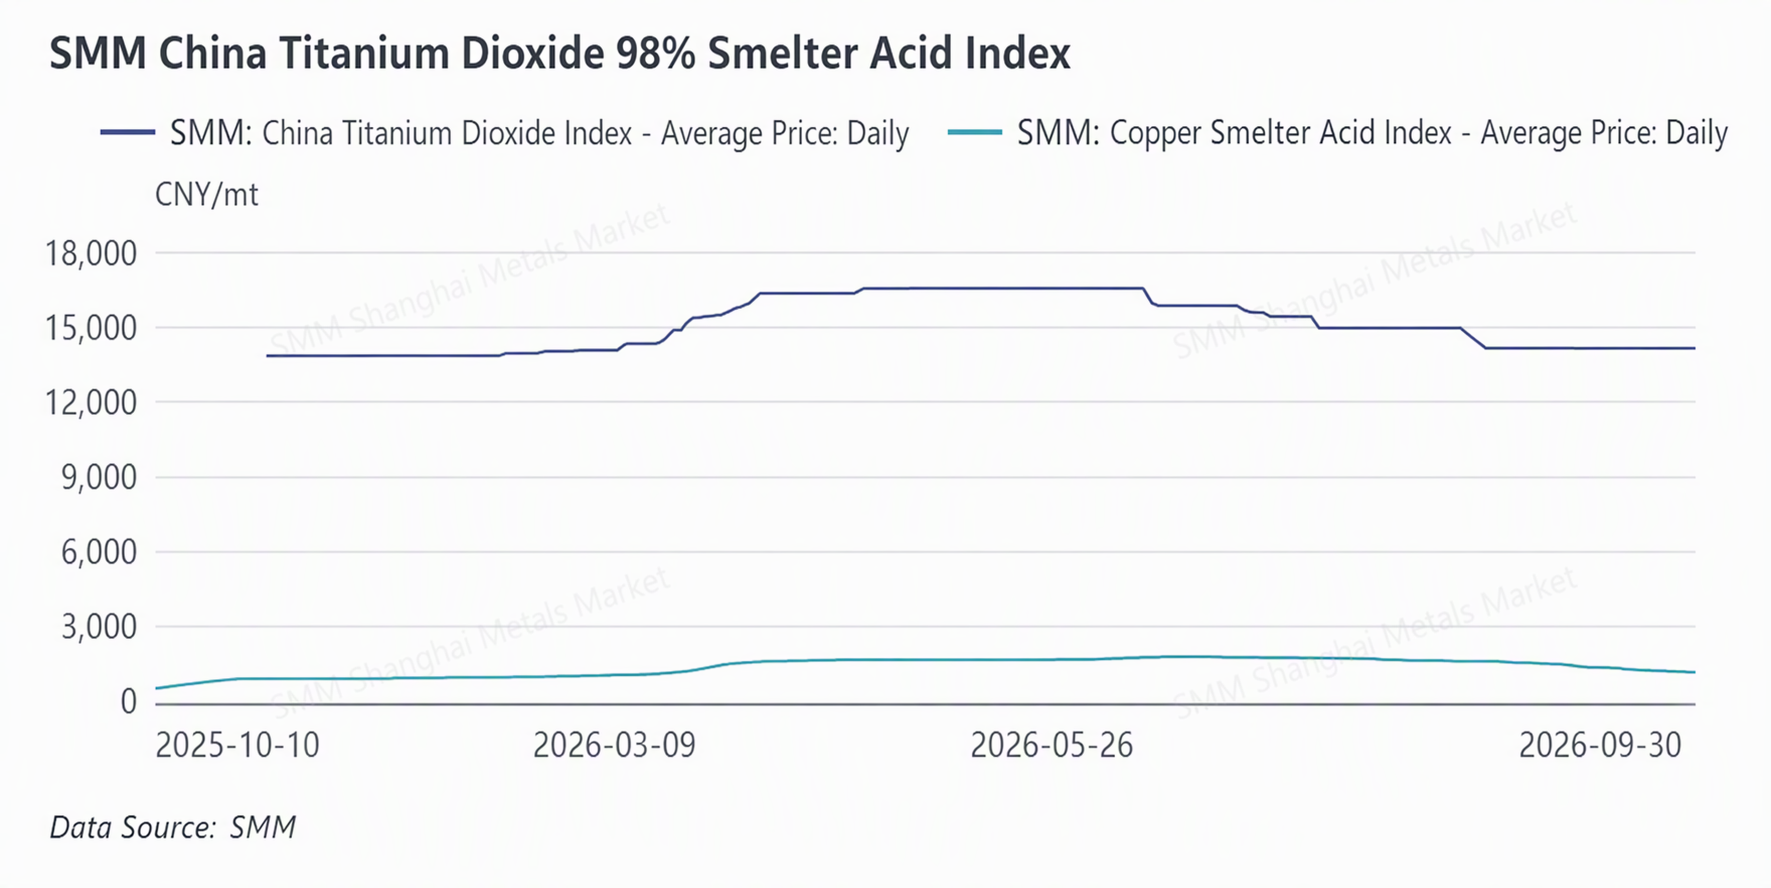
The TiO2 market remained broadly stable in September. Since the start of September, TiO2 enterprises have issued price increase letters in a concentrated manner, effectively boosting overall market sentiment. Combined with the traditional "September peak season" effect, manufacturers' order-taking performance improved compared with the earlier period. The supply side showed clear divergence: driven by market recovery and improved orders, some previously idled or production-cutting enterprises resumed operations. However, some manufacturers remained in production cut or suspension mode due to weak orders, low selling prices, equipment maintenance, and loss pressures. With these factors offsetting each other, the industry's overall operating rate and production rose only slightly, and the market supply landscape remained broadly stable.
On the demand side, before the price increase letters were released, downstream clients engaged in advance stockpiling, driving a recovery in factory orders. Coupled with the arrival of the Mid-Autumn Festival and National Day holidays, downstream buyers, having depleted their earlier inventories, launched a concentrated round of restocking purchases, boosting TiO2 enterprises' order intake and helping to digest inventory. Meanwhile, profitability divergence within the industry became more pronounced: chloride-process TiO2 profitability was relatively strong, with some supply even tightening, but performance was uneven across enterprises, and a few manufacturers still faced high inventory pressure due to insufficient production-sales matching. Approaching the dual holidays, most factories focused on scheduling and delivering existing orders, and new purchasing enthusiasm in the market pulled back somewhat.
On the raw material side, titanium concentrate and sulphuric acid prices continued to weaken, providing insufficient cost support. Going forward, if order follow-through slows and the destocking pace decelerates, upward momentum in TiO2 prices will be constrained, and the risk of renewed price weakness cannot be ruled out. In the short term, the market is likely to remain broadly stable, with the trend depending on post-holiday new order realization and actual transaction prices. Over a longer horizon, industry growth will still hinge on the strength of China's end-use demand release and whether exports can continue to provide effective support.
Sponge titanium September peak season expectations fell short; Q4 market likely to consolidate on a weak note
In September 2026, SMM China sponge titanium production rose 1.88% MoM. Cumulative production from January to September reached 228,500 mt, up 14.53% YoY. On the pricing front, as of September 24, Grade 0 sponge titanium closed at 44,000-45,000 yuan/mt, with an average price of 44,500 yuan/mt, holding stable for the month.
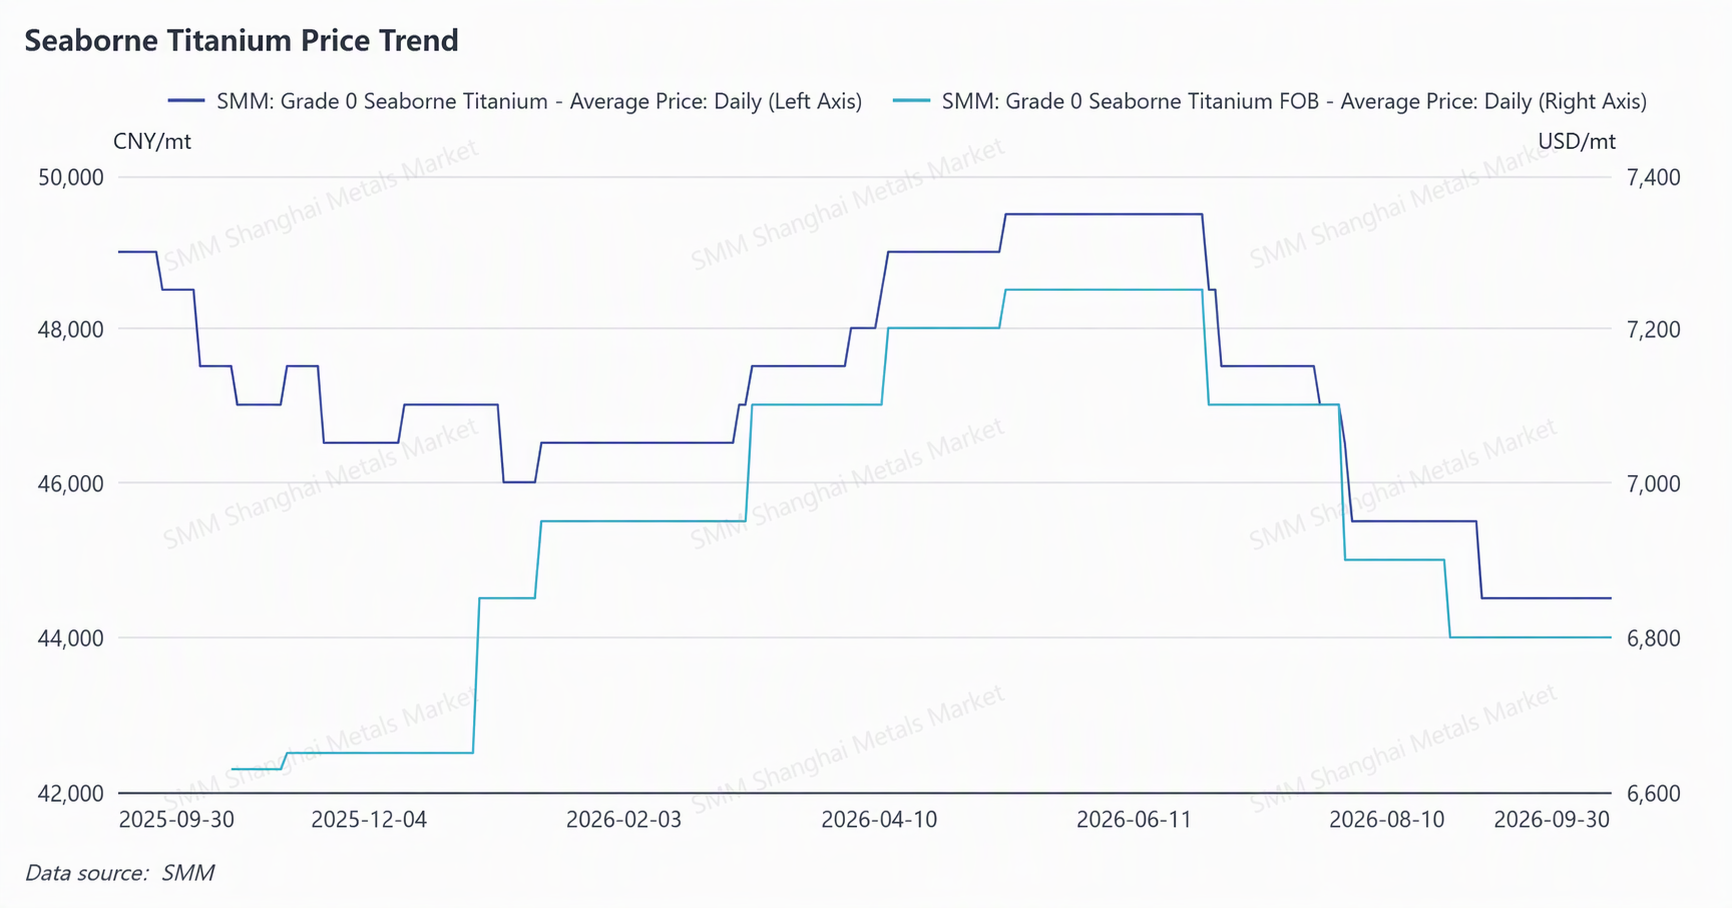
The sponge titanium market's "September peak season" expectations failed to materialize in September. On the demand side, domestic trade demand for titanium materials saw steady release in September, but due to the large inventory overhang accumulated in H1, downstream raw material purchasing progressed at a slower pace. Additionally, tighter export controls and the traditional industry off-season weighed on titanium product export orders this year. On the supply side, northern titanium enterprises gradually advanced new capacity, and with maintenance-hit facilities resuming operations one after another, national sponge titanium production rose steadily in H2. Against a backdrop of weak and stable demand, raw material suppliers engaged in involution-driven selling, with quotes largely stalemated near 44,000 yuan/mt. Currently, market confidence in Q4 sponge titanium prices is insufficient, with new domestic trade demand projects still unclear and export orders unstable. However, as smelting cost support gradually emerges, Q4 2026 sponge titanium market prices are expected to consolidate on a weak note.
Titanium materials: In September, civilian titanium materials largely consolidated on a weak note. Meanwhile, titanium material producers offered price cuts and sales promotions depending on clients and order volumes, but high-end products such as aerospace, medical, and 3D printing titanium powder maintained firm prices, with a price spread versus civilian titanium materials.
Looking ahead, the titanium industry's "September peak season" has concluded, with peak-season performance falling short of expectations, and market expectations for "October peak season" demand release have cooled notably. Upstream titanium concentrate continued to weaken, making it difficult for raw materials to support an industry chain rebound. Downstream traditional domestic demand growth for TiO2 and titanium materials remains limited, with some segments still facing demand contraction pressure, leaving industry growth more reliant on export-driven momentum. Although exports achieved growth this year, uncertainty remains over whether overseas end-use demand can continue to expand at scale. On balance, the short-term titanium market is likely to maintain a narrow sideways consolidation pattern.