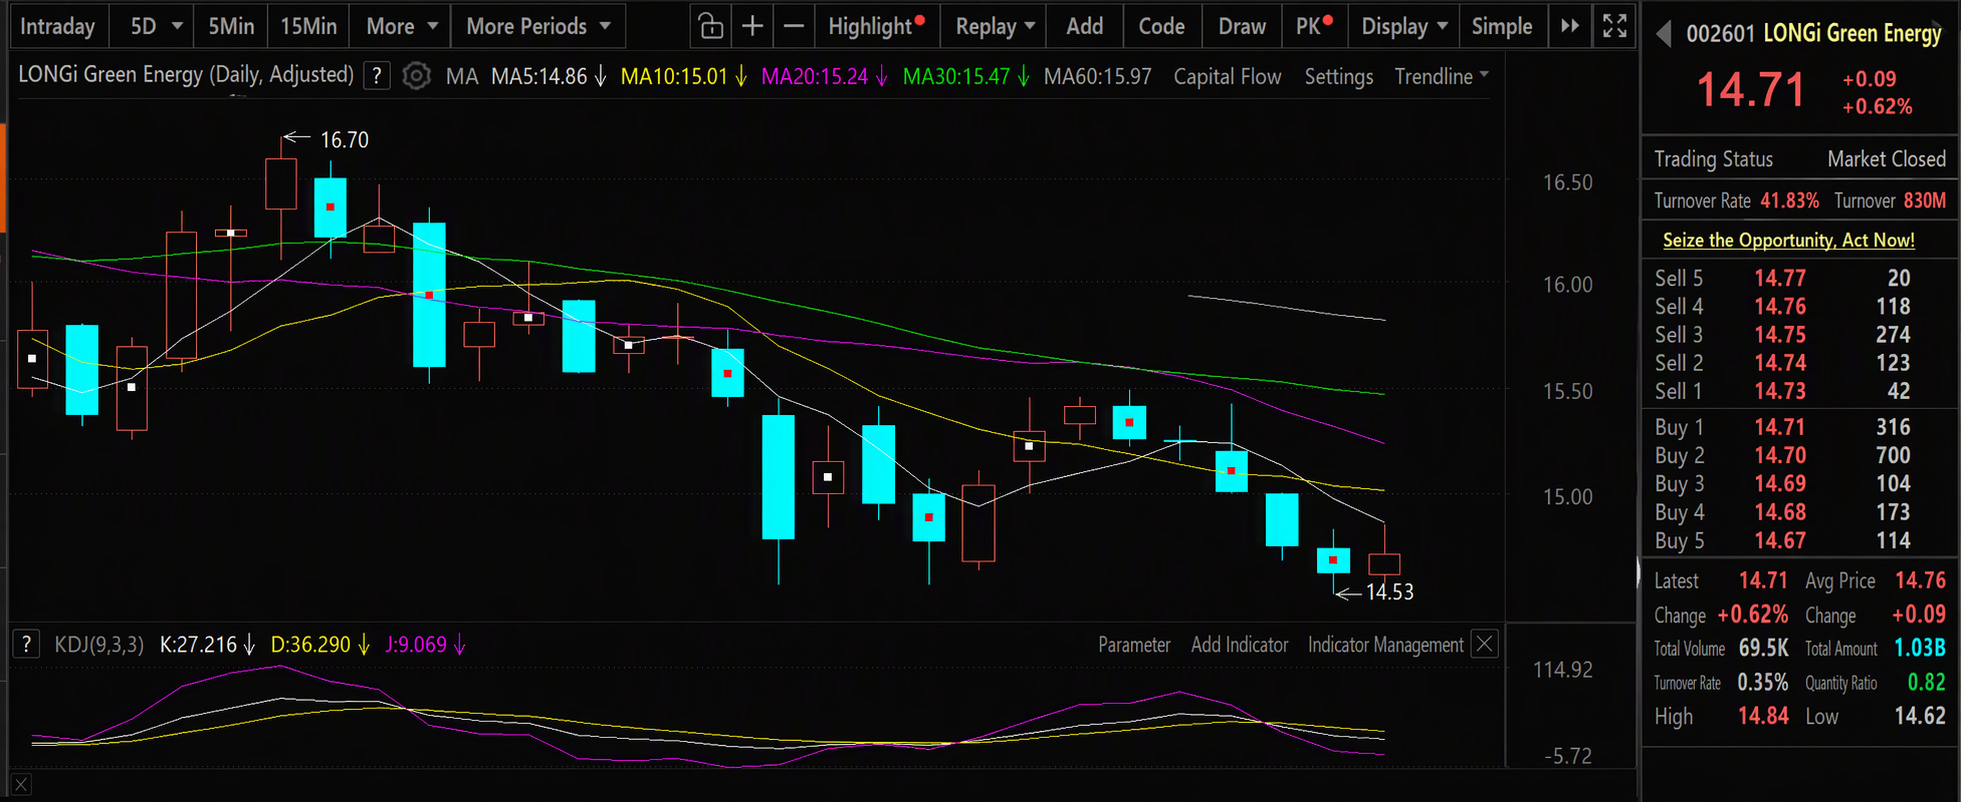
On September 30, LB Group's share price rose, closing up 0.62% at 14.71 yuan per share on September 30.
In terms of news, LB Group recently announced: Titanium concentrate is the key raw material required for the production of the company's main products, titanium dioxide and titanium sponge. To ensure a stable supply of titanium concentrate raw materials, on September 22, 2026, the company signed a Term Sheet (hereinafter referred to as the "Term Sheet" or "Letter of Intent") with its associate company Image Resources NL (ASX code: IMA, hereinafter referred to as "Image Resources") in Jiaozuo. Under the agreement, the company or a subsidiary designated by the company intends to invest through cash contributions and assets such as machinery and equipment valued as capital contributions, thereby acquiring approximately 80% of the interests in the Durack and Yandanooka mineral sands projects held by Titon Resources Pty Ltd, a wholly owned subsidiary of Image Resources. The mineral sands at Durack and Yandanooka contain elements such as titanium and zirconium, which can be further processed into titanium concentrate and zircon sand after mining and beneficiation. In this transaction, the company's total cash and asset contributions amount to approximately 160 million Australian dollars (approximately 765.6 million yuan), of which the cash contribution is approximately 20 million Australian dollars (approximately 95.7 million yuan), and machinery and equipment and other assets are valued at approximately 140 million Australian dollars (approximately 669.9 million yuan) through negotiation.The specific forms of investment in this transaction include acquiring part of the equity of the project company, or establishing an unincorporated joint venture (UJV) for the target projects. The two parties will determine the final transaction structure through negotiation, taking into account legal, regulatory, tax, and commercial factors. This transaction still requires completion of due diligence and valuation, signing of the final transaction agreement, and obtaining approval from both companies and regulators including the FIRB (Foreign Investment Review Board). The transaction consideration and equity ratio have not yet been finalized.
Regarding the basic situation of the target projects, LB Group stated: The target projects are the Durack and Yandanooka mineral sands projects located in Western Australia, held by Image Resources NL through its wholly owned subsidiary Titon Resources Pty Ltd. The aforementioned projects are located in the North Perth Basin, approximately 300 kilometers north of Perth, Western Australia. As of September 2026, according to the JORC (2012) standard, the Durack mine has a resource of 37.7 million tonnes with a heavy mineral grade of 2.2%, and the Yandanooka mine has a resource of 57 million tonnes with a heavy mineral grade of 3.1%. The Durack and Yandanooka projects plan to produce heavy mineral concentrate (HMC) through mining and beneficiation, with valuable minerals consisting mainly of zircon and titanium minerals (ilmenite, rutile, leucoxene), along with a small amount of monazite. Currently, both the Durack and Yandanooka mineral sands projects have obtained exploration permits, but have not yet received mining permits, nor have mining operations commenced.
Regarding other arrangements involving related-party transactions, LB Group announced: Upon completion of this transaction, the company will hold approximately 80% interest in the target projects, with Image Resources retaining approximately 20%. The company will arrange project company governance and staffing accordingly based on the final transaction structure. Upon completion of this transaction, it will not result in non-operating capital occupation of the company by the controlling shareholder, actual controller, or other related parties.
Regarding the purpose of the transaction and its impact on the publicly listed firm, LB Group stated: This transaction is an important initiative in the company's strategy of actively expanding resource deployment outside China.It will help the company acquire high-quality mineral sands resources overseas, ensure the long-term stable supply of upstream raw materials for the titanium dioxide and zirconium industry chains, and enhance the company's resource security capability and core competitiveness. The funding sources for this transaction are the company's own funds or self-raised funds and physical assets, and it will not have a material adverse impact on the company's current financial position and operating results. This agreement is an indicative arrangement, and the signing of this agreement itself will not have a material impact on the company's current financial position and operating results.
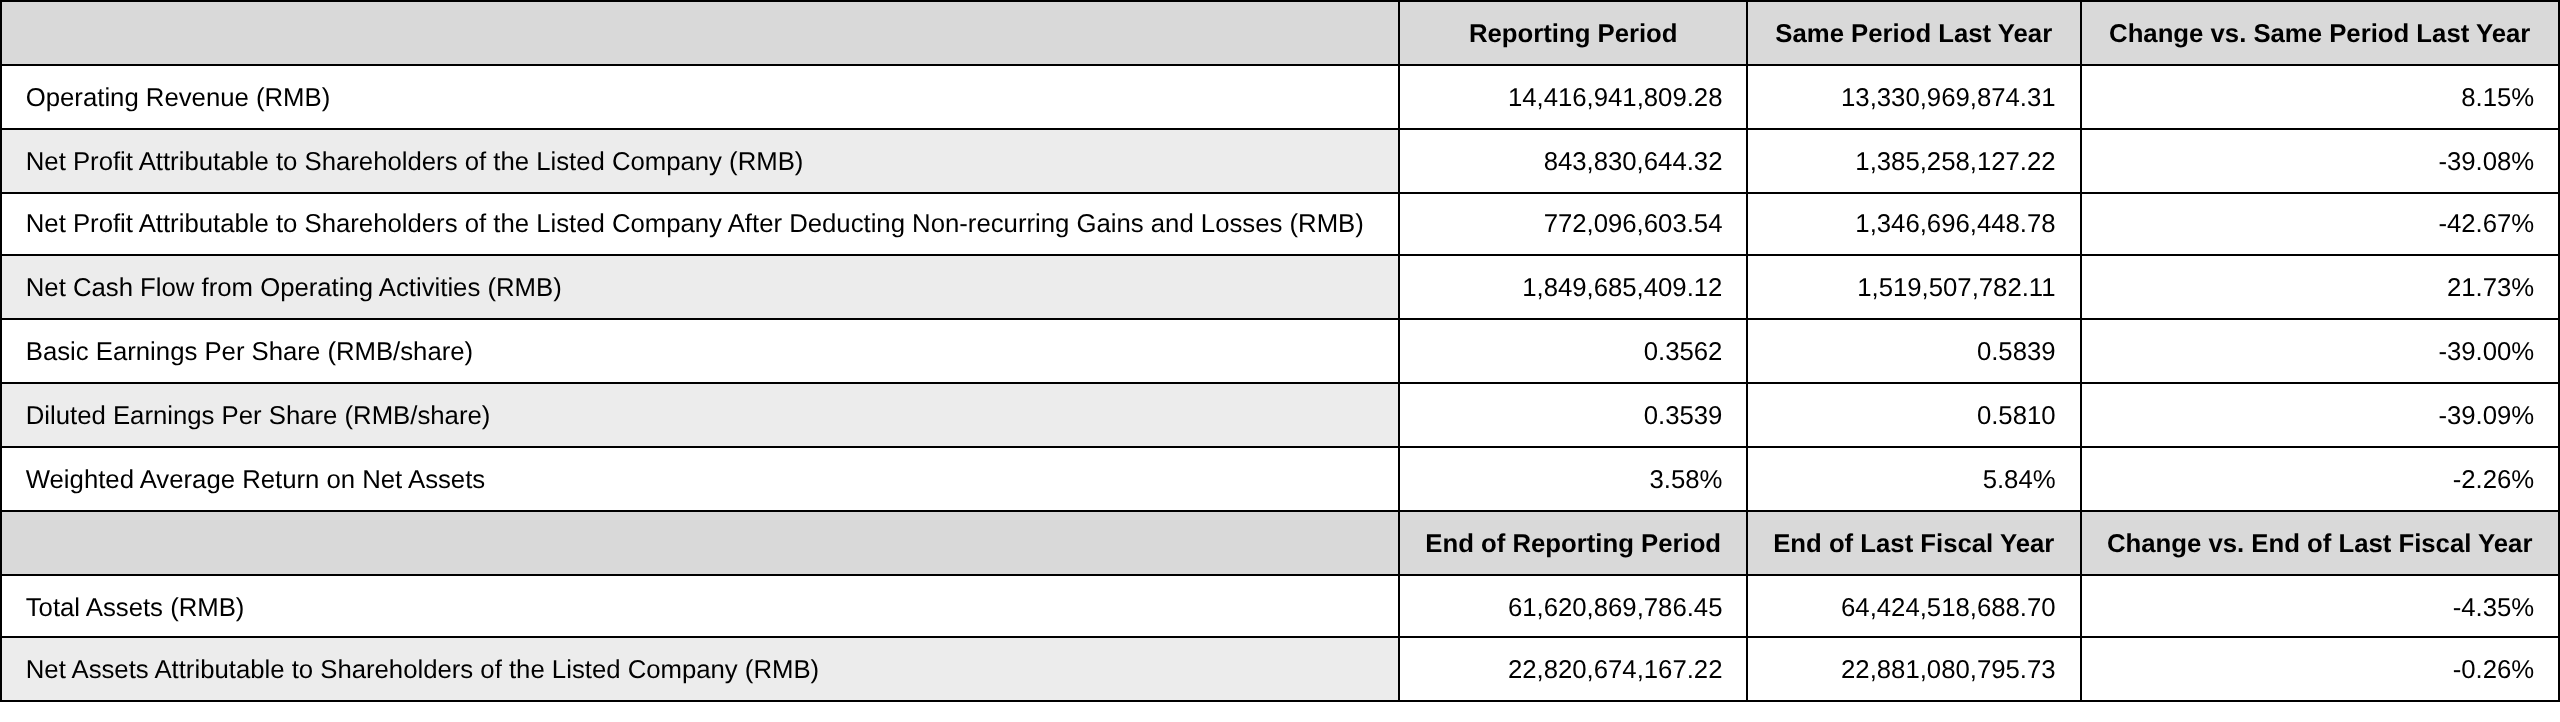
In terms of performance: LB Group released its 2026 semi-annual report, showing that the company achieved operating revenue of 14.417 billion yuan, up 8.15% YoY; total profit of 1.145 billion yuan, down 31.53% YoY; and net profit attributable to shareholders of the publicly listed firm of 844 million yuan, down 39.08% YoY. During the reporting period,net profit declined compared with the same period last year, mainly due to sharp increases in sulphur and sulphuric acid raw material prices, slow downstream pass-through of titanium dioxide prices, lower mineral product production, and exchange gains and losses.
In its semi-annual report, LB Group stated: 2026 marks the first year of the group's "15th Five-Year Plan" period. The group firmly anchored itself to market orientation, deepened innovation and reform, and actively responded to challenges such as global economic fluctuations and intensifying industry competition, driving the group's operations forward steadily. Titanium dioxide production and sales: In H1 2026, titanium dioxide production was 657,500 mt, down 3.62% YoY; total titanium dioxide sales were 685,600 mt, up 12.02% YoY, of which domestic sales accounted for 38.33% and international sales accounted for 61.67%. Titanium sponge production and sales: In H1 2026, titanium sponge production was 35,000 mt, down 3.28% YoY, and titanium sponge sales were 38,100 mt, down 1.55% YoY. Other products: In H1 2026, iron ore concentrates production was 703,300 mt, down 55.21% YoY; iron ore concentrates sales were 708,700 mt, down 55.20% YoY; titanium ore concentrates production was 448,900 mt, down 35.12% YoY, all for internal use; iron phosphate production was 62,600 mt, up 36.78% from the same period last year, and iron phosphate sales were 60,700 mt, up 57.59% from the same period last year.
Regarding the company's main businesses during the reporting period, LB Group's semi-annual report shows: The company is headquartered in the Western Industrial Agglomeration Area of Jiaozuo, Henan. It is a large diversified enterprise group dedicated to R&D and manufacturing of new materials and deep industrial integration. It is currently mainly engaged in the production and sales of titanium dioxide, titanium sponge, zirconium products, lithium battery cathode and anode materials, and other products. The company's products are sold to more than 110 countries and regions across six continents. Upholding the corporate mission of "creating a better titanium life and being a respected enterprise," the company has explored the titanium and titanium-related industries for more than 30 years. Relying on technological innovation and an efficient operating model, it continuously enhances the industry's ability to serve human society. The company's main products are titanium dioxide, titanium sponge, zirconium products, and lithium battery cathode and anode materials. Among them, titanium dioxide capacity is 1.66 million mt/year and titanium sponge capacity is 80,000 mt/year, both ranking first globally. The company's titanium industry bases are distributed across six cities in five provinces, including Henan, Sichuan, Hubei, Yunnan, and Gansu. It has formed a green industry chain from titanium mineral mining and processing, to titanium dioxide and titanium metal manufacturing, and derivative comprehensive utilization of resources. Non-metallic zirconium products are operated by the company's controlling subsidiary Orient Zirconic (stock code: 002167). For details, please refer to Orient Zirconic's 2026 semi-annual report.
Reviewing the H1 price trend of SMM rutile titanium dioxide shows: The average price of rutile titanium dioxide on June 30 was 15,750 yuan/mt, up 16.67% in H1 compared with the average price of 13,500 yuan/mt on December 31, 2025. Comparing the H1 2026 semi-annual daily average price of rutile titanium dioxide at 15,078.88 yuan/mt with the H1 2025 semi-annual daily average price of 14,375.21 yuan/mt, the semi-annual daily average price rose 4.9%.
According to SMM price data: On September 30, the SMM average price of rutile titanium dioxide was flat compared with the previous trading day.
The titanium dioxide market was generally stable this week. Cost side, titanium concentrates and sulphuric acid prices were in the doldrums, and raw materials did not provide strong cost support. Upward movement relied more on supply-demand dynamics and market sentiment. Supply side, driven by peak season expectations, some titanium dioxide enterprises resumed production and raised output. Producers actively took orders, previously circulating low-priced cargoes were largely absorbed, and bearish sentiment in the market visibly dissipated. As orders were fulfilled, some enterprises digested inventory, and production shifted to scheduled deliveries. However, demand-side improvement was limited. Pre-holiday stockpiling combined with the September-October peak season brought some order growth, but as the two holidays approached, downstream procurement pace slowed, and end-user purchasing remained cautious. Market sentiment has recovered, but actual transactions have not followed through with enough strength, making it difficult for prices to rise quickly. Overall, titanium dioxide prices are expected to remain stable and consolidate in the short term. Whether the market can strengthen further will depend on the actual purchasing volume from downstream after the holiday.
Recommended reading: