Markets had circled noon Beijing time on September 29 as a key checkpoint for a possible U.S. tariff on refined copper. The date was derived from a copper market update submitted by the U.S. Department of Commerce on June 30: applying Section 232’s 90-day timeline would have taken the presidential decision window to September 28, U.S. time.
However, the update was required under the existing copper tariff proclamation and was not explicitly designated as a new formal Section 232 investigation report. The president’s written explanation may also be published after a decision has been made. The absence of an announcement by noon therefore should not be read as confirmation that the tariff proposal has been dropped.
The U.S. had previously considered a 15% tariff on refined copper imports in 2027, rising to 30% in 2028. If the White House leaves that phased tariff schedule on the table without finalizing the details, the policy risk alone could continue drawing global copper into the U.S. through 2027.
Traders looking to capture future dislocations between COMEX and LME prices would continue moving cathode into U.S. exchange warehouses, bonded facilities and commercial storage. This would allow the U.S. to build a sizeable copper stockpile without direct government funding: private traders would absorb the procurement, financing and storage costs. In effect, tariff expectations could turn privately held copper into a de facto strategic reserve.
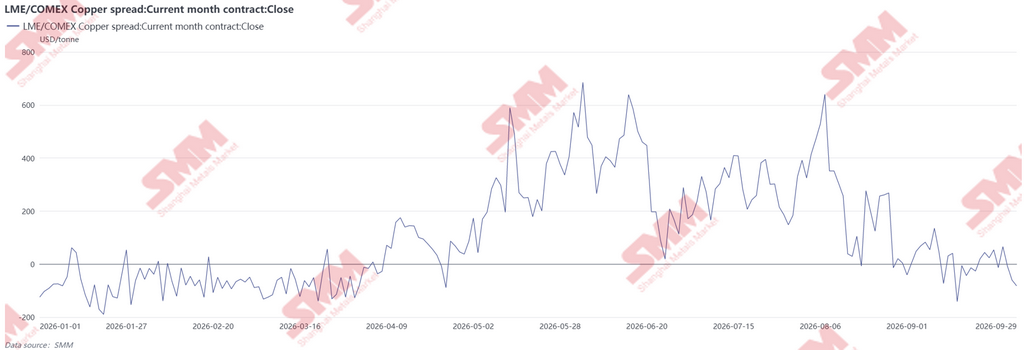
For now, however, the market structure points to a weaker near-term pull. COMEX remains in contango, consistent with ample nearby supply in the U.S., while LME copper remains in backwardation, indicating tighter prompt availability elsewhere. Cross-market spreads have narrowed steadily since late August. The October 2026 COMEX contract traded at a discount of $46.94/mt to LME three-month copper, while the November 2026 contract carried a premium of just $38.99/mt. Neither spread is sufficient to cover freight, financing, storage and exchange-delivery costs, effectively closing the arbitrage window for additional physical shipments into the U.S. If the market had received a firm signal that tariffs were imminent, longer-dated COMEX premiums would likely have widened sharply. That has not happened. The current spread structure suggests that the U.S. pull on global copper is losing momentum and that traders remain unconvinced about the significance of the end-September deadline.
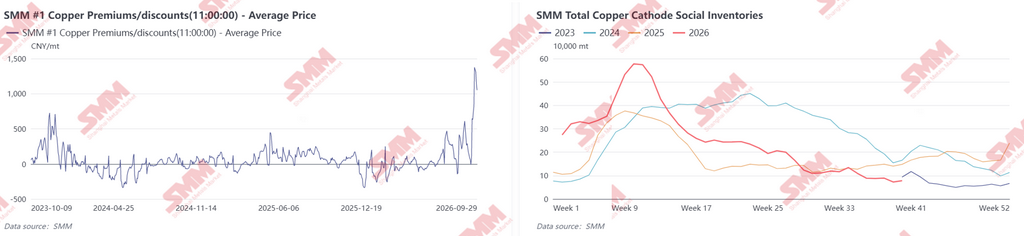
The resulting regional imbalance is already visible in China’s physical market. The SMM #1 copper cathode premium recently approached approximately $205/mt (RMB 1,400/mt), its highest level since October 2023. This rise cannot be attributed to stronger consumption alone. Section 232 tariff expectations have redirected copper towards the U.S., reducing LME stocks in Asia and limiting the volume of imported cathode available to China. Domestic supply has tightened accordingly, with SMM-tracked social inventories falling to a multi-year low of 78,300 mt. Tradable recycled copper feedstock has also become scarce, weakening its ability to substitute for refined copper. At the same time, Chinese fabricators accelerated procurement and restocking ahead of the Mid-Autumn Festival and National Day holidays. The global diversion of copper towards the U.S. provided the underlying support for higher spot premiums, while pre-holiday buying acted as the immediate catalyst.
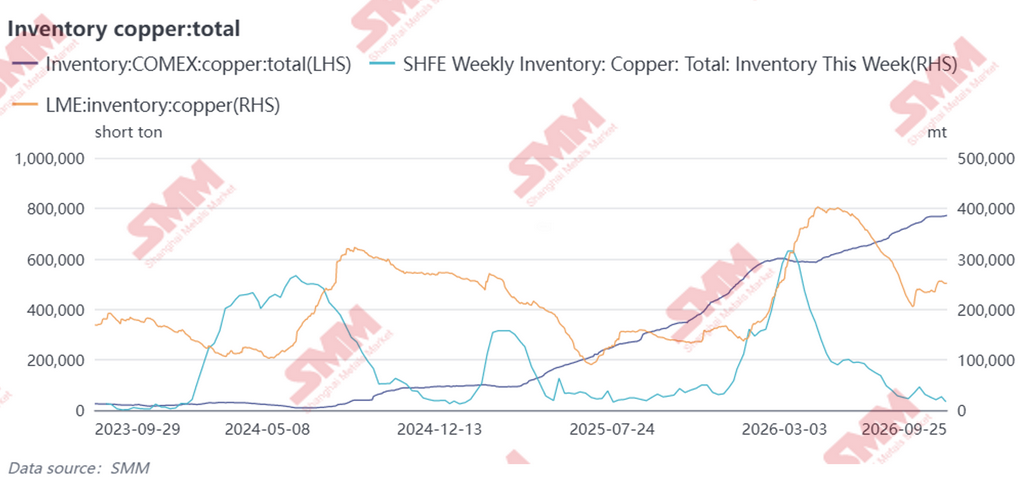
Inventory movements illustrate the scale of the shift. Between September 2025 and September 2026, COMEX copper stocks rose from approximately 320,000 short tons to nearly 770,000 short tons, more than doubling within a year. Over the same period, LME inventories fell from an interim peak of about 400,000 mt in April 2026 to roughly 250,000 mt. SHFE stocks declined even more sharply, from 359,100 mt at the end of March to 47,100 mt on September 24. The direction of travel is clear. Tariff expectations and earlier COMEX premiums pulled cathode from South America, Africa and other producing regions into the U.S., reducing freely available supply elsewhere. The combination of continued stockbuilding in the U.S. and sustained inventory drawdowns across China and the wider Asian market has been a major driver of the recent surge in Chinese spot premiums.
For the global copper market, delaying a final tariff decision may prolong the regional dislocation rather than unwind it. Even if incremental shipments into the U.S. have slowed, the copper already accumulated there is unlikely to return quickly given the cost of financing, handling and re-exporting the metal. Until the White House clearly steps back from tariffs on refined copper, policy uncertainty will keep those stocks anchored in the U.S. and preserve the prospect of renewed inflows if forward COMEX premiums widen again. That would further tighten available supply outside the U.S. and continue to provide support to global copper prices.
Currency conversion is based on the CFETS central parity rate on September 29, 2026: USD 1 = RMB 6.8166.