SMM, September 24:
During the 2026 Mid-Autumn Festival and National Day holidays, about 60% of the 25 secondary lead sample smelters surveyed by SMM kept their production lines running through the holidays, maintaining normal production, with limited overall impact from production cuts and suspensions.
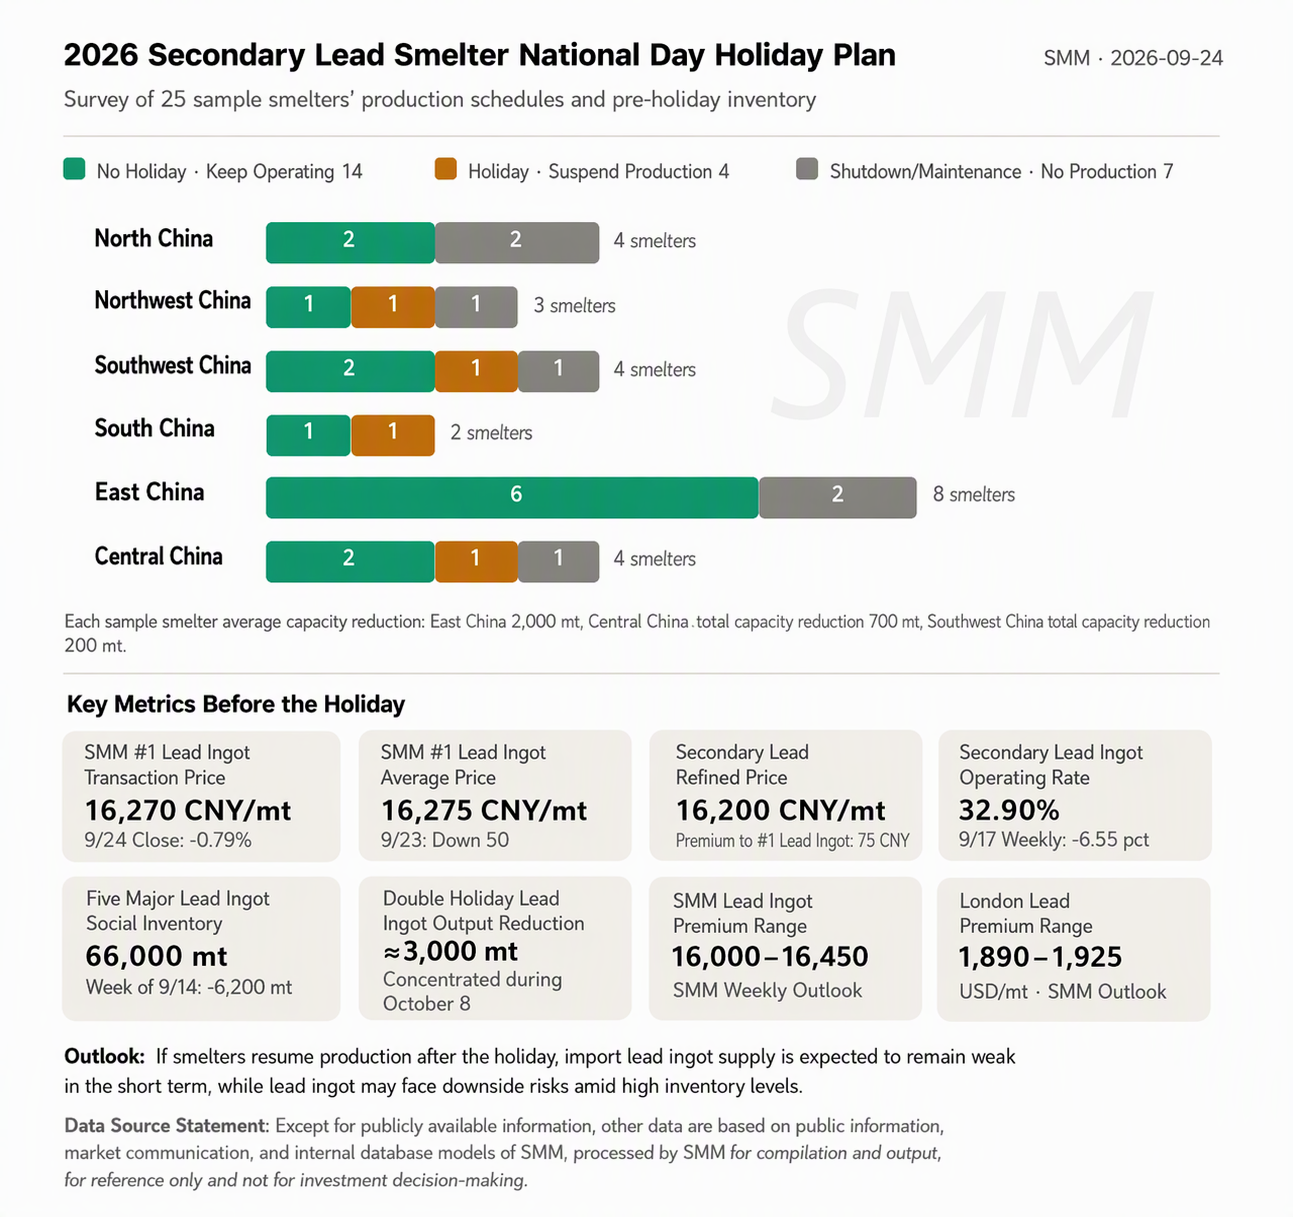
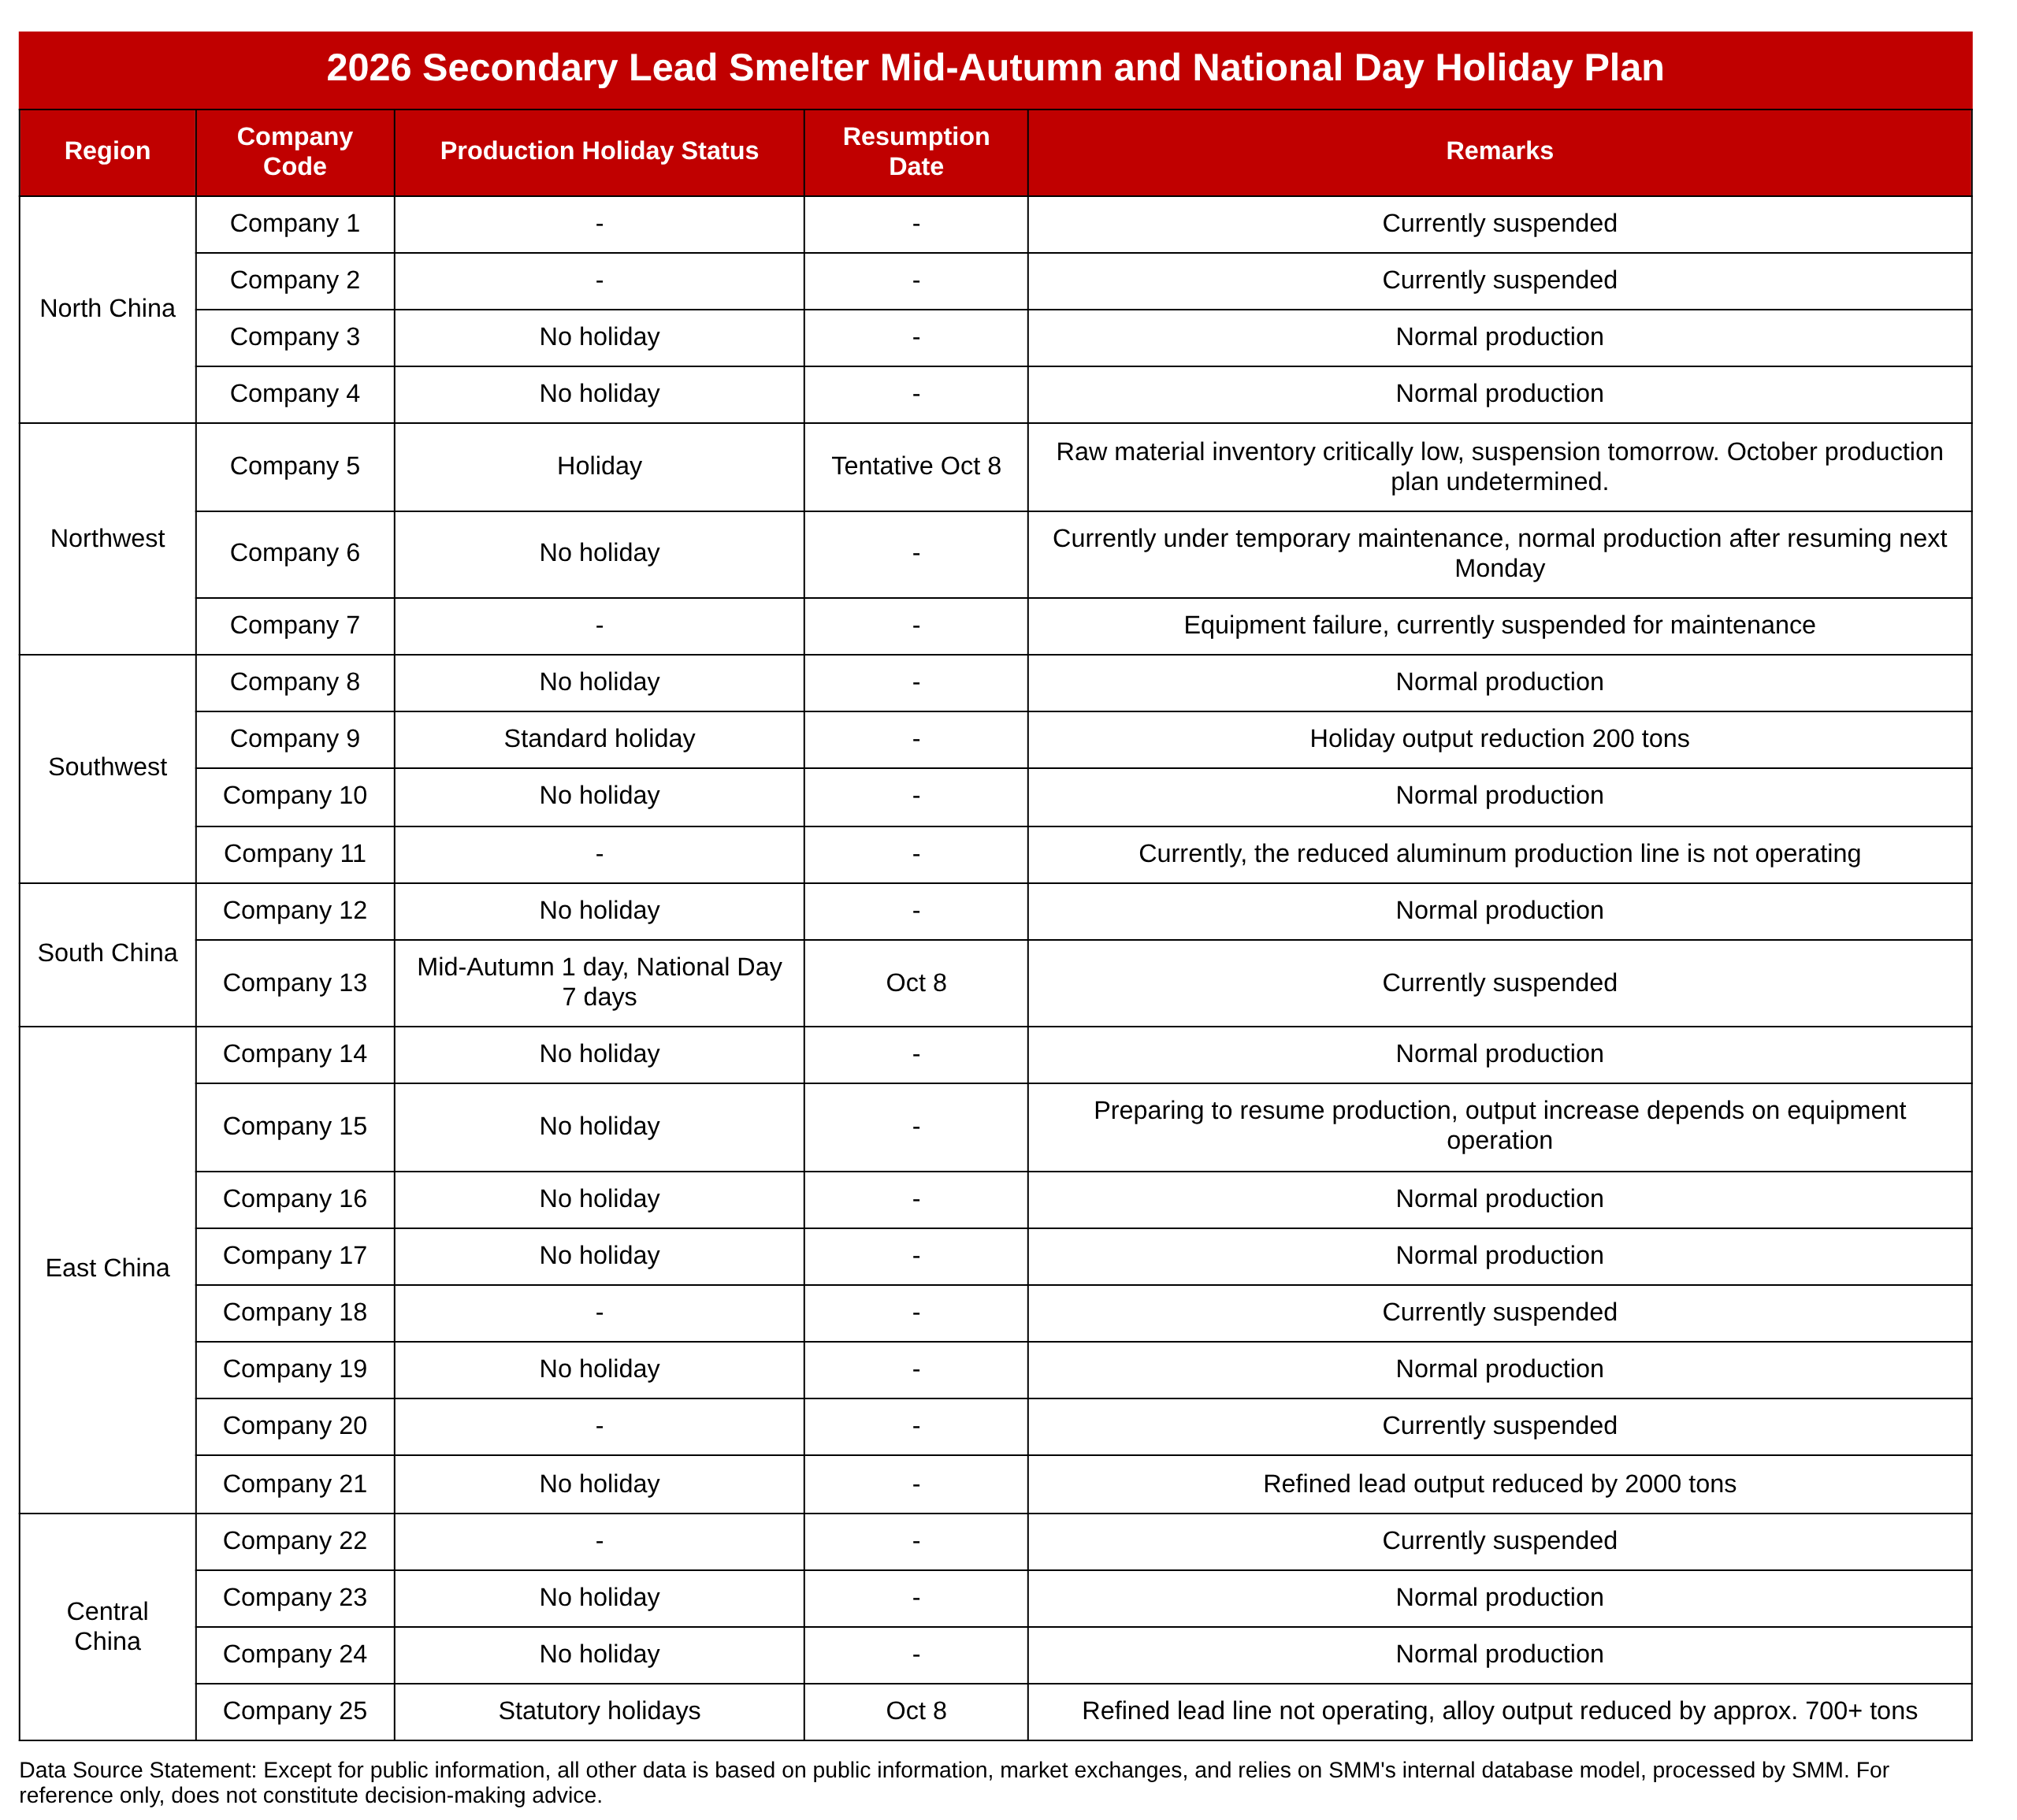
By region: In north China, 2 of 4 smelters maintained normal production, while 2 are currently suspended. In northwest China, 1 of 3 smelters halted production before the holiday due to critically low raw material inventories, tentatively scheduled to resume production on October 8 with the October production plan undecided; 1 will resume work next Monday after temporary maintenance; and 1 is down for maintenance due to equipment failure. In southwest China, 3 of 4 smelters are producing normally, 1 took a normal holiday with output reduced by about 200 mt, and another has its secondary crude lead production line idled. In south China, 1 smelter planned a 1-day break for Mid-Autumn Festival and a 7-day break for National Day, resuming production on October 8. In east China, 5 of 8 smelters did not take holidays, of which 1 planned to cut refined lead production by 2,000 mt, and 2 are currently suspended. In central China, 2 of 4 smelters are producing normally, 1 took statutory holidays and will resume production on October 8 with alloy production expected to fall by over 700 mt, and 1 is currently suspended. Overall, the production loss explicitly attributed to holidays is about 3,000 mt, with resumptions concentrated on October 8.
On the price front, as of September 24, the most-traded SHFE lead contract closed at 16,270 yuan/mt, down 0.79% on the day, showing a first-up-then-down pattern this week. The SMM #1 lead ingot average price stood at 16,275 yuan/mt (September 23), and the secondary refined lead average price was 16,200 yuan/mt, at a discount of 75 yuan/mt to #1 lead. In the week of September 17, the weekly operating rate of secondary lead fell to 32.90%, down 6.55 percentage points WoW. SMM lead ingot social inventory across five regions stood at 66,000 mt (September 23), destocking by 6,200 mt from September 14.
Looking ahead, the contraction in secondary lead supply and destocking of social inventory provide bottom support for lead prices. SMM expects the most-traded SHFE lead contract to trade in the range of 16,000-16,450 yuan/mt in the near term. If smelters resume production en masse after the holiday, imported lead continues to flow in, and downstream cargo pick-up weakens, lead prices face the risk of retreating after a rapid rise. If the scrap battery cost line holds firm and destocking continues, lead prices are expected to continue to consolidate at highs.