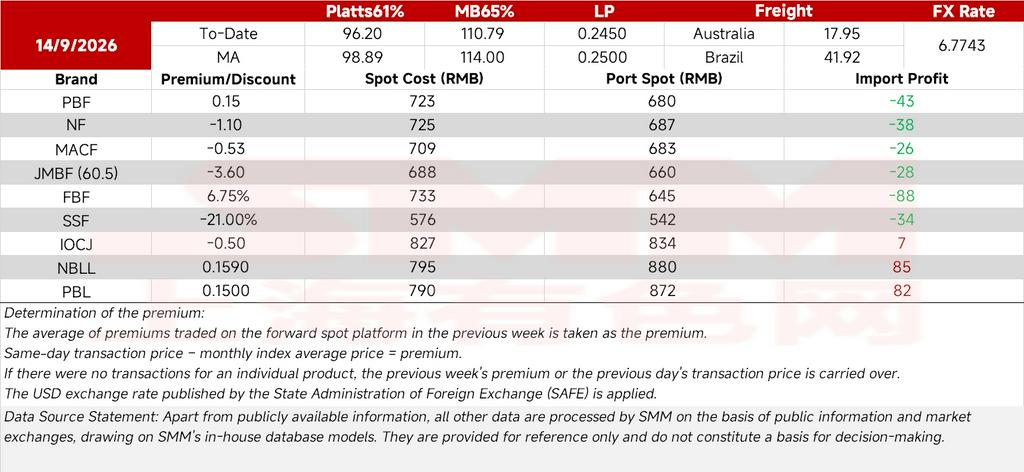
The average imported iron ore margin narrowed further this period, from -1.90 yuan/mt to -9.15 yuan/mt. Spot prices fell sharply and freight costs rose on some routes.
Following the latest round of coke price increases, mill profitability has narrowed further. The market is concerned mills may begin cutting output, which would weigh on iron ore demand. On fundamentals, supply remains comfortable. SMM data showed stocks across 35 major Chinese ports at 143.49 million mt, down 420,000 mt week on week, a smaller draw than in recent weeks. Average daily port outbound volume rose 90,000 mt to 3.235 million mt. On demand, most mills are running at a loss but only a handful have production cut plans, so the actual impact on demand is limited.
On the macro side, tensions in the Middle East continue to build. Houthi forces in Yemen have tightened control around the Bab el-Mandeb Strait, lifting oil prices and trade risk. Expectations of further Federal Reserve rate rises have also strengthened. Together these have reinforced a bearish market outlook and commodities are broadly under pressure. Iron ore prices are likely to stay weak in the near term, driven by news flow and sentiment, with imported margins narrowing further.