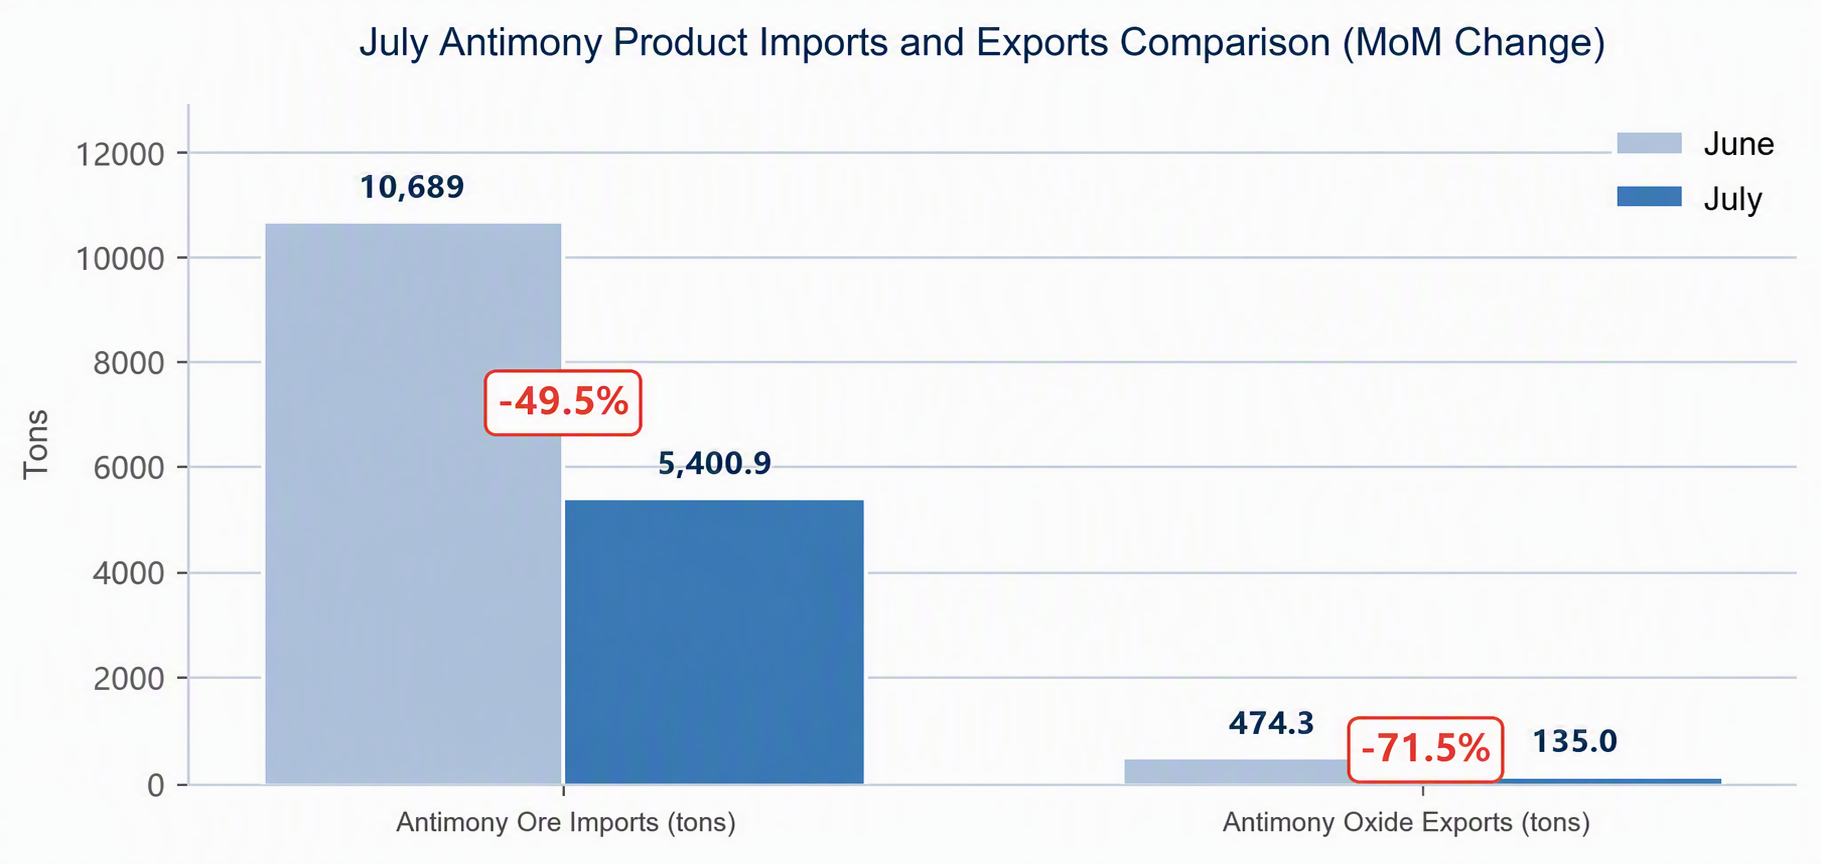
This week, #1 antimony ingot consolidated above the 100,000 mark before drifting higher, closing at 102,500 yuan/mt on Friday, up 2,000 (+2.0%) WoW; 99.8% antimony trioxide closed at 92,000 yuan/mt on Friday; production halts and rectification at some large antimony mines in Hunan + August antimony ingot production -9%, new bullish supply-side factors released; July antimony ore imports at 5,400.89 mt (-49.5% MoM) remained low, antimony trioxide exports at only 135 mt (-71.5%), export controls continuing.
I. Price Review This Week
This week (August 28–September 4), the antimony products market continued its pattern of "stabilizing at highs and rising slowly." After #1 antimony ingot consolidated above the 100,000 yuan/mt integer mark, the price center continued to move higher: on Monday (9/1), it rose from 100,750 yuan/mt on August 28 to 101,500 yuan/mt, hit 102,500 yuan/mt on Wednesday (9/3), and held steady on Thursday (9/4); signals of tightening spot circulation strengthened.
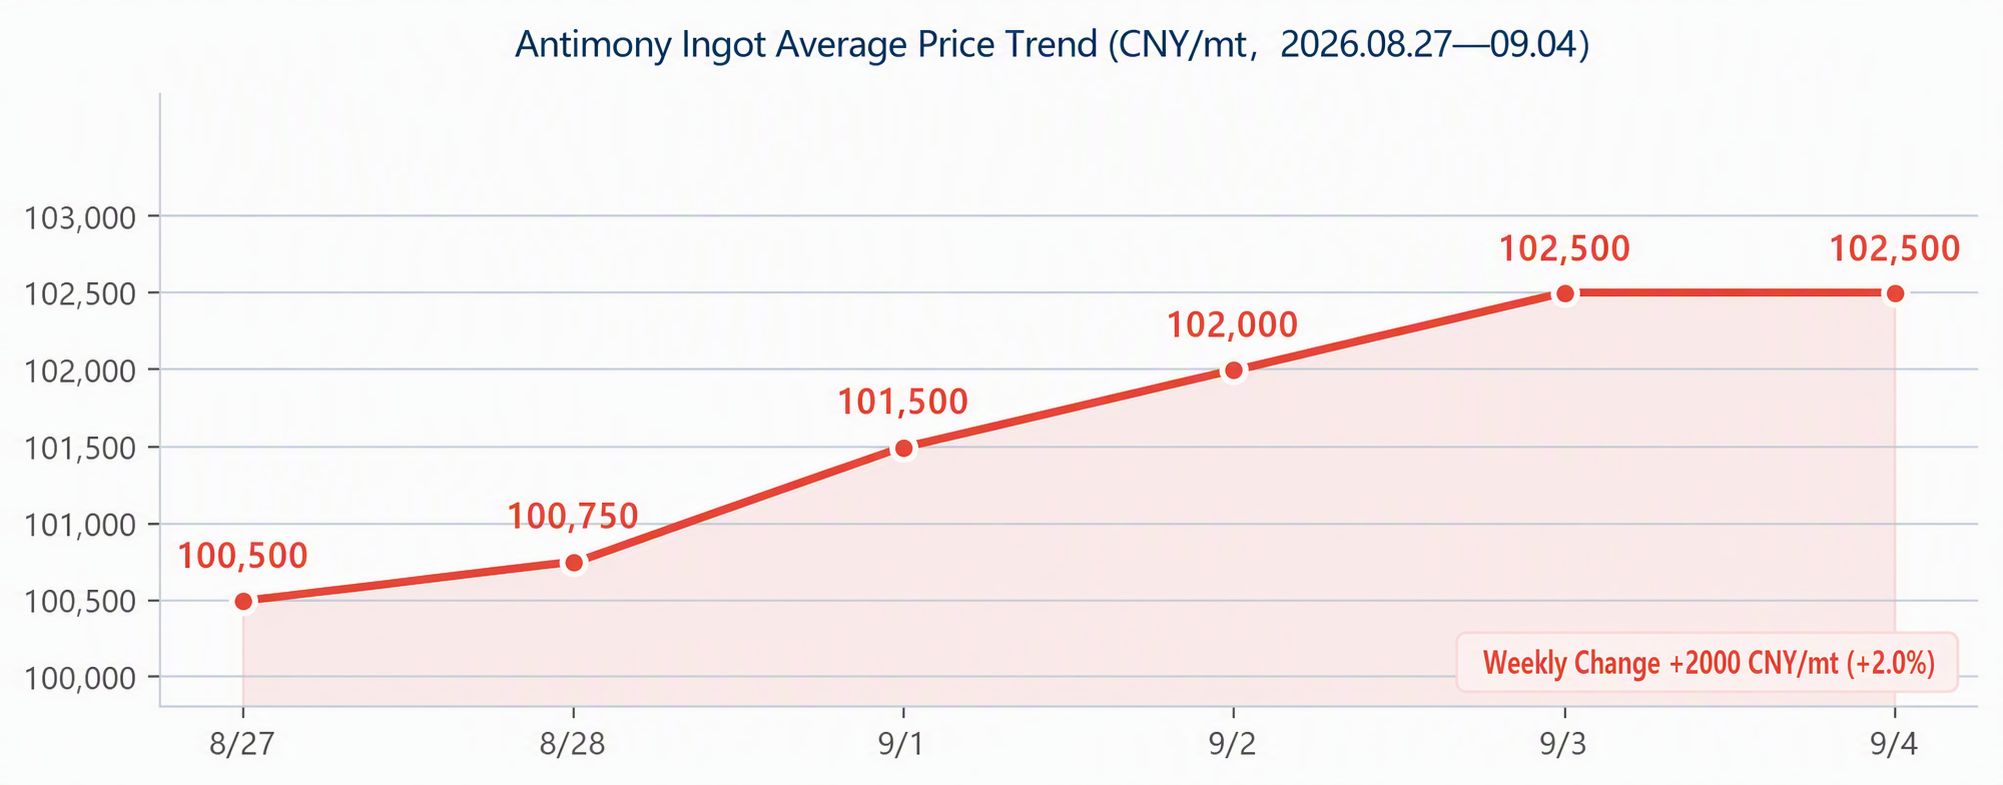
Drivers: ① Production halts and rectification at Hunan antimony mines, with multiple large antimony mines producing over 100 mt per month halted for at least one month, adding new variables to China's raw material supply; ② August antimony ingot production -9% (SMM assessment in early September), with the sharp drop in July antimony ore imports feeding through to August production; ③ "September-October peak season" stockpiling expectations providing support; ④ However, downstream flame retardant and sodium pyroantimonate buyers remained cautious about high-priced cargoes, keeping the upward pace mild.
II. Market Supply (Production Side)
This week, the supply-side focus shifted from "imports" to "production." SMM's latest assessment in early September showed that China's August antimony ingot production (including antimony ingot, converted crude antimony, antimony cathode, etc.) fell about 9% MoM, showing a pullback. Market participants generally believe the August production decline was normal—the sharp drop in July overseas antimony ore imports (-49.5%) was bound to translate into lower antimony ingot production in August.
More noteworthy was the SMM news released on August 28 about "production halts and rectification at some large antimony mines in Hunan": the report showed that multiple large antimony mines in Hunan with monthly production exceeding 100 mt have halted production, with the halt expected to last at least one month, which will have a certain impact on Hunan's antimony supply in the short term. Combined with long-term mining controls, environmental protection requirements, and periodic enterprise maintenance in major producing areas such as Hunan and Guangxi, antimony concentrate output from mines remains limited.
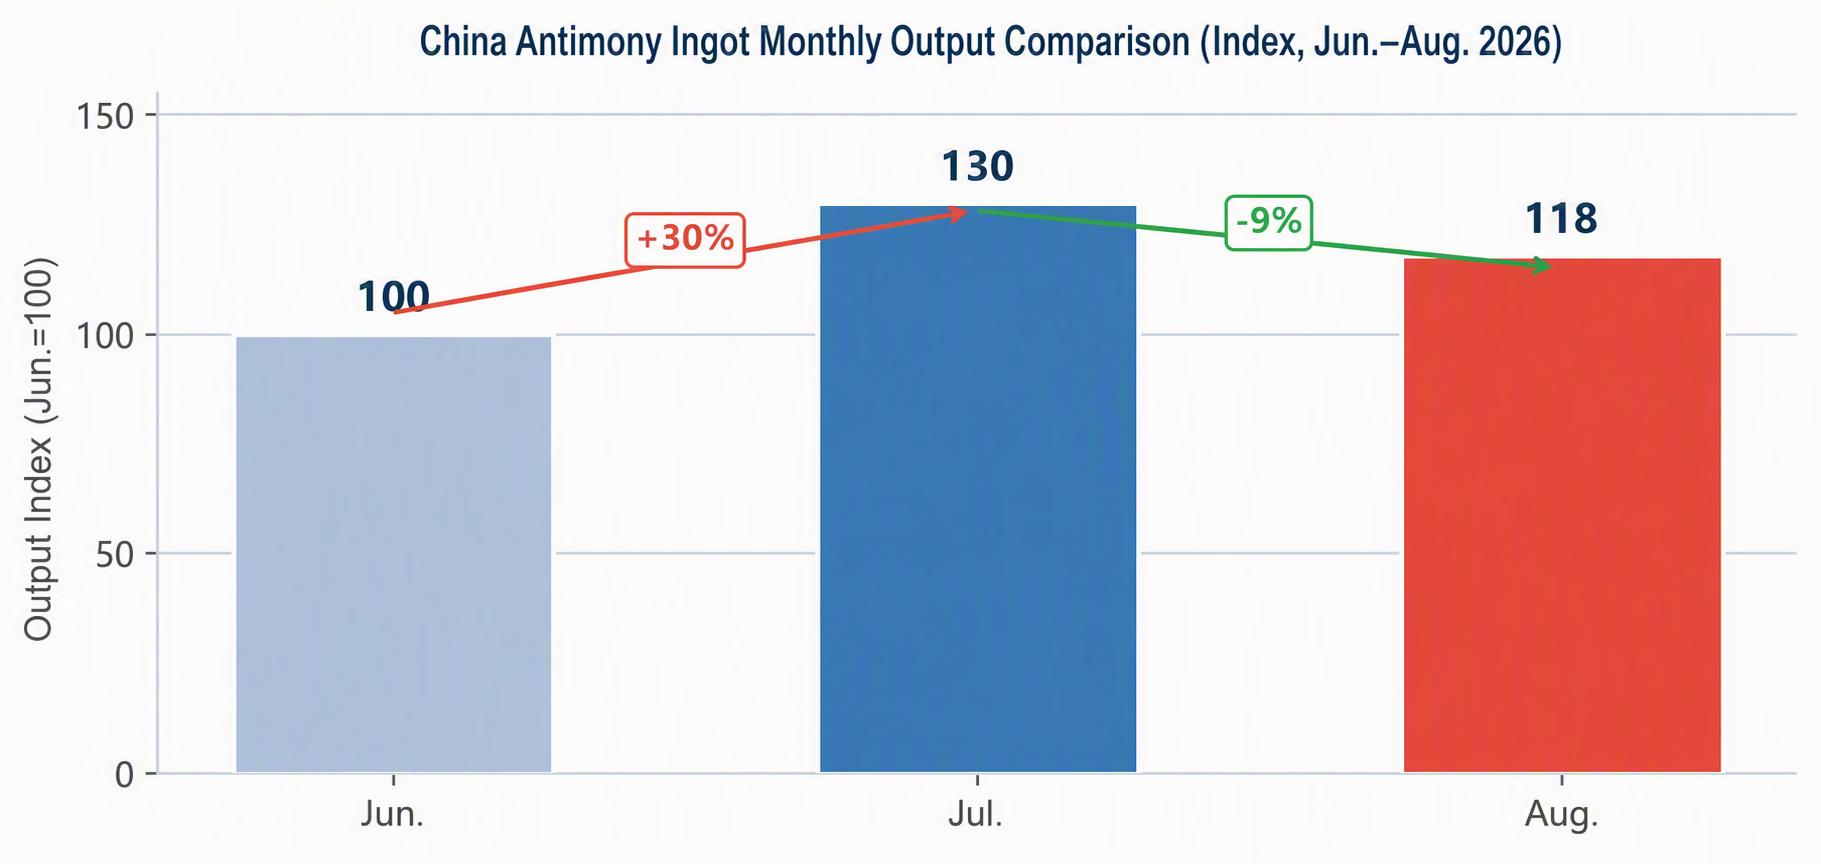
In terms of pace, using June production as a baseline of about 100, July shot up +30% (corresponding to the conversion of H1 cumulative antimony ore imports of 59,347.5 mt in physical content, exceeding full-year 2025 imports), and August pulled back -9%; the July surge and August pullback are broadly consistent with the time lag from the sharp drop in July antimony ore imports. The proposed 10,000 mt/year No.1 antimony ingot smelting project at Xiaoerkule in Xinjiang remains a long-term supply variable and does not pose a shock to short-term prices.
III. Import and Export Changes
July customs data (released on August 20) showed a dual decline pattern of "plunging imports + contracting exports." SMM assessments confirm that the sharp drop in raw material imports has strengthened smelting cost support, serving as the core momentum behind antimony ingot's continued rise this week.
IV. End-Use Demand
End-use demand showed a divergent pattern this week. Flame retardants improved mildly, with bromine prices rising to a high of 36,500 yuan/mt and consolidating at highs amid supply tightness, providing cost support for antimony prices. However, downstream acceptance of post-price-hike supply remains cautious, creating resistance in transmission to the upstream smelting segment. Sodium pyroantimonate: China's first-grade sodium pyroantimonate production in August 2026 is expected to rise sharply by around 58% MoM. The notable increase in August production has led many market participants to speculate whether the September-October peak season has arrived, with PV glass industry stockpiling of sodium pyroantimonate likely to increase gradually.
V. Market Outlook
Combining data from production, imports and exports, and demand, supply-side positives (Hunan production halt + August production -9% + low imports) continue to accumulate, while demand-side verification (actual restocking pace during the September-October peak season) still requires time. Over the next 1-2 months, the antimony market is expected to maintain a relatively strong pattern as peak-season demand materializes. From late Q3 to early Q4 is the traditional peak consumption season for antimony products, with the flame retardant industry entering its production peak, which will boost consumption of antimony trioxide and antimony ingot. Although PV glass is cutting production, it is unlikely to alter the overall demand structure. On the supply side, domestic antimony ore is constrained by resource limitations and is unlikely to see significant volume increases, export controls continue to deepen, and Thailand's role as a transshipment hub strengthens, so prices cannot rule out gradually showing strength.
Key Watchpoints
- Downstream actual acceptance of post-increase antimony ingot prices and sustainability of transaction volume growth
- Pace of production resumptions at halted antimony mines in Hunan and whether other major producing regions in China follow suit
- Actual verification of September-October peak season demand (flame retardant operating rates, PV module production schedules)
- Changes in August antimony ore imports (whether they bottom out after already falling 49.5%)
- Changes in overseas antimony trioxide capacity and pace of domestic export recovery
- Progress of the 10,000 mt antimony ingot smelting project at Xiaoerkule in Xinjiang
- Bromine price trends and cost support
- Enforcement of strategic mineral export control policies