SMM, September 3:
In August, China's molybdenum market maintained a tight balance with supply tightening and rigid demand providing a floor, with overall prices rising first and then stabilizing, consolidating at highs. 45% molybdenum concentrates shot up to 5,455 yuan/mtu during August 19-25, holding firmly in the three-year high range; this also drove spot 60% ferromolybdenum higher, hitting a stage high of 344,000 yuan/mt on August 24-25. In August, China's molybdenum concentrates supply market saw production decline for the third consecutive month, and with the import window for overseas molybdenum raw materials closed, imported molybdenum raw materials also showed varying degrees of decline. Meanwhile, downstream molybdenum demand in China remained steady, with steel mill demand showing a stronger-than-usual off-season, and steel tender price centers moved up. However, the ferromolybdenum smelting segment continued to see slight margin inversion, capping upside room for finished product prices. Entering September, the tug-of-war between sellers and buyers in China's molybdenum market has intensified, with little room for significant supply growth on the supply side, while on the demand side, steel mills' September production schedules edged up MoM and stockpiling demand ahead of the upcoming holiday increased. Amid the tug-of-war between September supply contraction and peak-season demand verification, molybdenum is expected to consolidate at highs on a strong note, with molybdenum concentrates more likely to rise than fall and ferromolybdenum following steel tenders toward the cost line.
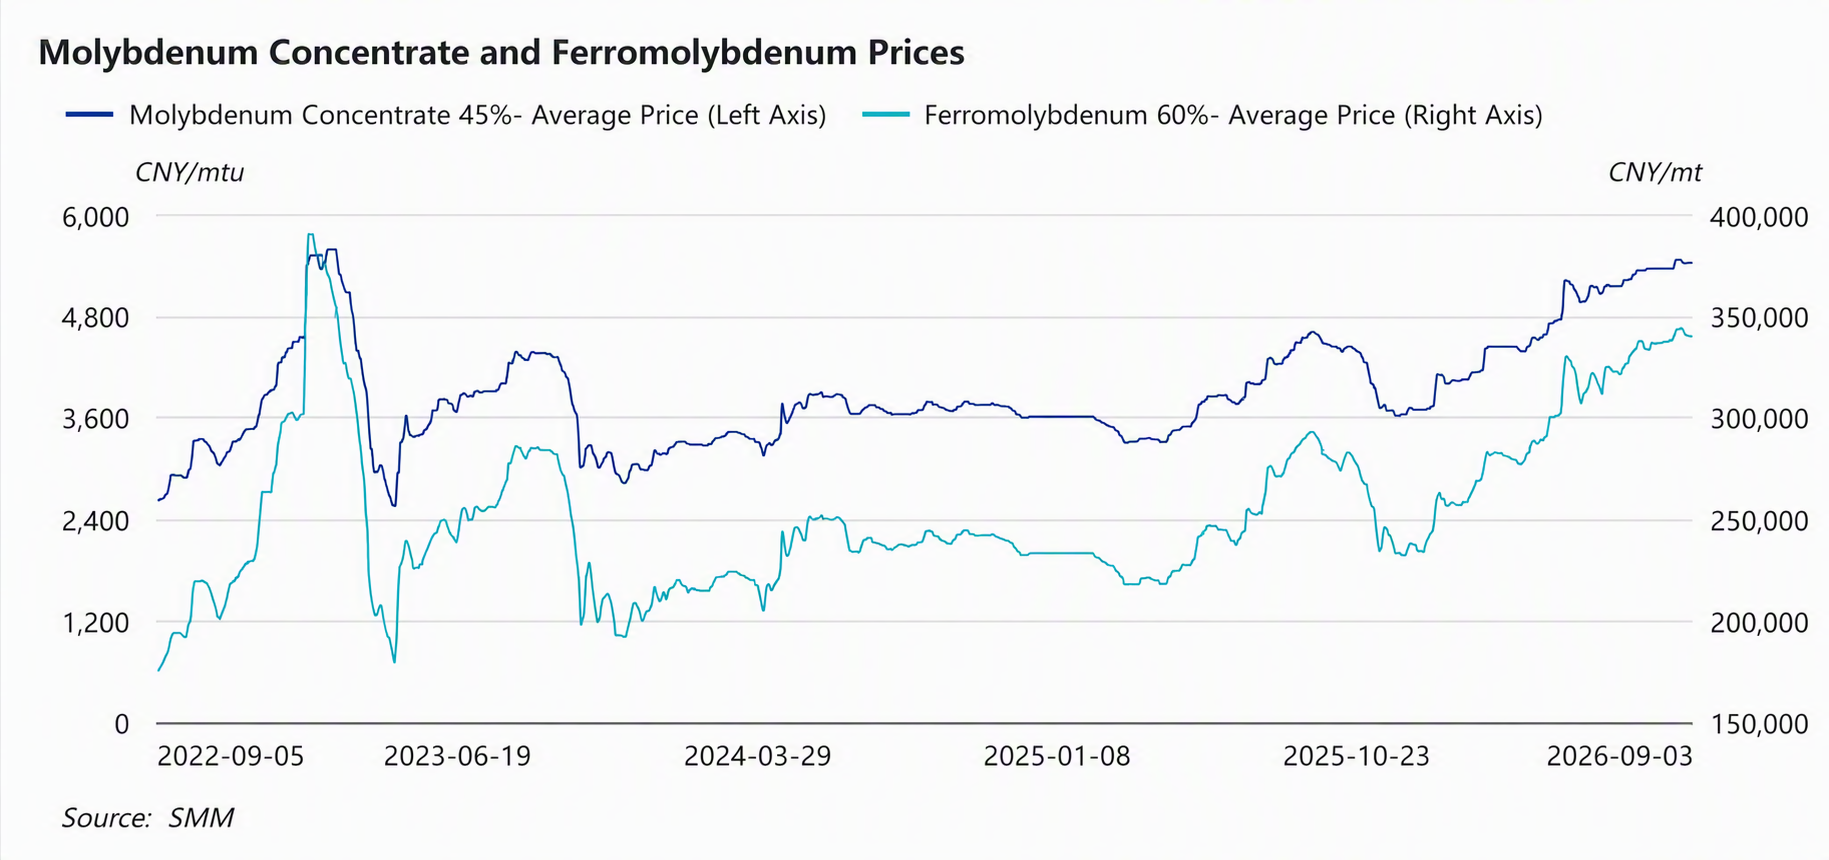
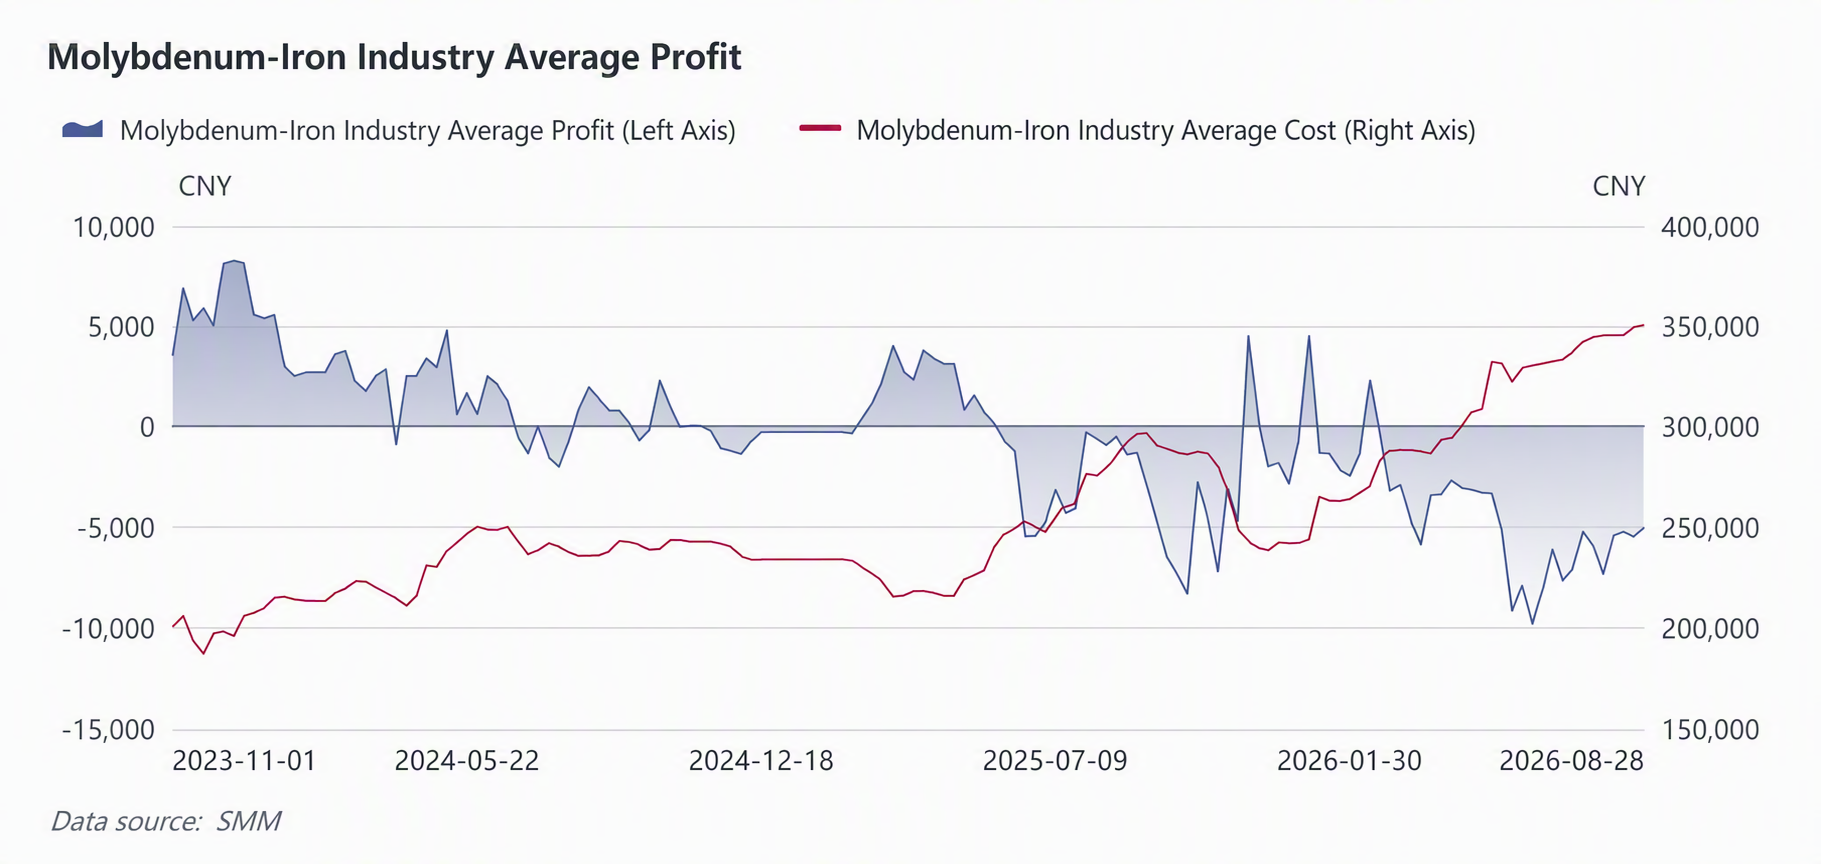
From the perspective of monthly average prices, the industry chain price center moved up for the third consecutive month: SMM 45% molybdenum concentrates averaged about 5,392 yuan/mtu in August, up 2.0% MoM; SMM molybdenum oxide averaged about 5,502 yuan/mtu, up 1.9% MoM; SMM ferromolybdenum averaged about 339,400 yuan/mt, up 2.2% MoM. The mine-side increase continued to outpace the smelting side, and the "strong ore, weak ferromoly" profit distribution pattern remained unchanged, with industry chain profits continuing to concentrate upstream.
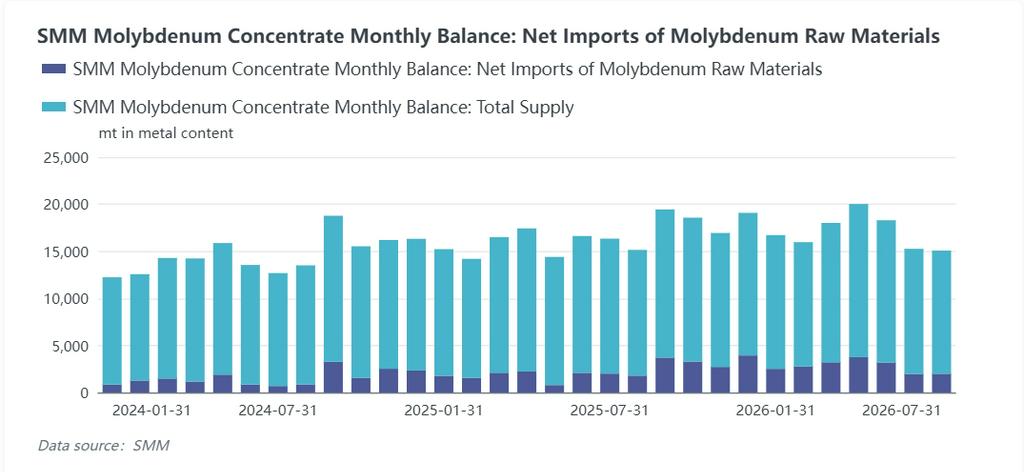
Molybdenum concentrates: Supply tightening remained the strongest pricing theme in the August molybdenum market. Domestically, molybdenum concentrates producers in Henan maintained production cuts. Under safety and environmental protection checks and mining quota constraints, mines and traders generally held back from selling, and low-priced cargoes nearly disappeared. According to SMM sample data, China's molybdenum concentrates production fell 4.5% MoM in August, the third consecutive month of MoM pullback, with cumulative contraction of about 10.1% from the May year-to-date high. Total molybdenum concentrates production in China from January to August was about 213,000 mt, down 6.5% YoY, with production growth falling short of expectations. In the short term, China's molybdenum mines are generally facing grade decline, and with stricter safety inspections and mining standards for underground metal mines, mine operations still face some disruption ahead. Most new domestic projects are concentrated for commissioning in 2028, so the operating status of existing mines will have a greater impact on the market in the short term. Entering September, China's molybdenum concentrates production is expected to remain largely flat, with a large mine in Heilongjiang having a maintenance plan during the month, no concentrated production resumption expectations heard from Henan mines that had cut production, and mines in Jiangxi, Fujian and other regions still facing flooding season impacts, making production growth unlikely.
Outside China, declining grades and ongoing labor disruptions at major mining areas in Chile and Peru continued to weigh on supply. BHP's FY2026 annual report released on August 18 showed total molybdenum production of 1,251 mt for the fiscal year, down 58% YoY, with total sales of 1,157 mt, down 65% YoY. The larger decline in sales than production implied inventory accumulation of roughly 94 mt. Codelco's molybdenum production in Q1 2026 fell 7.1% YoY, and incremental molybdenum by-product supply outside China remained limited. Imported molybdenum oxide CIF prices climbed steadily in August to a high of $33.6/lb Mo, and elevated import costs provided clear support to domestic raw material prices. Since the start of this year, the overseas molybdenum oxide market has continued to consolidate at highs, while domestic molybdenum oxide imports have remained in an inverted state. According to customs data, China's molybdenum concentrates imports totaled 50,973.409 mt in January-July 2026, up 47.71% YoY. However, some of the imported molybdenum concentrates this year were raw ore sourced from regions such as Myanmar with lower grades. Excluding this portion, conventional molybdenum concentrates imports totaled approximately 34,490 mt, down 0.2% YoY on a cumulative basis. In July, domestic molybdenum oxide imports fell off a cliff MoM, dropping 65% to around 523 mt. Cumulative molybdenum oxide imports in January-July rose 93.5% YoY, mainly because long-term contract supply accounted for a relatively large share, with no reduction in long-term contract volumes seen so far. However, supported by the persistent inversion of price spreads between Chinese and overseas markets, China's molybdenum oxide export market showed growth momentum, with cumulative exports of 8,322 mt in January-July, up 1.1% YoY.
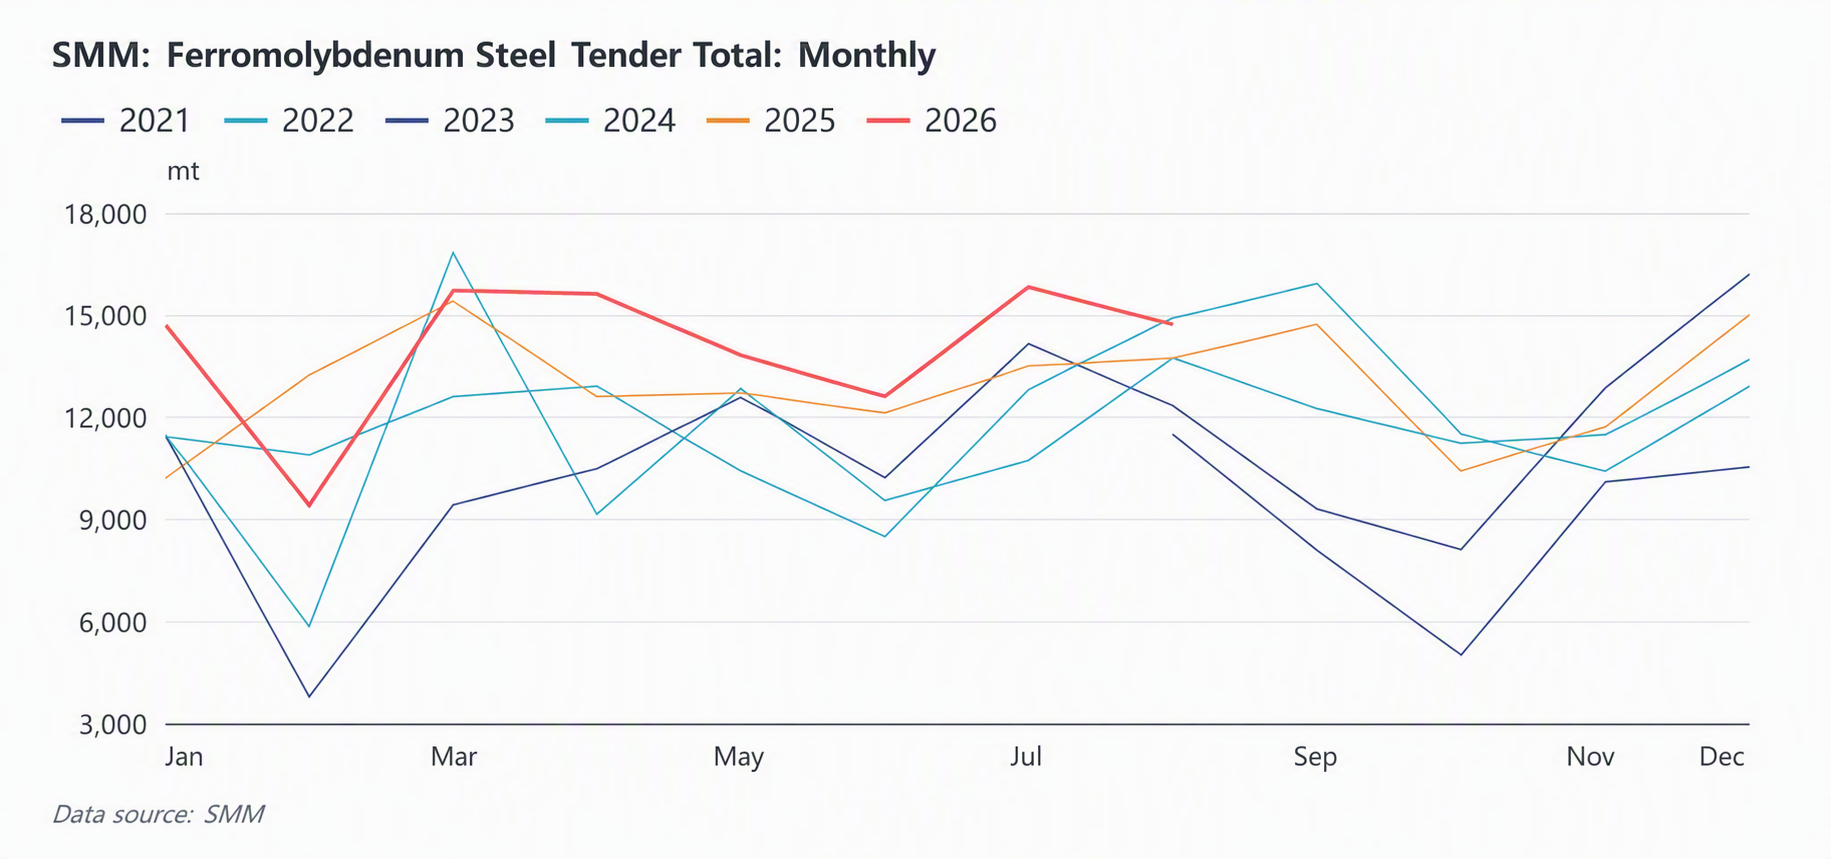
Ferromolybdenum: According to SMM sample data, China's ferromolybdenum production fell 3.0% MoM and 3.2% YoY in August. The main reason was the persistent inversion in the smelting segment—the industry average profit margin in late August remained at -1.45%, and mills scheduled production based on demand while proactively reducing operating rates. Although steel tenders were front-loaded, actual smelting growth remained cautious. In August, stainless steel and special steel end-users were still in the traditional off-season, but steel mill procurement was clearly front-loaded—August ferromolybdenum tender deliveries were mostly scheduled for September peak-season production—with both tender volumes and prices rising. Data showed that China's total steel tender volume in August was approximately 14,700 mt, up 7.3% YoY, and total ferromolybdenum steel tender volume in January-August was approximately 112,300 mt, up 8.6% YoY. In addition to public tenders, some steel mills also needed to make flexible purchases from the spot order market. Based on order feedback from steel mills, demand for alloy steel used in oil and gas pipelines, high-end equipment, and shipbuilding in China remained resilient in 2026, driving growth in molybdenum-containing steel demand. However, as costs of molybdenum and nickel rose, SMM calculations showed that profitability in the 316 stainless steel sector narrowed notably in August, and steel mills will need to monitor the impact of profitability on demand going forward.
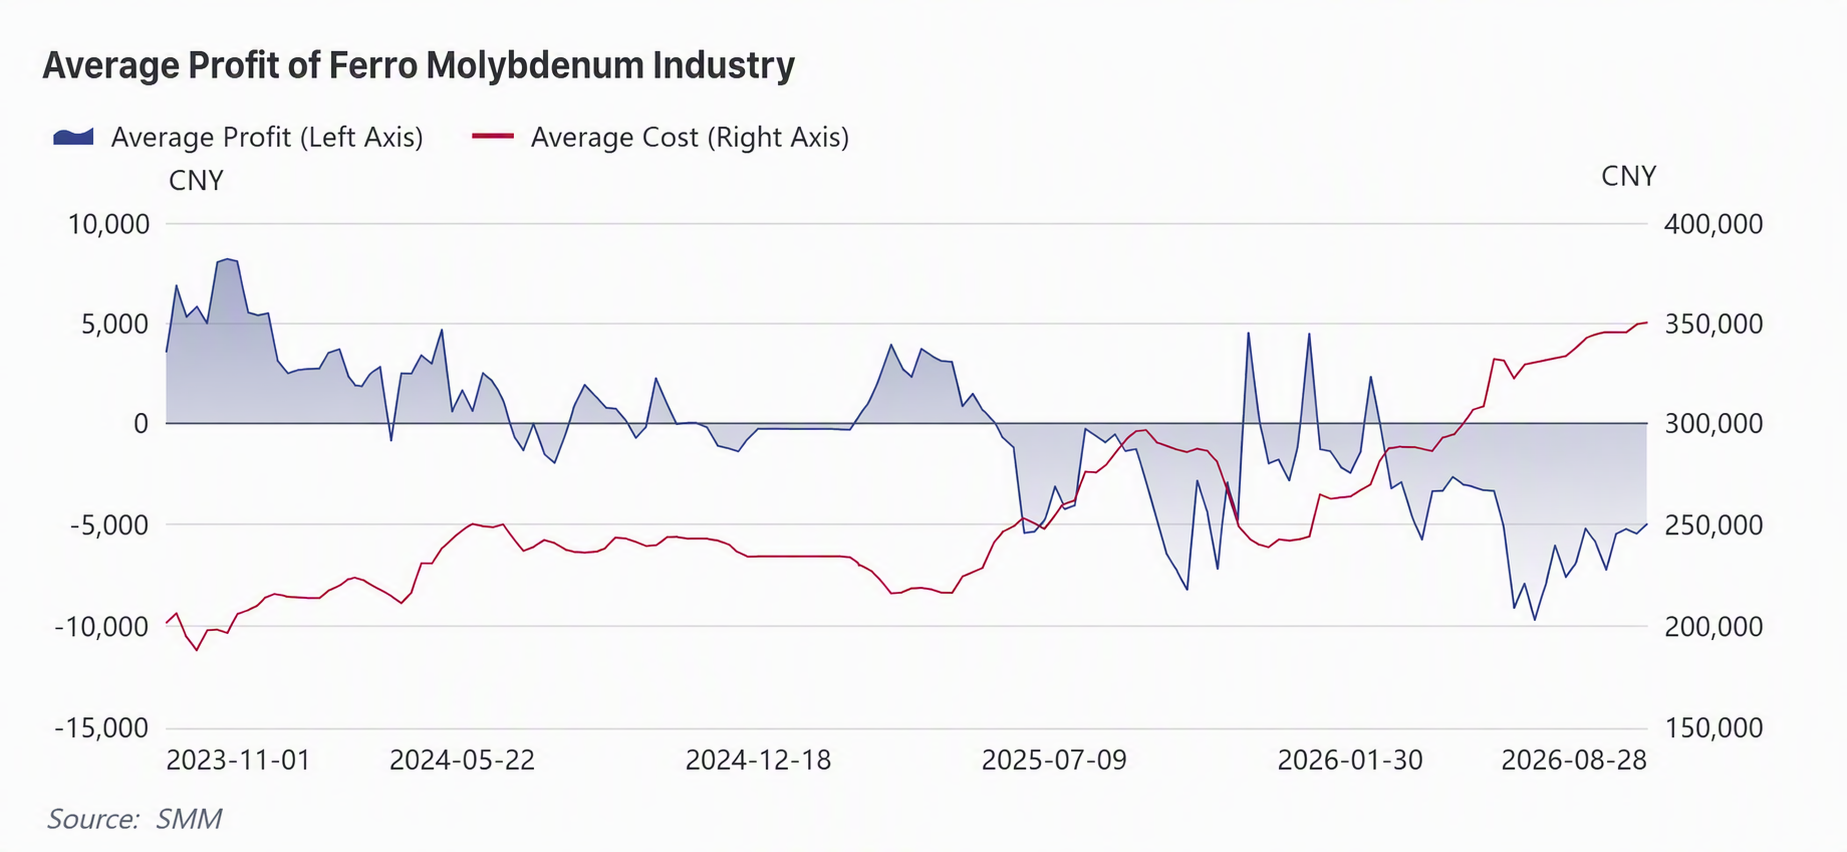
At the beginning of September, the tug-of-war between sellers and buyers in China's molybdenum market intensified. On September 3, two mines in Yunnan and Jiangxi successively auctioned molybdenum concentrates, with the transaction center for 45% molybdenum concentrates remaining around 5,430 yuan/mtu, equivalent to a molybdenum iron production cost of 340,800 yuan/mt. With downstream inventories at low levels, purchasing was active. Downstream steel mills entered the market intensively for tenders from late August to early September, with tender prices from representative stainless steel mills in Fujian, Shanxi, and other regions generally concentrated at 337,000 yuan/mt. However, with significant cost pressure in the molybdenum iron market, tender prices at some steel mills were pushed up to 338,500 yuan/mt. Molybdenum iron plants mostly executed earlier orders, and with order losses at molybdenum iron plants and the tight supply of upstream molybdenum concentrates persisting, contradictions in industrial profit distribution were prominent, further intensifying market tug-of-war. In markets outside China, international molybdenum prices remained high, and there was no notable growth in imported molybdenum concentrate inflows, making it difficult to ease the tight domestic raw material supply. In the short term, the cost bottom support formed by tightening molybdenum concentrate supply is relatively strong, and the molybdenum market in September is expected to consolidate on a strong note. However, caution is needed regarding cost pressure on downstream steel mills, as resistance to upward transmission is significant, and the market may continue to maintain a divergent pattern of strong ore and weak iron. Going forward, focus should be on new domestic mine output additions, the implementation of concentrated steel mill tenders, and changes in smelter operating rates. If steel tender prices struggle to approach the cost line, the risk of production cuts in the smelting sector may further expand, and prices will continue to consolidate at highs amid the supply-demand tug-of-war.