Key takeaway: A Q4 spike is unlikely, but we do expect continued moderate growth. Monthly output is likely to settle in the 9–10 tonne range – a modest step-up from Q3, not an explosive leap.
I. January–August Review: China Now Dominates Global Supply
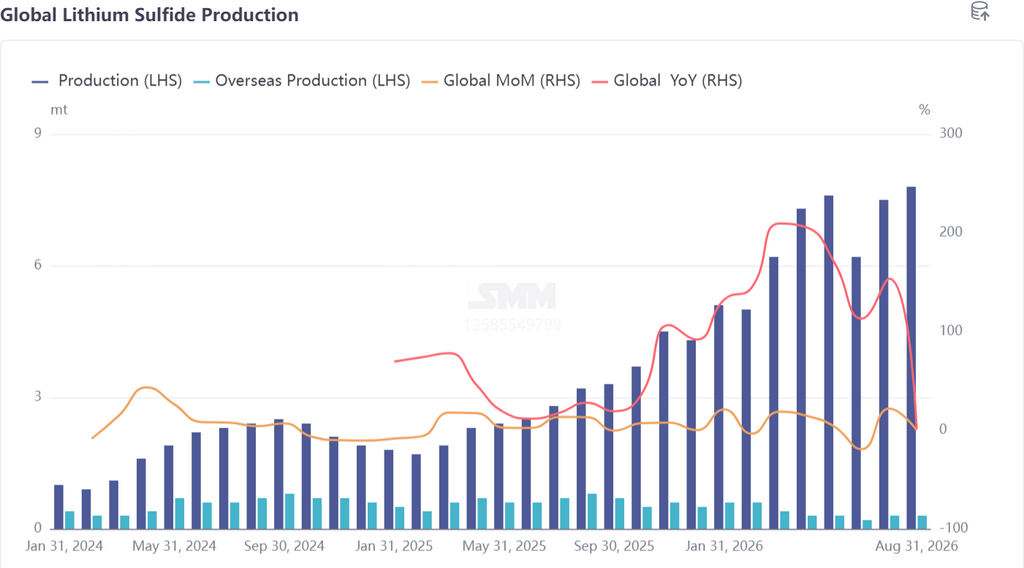
China produced 52.9 tonnes in the first eight months of 2026, up 184% year-on-year and already exceeding the full‑year 2025 total of 34 tonnes. Domestic capacity release has entered a substantive delivery phase. Overseas, only 3.0 tonnes were produced in the same period, down 39% year-on-year, as Japanese and Korean producers remain constrained by equipment commissioning and weak downstream orders – essentially "capacity without output". Of the global 55.9‑tonne total, China accounted for 95%.
The key question: does this 52.9 tonnes reflect "how much can be produced" or "how much is actually needed"? The answer leans toward the latter – current production is more driven by downstream stocking cycles than by capacity bottlenecks. Some producers have built inventories in anticipation of stronger Q4 demand.
II. Q3 Performance: Ramp-Up Continues, but the Slope Is Easing
August data: Domestic output of 7.79 tonnes, up 3.6% month-on-month and 143% year-on-year. The monthly growth rate has narrowed from double‑digit in Q2 to single‑digit – a signal that the steepest phase of the capacity ramp‑up is behind us, and we are now in a period of moderate, rather than explosive, volume growth.
September outlook: Domestic production is expected at 8.0–8.5 tonnes, with a midpoint of 8.3 tonnes, likely setting a new monthly high. Support comes from three factors: ① stable operations at major facilities; ② end‑of‑Q3 rigid stocking demand from solid‑state battery customers; and ③ continued low‑load commissioning at new capacities from Xiba, Wanbang, and others. However, the ceiling is clear: downstream cell makers have not yet entered large‑scale procurement cycles, so there is no basis for a sudden spike in utilisation.
Overseas output remains negligible at 0.3 tonnes.
III. Q4 Projection: No Spike Expected
Average monthly output in Q4 is projected to land in the 9–10 tonne range, representing a 15–25% sequential increase from Q3's ~8 tonnes/month – a moderate rise, not a surge.
3.1 Factors supporting upside:
New capacity additions: Sichuan QuanguSolid's line is expected to come online in Q4; Xiba's hundred‑tonne‑scale line will continue to ramp; and Wanbang & Salt Lake still have room to increase output. These are all "invested but not yet fully utilised" sources of flexibility.
Downstream stocking: Q4 is traditionally a peak stocking season for battery material companies, and some solid‑state battery customers are accelerating their pilot‑line schedules, supporting sequential demand improvement.
3.2 Factors capping a breakout:
Orders are the hard constraint: Solid‑state batteries are still in the pre‑commercialisation stage. Sulfide electrolyte purchases by leading cell makers remain far from "mass‑volume" levels. Without final‑user orders, lithium sulfide lines will not run at full capacity – this is not a capacity issue but an economic one.
Overseas offers no help: Japanese and Korean producers will remain focused on equipment debugging and small‑batch validation through Q4, so global supply growth will depend solely on China.
Quantitative assessment: Q4 monthly average output is most likely to fall in the 9–10 tonne range, with December potentially touching 10–11 tonnes (depending on the Sichuan QuanguSolid start‑up schedule). Full‑year 2026 production is expected at 85–95 tonnes – a 2.5‑ to 2.8‑fold increase from 2025's 34 tonnes.
IV. The Core Tension: Capacity Is Not the Bottleneck – Orders Are
The real state of the lithium sulfide market is this: domestic installed capacity far exceeds actual output, and actual output depends entirely on the procurement pace of downstream solid‑state battery customers.
The only variable that matters in Q4: Will electrolyte procurement volumes from top domestic solid‑state battery makers show a meaningful MoM jump? If yes, Q4 monthly averages could challenge 10–11 tonnes; if no, 9–10 tonnes remains a reasonable baseline.
V. Bottom Line
Q4 will not see a spike, but it will maintain a steady month‑by‑month upward crawl. A full‑year total of 85–95 tonnes would already be a strong validation of supply‑side capability. The real "spike" will have to wait for downstream solid‑state battery vehicle deployment – and that is at least a 2027‑and‑beyond story.
Risk note: If Q4 downstream stocking appetite falls short of expectations – particularly if solid‑state battery customers delay their pilot schedules – domestic producers may voluntarily cut utilisation, pushing monthly output down to the 8‑tonne level. The >100% utilisation rates shown in some tables for October–December are statistical anomalies and should not be treated as regular production references.
**Note:** For further details or inquiries regarding solid-state battery development, please contact:
Phone: 021-20707860 (or WeChat: 13585549799)
Contact: Chaoxing Yang. Thank you!