Titanium Market Supply-Demand Imbalance Persists: Can the September-October Peak Season Break the Deadlock? [SMM Analysis]

Published: Sep 2, 2026 11:38
The titanium market remained under pressure overall in August. Titanium dioxide production rebounded, but inventory accumulated simultaneously, and prices drifted lower, with monthly declines of 0.6%-7.4% across the three grades. Sponge titanium production fluctuated at highs, prices were in the doldrums, and end-user just-in-time procurement dominated. The supply-demand imbalance remains unresolved, making it difficult for September-October peak season expectations to materialize, and the market is likely to stay weak in the short term.

August TiO2 production rebounds while inventory builds, prices drift lower

In August 2026, SMM China TiO2 production edged up 0.3% MoM, but producer inventory accumulated in tandem, up 0.34% MoM. On the pricing front, TiO2 remained broadly weak in August. As of August 31, the average price of rutile TiO2 closed at 13,650 yuan/mt (down 6.5% MoM), anatase averaged 12,500 yuan/mt (down 7.4% MoM), and chloride-process averaged 16,150 yuan/mt (down 0.62% MoM).
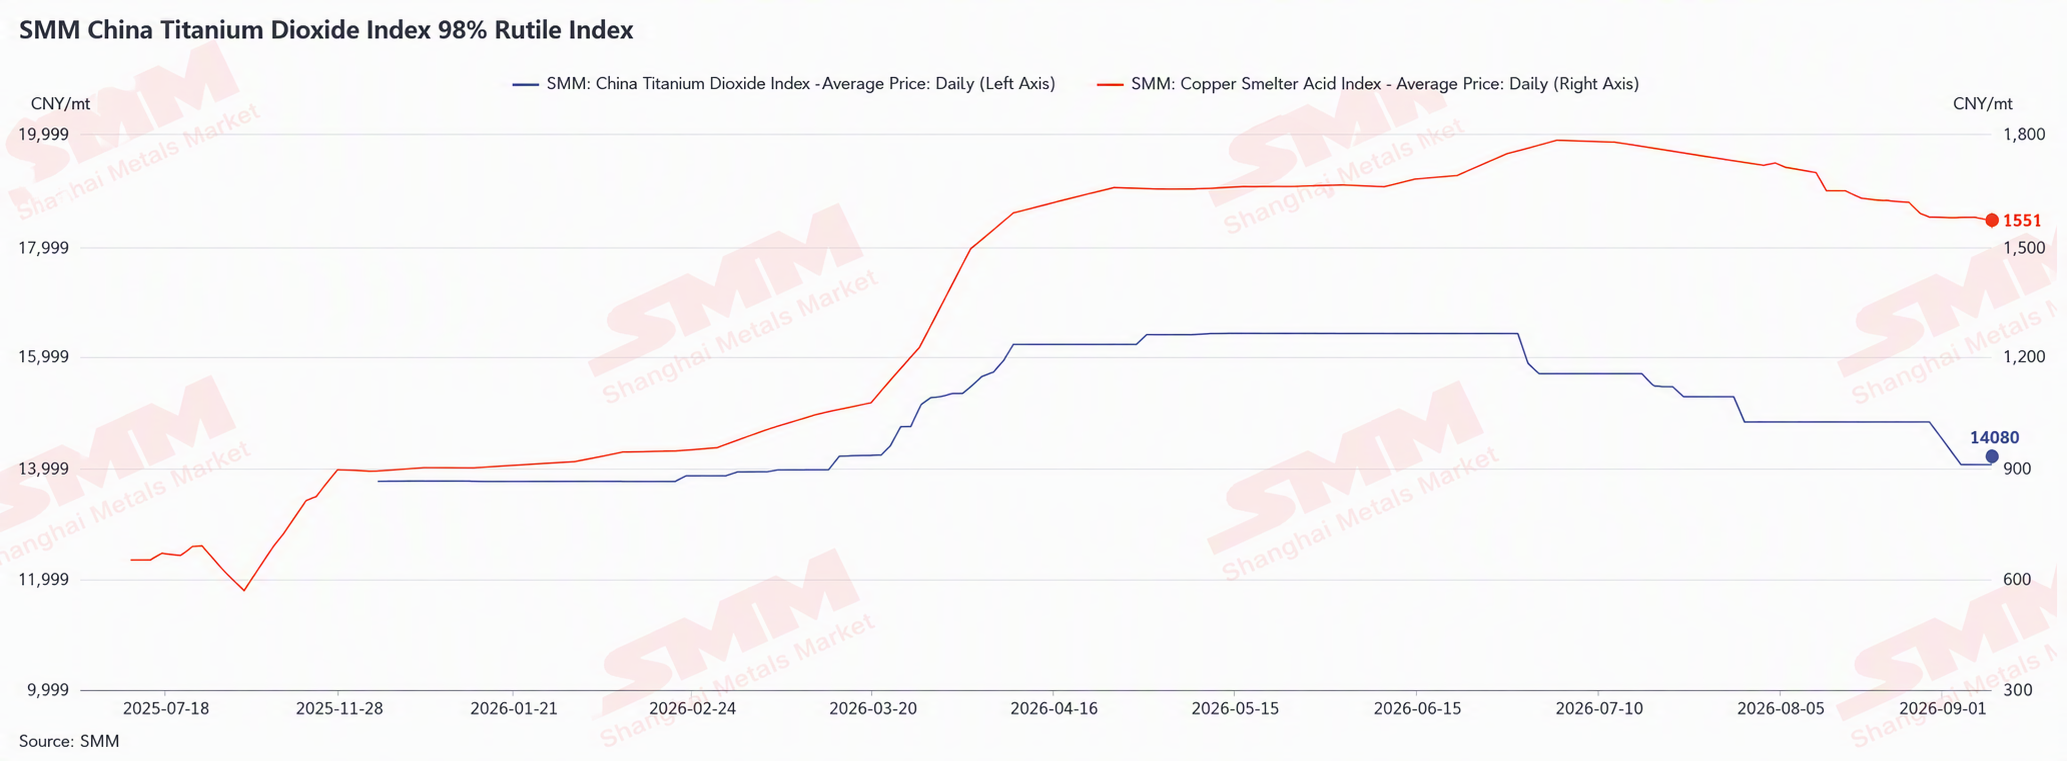
The TiO2 market stayed weak overall in August, with the price center continuing to shift lower. The monthly production rebound mainly came from resumed supply at previously idled or curtailed producers, adding incremental pressure to the market. Meanwhile, some enterprises still opted for maintenance shutdowns amid uncertainty, leaving the supply side in a divergent pattern. Top-tier players and producers with quality downstream client resources achieved relatively better production-sales balance, but many enterprises faced significant sales pressure. To seize market share, recover funds, and dilute fixed costs, they did not proactively restrict production and kept operations running.

On the demand side, the Chinese market has yet to show clear signs of recovery, with the industry dominated by just-in-time procurement. Downstream end-users continued to digest their own inventory and, given cautious judgment on the outlook, have not yet engaged in concentrated restocking. On exports, following the pullback in July, foreign trade still carries weakening expectations, with export pressure further intensifying the supply-demand imbalance.

In the short term, although some enterprises have signaled price adjustment intentions based on cost support, actual transactions have not picked up volume, and downstream demand follow-through remains insufficient. The traditional September-October peak season has yet to deliver effective positives, and the existing supply-demand pattern is difficult to repair quickly. TiO2 prices are expected to remain under pressure. In the medium and long term, industry pricing will gradually focus on price guidance from top-tier players, with price anchors increasingly driven by raw material costs such as sulphuric acid. Supply-side inventory digestion still needs time, and small and medium-sized producers are gradually exiting the market. On the demand side, the market awaits export policy-driven order release, and the supply-demand imbalance is expected to improve slowly.


August titanium sponge production fluctuates at highs, prices in the doldrums under pressure

In August 2026, SMM China titanium sponge production fell 1.85% MoM. Cumulative production from January to August reached 201,400 mt, up 14.04% YoY. On the pricing front, as of August 31, grade 0 titanium sponge was quoted at 44,000-45,000 yuan/mt, averaging 44,500 yuan/mt, down 1,000 yuan from the start of the month.
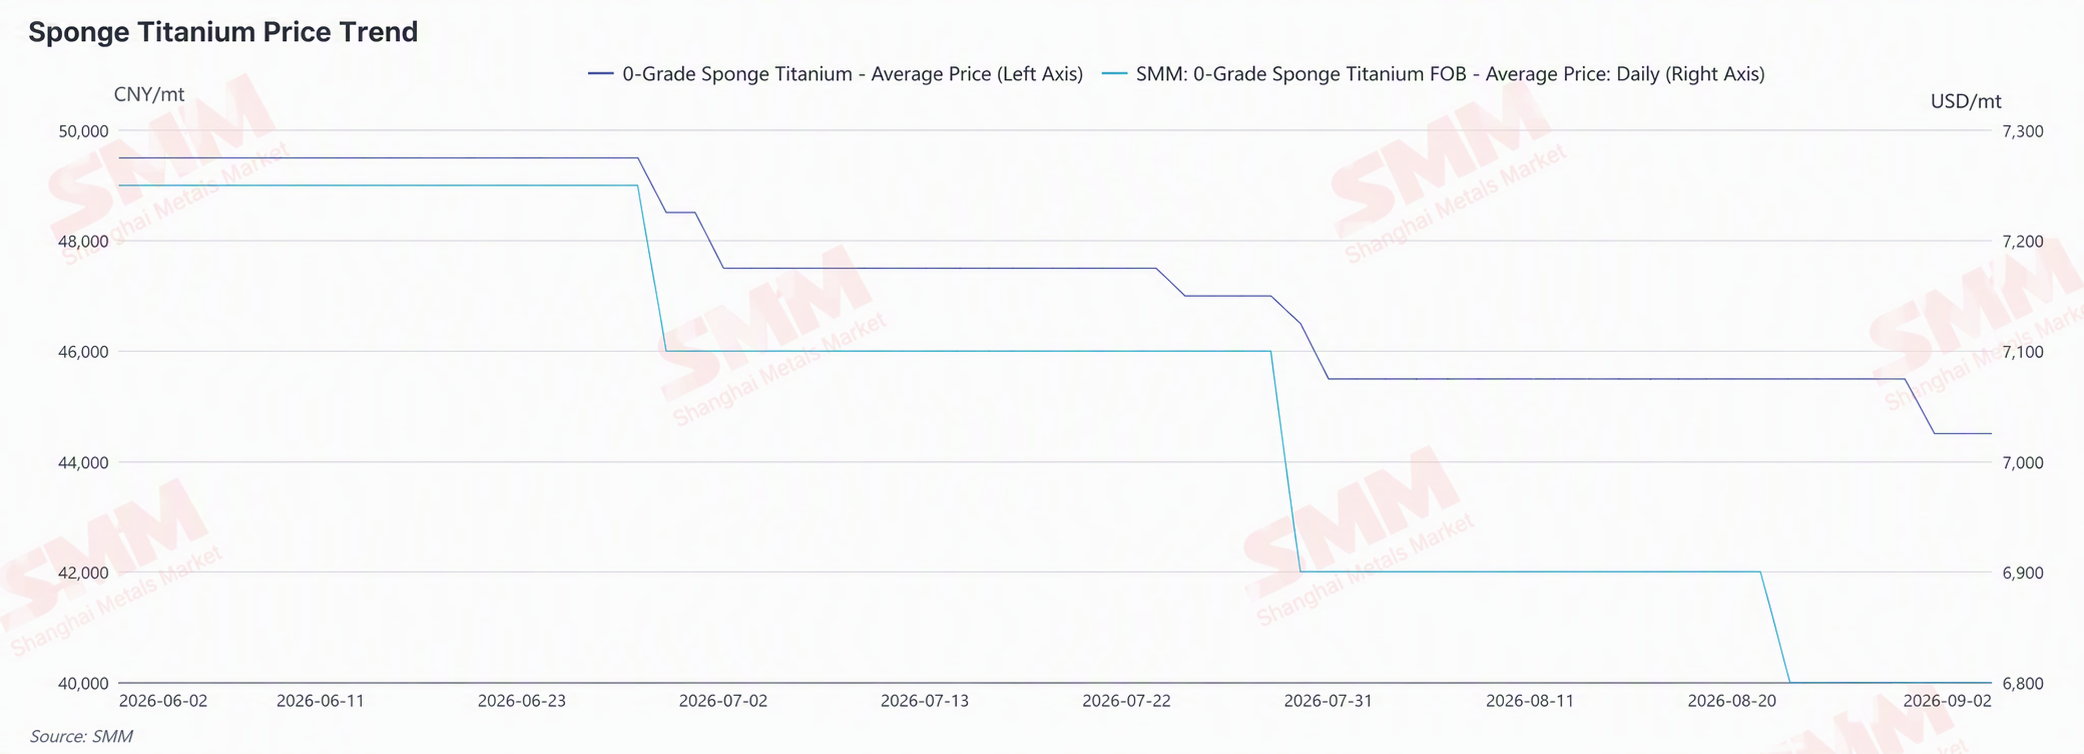
The titanium sponge market remained in the doldrums in August. After the collective price cuts in July, end-users maintained only just-in-time procurement. Some enterprises that had planned production cuts earlier did not fulfill their commitments, and with capacity continuing to expand this year, the industry kept production at high levels. In late August, producer quotes loosened again, and downstream buyers increasingly favored negotiated deals. On exports, titanium sponge export orders were mostly executed under long-term contracts, with little overall change.

On titanium materials, some enterprise inventory flowed into the market in Q2, leaving titanium material supply relatively saturated. Combined with stricter export controls and the traditional summer off-season, export orders underperformed this year. Overall, titanium materials showed a weak supply-demand pattern on both sides, further suppressing procurement demand for titanium sponge.

Looking ahead to Q4, the September-October peak season expectations are similarly unlikely to materialize in the titanium metal market. Projects in new energy and other sectors are unlikely to be implemented quickly in the short term, and titanium sponge prices will remain under pressure. In the medium and long term, as inventory is gradually digested and domestic demand growth is released, prices are expected to rebound.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Peak season expectations have yet to be effectively realized; titanium industry chain trends diverge in a tug-of-war [SMM Titanium Weekly Review]
Sep 4, 2026 15:57
Peak season expectations have yet to be effectively realized; titanium industry chain trends diverge in a tug-of-war [SMM Titanium Weekly Review]
Read More
Peak season expectations have yet to be effectively realized; titanium industry chain trends diverge in a tug-of-war [SMM Titanium Weekly Review]
[SMM Titanium Weekly Review: Peak-Season Expectations Not Yet Effectively Realised, Titanium Industry Chain Trends Diverge and Wrestle] This week, China's titanium industry chain showed a pattern of weak upstream pressure, stagnant midstream consolidation, and structural downstream divergence. Cost transmission across the chain was sluggish, and peak-season expectations have not yet materialised. Upstream titanium concentrates remained at low levels, imported ore declined, and new supply from Xinjiang increased domestic availability. Mine profits were thin, leaving limited downside room for prices. Titanium slag operating rates stayed low, enterprises were loss-making, and market trading was sluggish. Midstream titanium dioxide was in the doldrums and stagnant, with stable operating rates and new capacity being released. Inventory diverged, and some enterprises offered concessions to destock. The expiry of phosphate fertiliser export controls raised expectations of higher sulphuric acid costs, but weaker titanium concentrates undermined raw material support. Demand from real estate and coatings was sluggish, and price adjustments were mostly for order repairs, with insufficient actual follow-through, leaving the market stuck between upward and downward pressures. Downstream titanium sponge was suppressed by high capacity, with only rigid demand transactions. Titanium materials polarised: civil demand was sluggish, while high-end orders from aerospace and defence were ample. Titanium sponge costs formed a bottom support, and divergent trends across segments dominated short-term market movements.
Sep 4, 2026 15:57
China sulphuric acid index falls for nine consecutive weeks with a widening decline; domestic sulphur trade rebounds from lows, while sulphuric acid outside China stops falling and stabilizes [SMM Sulphuric Acid Weekly Review]
Sep 4, 2026 14:43
China sulphuric acid index falls for nine consecutive weeks with a widening decline; domestic sulphur trade rebounds from lows, while sulphuric acid outside China stops falling and stabilizes [SMM Sulphuric Acid Weekly Review]
Read More
China sulphuric acid index falls for nine consecutive weeks with a widening decline; domestic sulphur trade rebounds from lows, while sulphuric acid outside China stops falling and stabilizes [SMM Sulphuric Acid Weekly Review]
China sulphuric acid index falls for nine consecutive weeks with a widening decline; sulphur domestic trade rebounds from lows, while sulphuric acid outside China stops falling and stabilizes [SMM Sulphuric Acid Weekly Review]
Sep 4, 2026 14:43
Rio Tinto Suspends Madagascar Ilmenite Mining Due to Road Blockages, Affecting Titanium Supply
Sep 4, 2026 14:17
Rio Tinto Suspends Madagascar Ilmenite Mining Due to Road Blockages, Affecting Titanium Supply
Read More
Rio Tinto Suspends Madagascar Ilmenite Mining Due to Road Blockages, Affecting Titanium Supply
【SMM Titanium Flash】On August 27th, Rio Tinto's QIT Madagascar Minerals decided to temporarily suspend its mining operations due to multiple road blockages leading to the Mandena mining area. The company's main business in Madagascar is ilmenite mining, which is one of the important sources of global titanium raw material supply. Currently, basic safety-related services are still operating, and the resumption of production is pending further improvement in traffic conditions. This production halt may cause short-term disruptions to the regional supply of titanium ore.
Sep 4, 2026 14:17