SMM, August 29:
Metals Market:
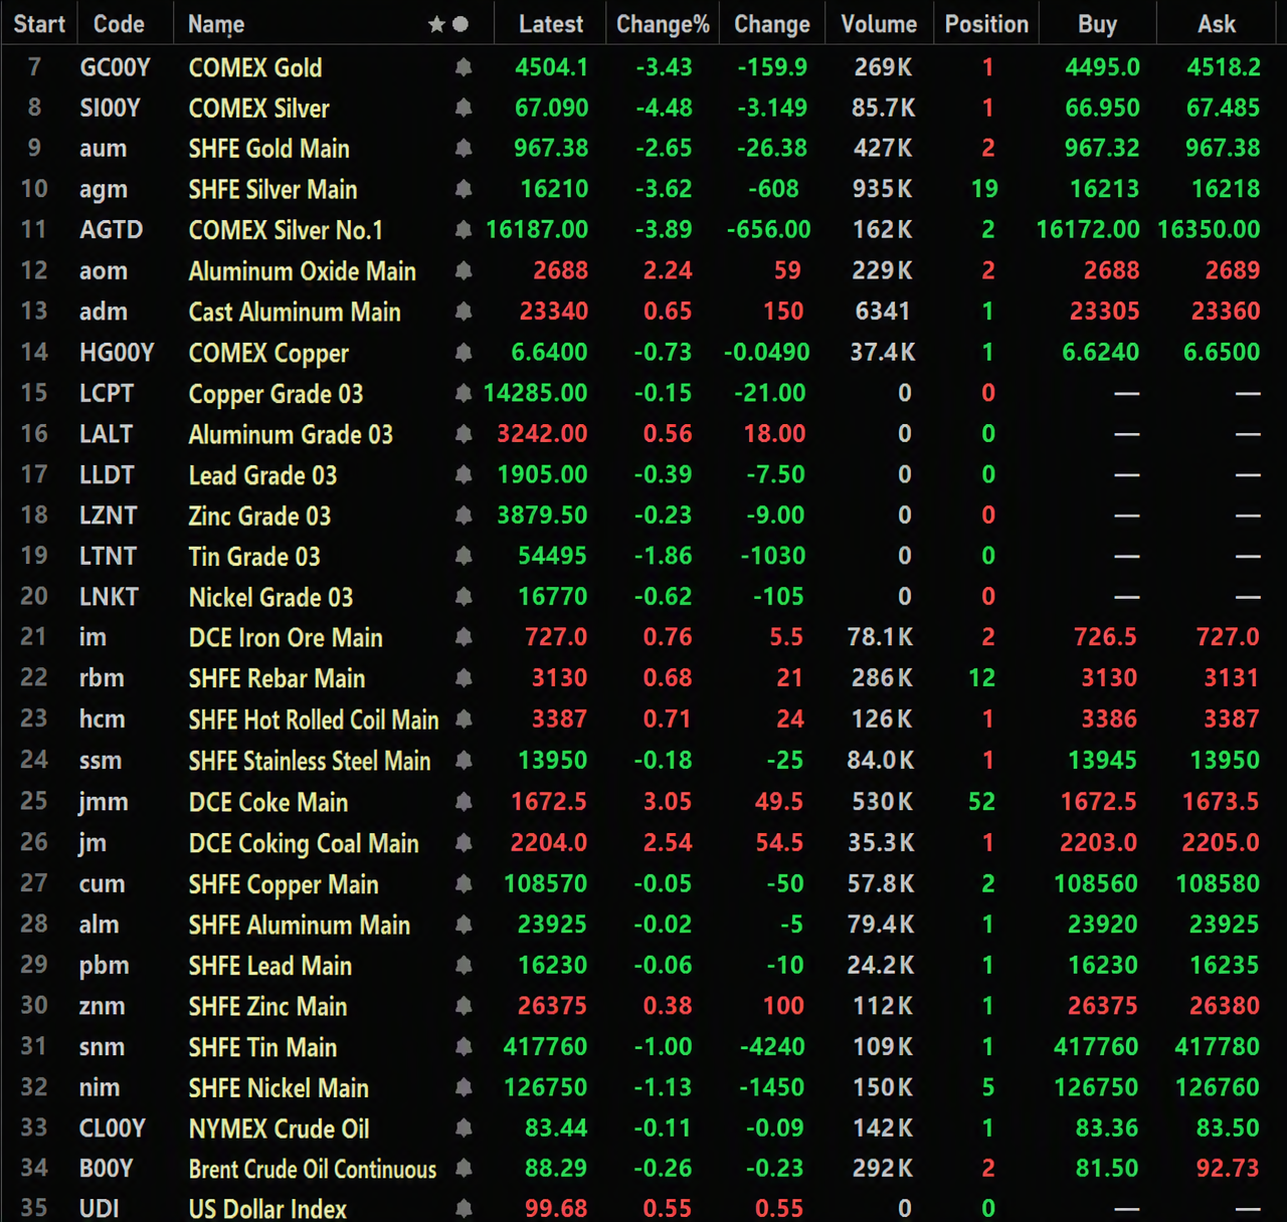
Overnight last Friday, base metals in the domestic market mostly rose. SHFE copper, SHFE aluminum, and SHFE lead edged down, all within 0.1%. SHFE zinc rose 0.38%, while SHFE tin fell 1%. SHFE nickel fell 1.13%. In addition, the most-traded alumina futures rose 2.24%, and the cast aluminum main contract rose 0.65%.
Overnight last Friday, ferrous metals were mostly higher. Stainless steel fell 0.18%. Iron ore rose 0.76%, and rebar rose 0.68%. Hot-rolled coil rose 0.71%. For coking coal and coke: the most-traded coking coal contract rose 3.05%, and the most-traded coke contract rose 2.54%.
Overnight last Friday, in the overseas metals market, LME base metals mostly fell. LME copper fell 0.15%, while LME aluminum rose 0.56%. LME lead fell 0.39%. LME zinc fell 0.23%. LME tin fell 1.86%. LME nickel fell 0.62%.
Overnight last Friday, in the precious metals market: COMEX gold fell 3.43%, and the weekly chart closed lower, down 3.77% for the week; COMEX silver fell 4.48%, and the weekly chart closed lower, down 3.51% for the week. Overnight last Friday, the SHFE gold main contract fell 2.65%, while SHFE gold posted a sixth consecutive weekly gain, up 2.09% for the week; the SHFE silver main contract fell 3.62%, while SHFE silver rose for a sixth consecutive week, up 3.64% for the week.
As of 7:17 on August 29, closing prices for last Friday's overnight session:
Macro Front
China:
[Two Departments: Extend Maximum Individual Housing Loan Term from 30 Years to 40 Years] The People's Bank of China and the National Financial Regulatory Administration issued a notice regarding the Opinions on Reforming and Improving Real Estate Credit Management and Accelerating the Building of a New Model for Real Estate Development. The notice stated that the maximum term for individual housing loans shall not exceed 40 years, and the loan amount shall not exceed the appraised value of the home to be purchased. For loans with a term of one year or less (including one year), principal and interest shall be repaid either in a lump sum at maturity or in monthly installments; for loans with a term longer than one year, principal and interest shall be repaid monthly.
[Three Departments: Orderly Promote Sales of Completed Commercial Housing, Ensure 'What You See Is What You Get,' and Promote 'Certificate on Delivery'] The Ministry of Housing and Urban-Rural Development, the Ministry of Natural Resources, and the National Financial Regulatory Administration issued a notice on improving the commercial housing sales system. The notice stated that all regions should vigorously and in an orderly manner promote sales of completed commercial housing, ensure that what buyers see is what they get, reduce disputes over the delivery of commercial housing, fundamentally guard against delivery risks, safeguard the legitimate rights and interests of homebuyers, and accelerate the building of a new model for real estate development.
[Reform and Improvement of the Real Estate Financing System: National Financial Regulatory Administration Issues Five Administrative Measures] The National Financial Regulatory Administration, together with relevant departments, reformed and improved the real estate financing system and issued the Interim Measures for the Administration of Commercial Housing Development Loans (Trial), the Interim Measures for the Administration of Personal Housing Loans (Trial), the Interim Measures for the Administration of Commercial Real Estate Loans (Trial), the Interim Measures for the Administration of Urban Renewal Project Loans (Trial), and the Interim Measures for the Administration of Trust Companies' Trust Business in the Real Estate Sector (Trial). The Interim Measures for the Administration of Commercial Housing Development Loans (Trial) fully draw on the experience and practices of the "white list" mechanism, treat projects of all ownership types equally, and meet the reasonable financing needs of commercial housing development projects. The Interim Measures for the Administration of Personal Housing Loans (Trial) reasonably adjust the timing of loan disbursement, appropriately optimize the upper limit on the income-to-debt ratio, and extend the maximum loan term, both safeguarding the lawful rights and interests of homebuyers and better meeting residents' rigid and improvement housing demand. The Interim Measures for the Administration of Commercial Real Estate Loans (Trial) specify loan requirements at the development, purchase, and operation stages of commercial real estate and support the stable and sound development of the commercial real estate market. The Interim Measures for the Administration of Urban Renewal Project Loans (Trial) guide banking financial institutions to enhance the precision, suitability, and effectiveness of financial services for urban renewal and help advance high-quality urban renewal. The Interim Measures for the Administration of Trust Companies' Trust Business in the Real Estate Sector (Trial) adhere to the principles of serving the real economy, controlling risks, and implementing investor suitability management. By clarifying business operation rules, strengthening professional capacity building, and enhancing investor protection, they encourage trust companies to better leverage their distinctive strengths in conducting trust business in the real estate sector. (CCTV)
[China Securities Regulatory Commission Issues the Opinions on Capital Market Support for Building a New Development Model for Real Estate] To implement the major decisions and arrangements of the CPC Central Committee and the State Council on accelerating the construction of a new development model for real estate and promoting the high-quality development of the real estate sector, accelerate the establishment of a capital market service system compatible with the new development model for real estate, support the improvement of housing quality and the transformation and development of enterprises, and promote a virtuous cycle between finance and real estate, the China Securities Regulatory Commission formulated the Opinions on Capital Market Support for Building a New Development Model for Real Estate (hereinafter referred to as the "Opinions"). The Opinions consist of 12 articles in four parts and mainly include the following: First, the overall requirements. Reform the financing methods for real estate development, promote a shift from reliance on entity credit to project-based conditions, and meet the reasonable financing needs of real estate development enterprises of all ownership types without discrimination. First, strengthen market access, information disclosure, and capital supervision in the real estate sector, prudently prevent, defuse, and handle real estate-related risks, and promote high-quality development of the real estate sector. Second, support reasonable financing. Support listed real estate development enterprises in refinancing and in using a combination of tools such as share issuance, targeted convertible bonds, and cash to acquire real estate-related assets. Increase bond financing support, support real estate development enterprises in issuing corporate bonds for real estate projects that meet policy requirements, and encourage the issuance of commercial mortgage-backed securities (CMBS) and real estate asset-backed securities (ABS). Support the issuance of real estate investment trusts (REITs) backed by eligible rental housing, urban renewal, and other projects or their use as assets for REIT expansion, and steadily and prudently advance the development of commercial real estate REITs. Support qualified private fund managers in establishing private real estate investment funds. Third, optimize regulation. Optimize access regulation for securities issuance by real estate development enterprises, highlighting the “project-based” financing feature; optimize information disclosure regulation, focusing on the implementation of accounting standards; strictly enforce ongoing and look-through supervision of raised funds; strictly prevent and crack down on illegal and non-compliant activities such as fraudulent issuance by issuers, false information disclosure, and misappropriation of raised funds, and increase penalties for systemic and organized fraud. Fourth, prevent and defuse risks. Implement the “four early” requirements, establish and improve mechanisms for advance research and early assessment of capital market-related risks in the real estate sector, and strengthen coordinated supervision of stocks, bonds, and funds. Ensure smooth and orderly delisting supervision of listed real estate development enterprises and keep diversified delisting channels open. Cooperate with local governments to promote the disposal and clearing of defaulted real estate bonds, and enrich diversified risk resolution mechanisms for real estate bonds.
US dollar:
In overnight trading last Friday, the US dollar index rose 0.55% to 99.68. On the weekly chart: the US dollar index rose for the week, up 0.84%.
Fed Chairman Warsh said on Friday that if policymakers cannot be confident that inflation is pulling back to 2% “at a clear and sufficiently fast pace,” the Fed “still has work to do.” That suggested that if price pressures did not improve, the Fed’s next step could be to raise interest rates. Warsh made clear that he still adheres to the Fed’s long-standing policy approach of managing inflation by adjusting interest rates. This significantly raised the likelihood that the Fed’s next move would be an interest rate hike, which could put him at odds with President Trump, who has long sought interest rate cuts. These remarks largely eliminated the ambiguity left earlier. At a late-July press conference, Warsh declined to say much about whether interest rate hikes were needed to address inflation that had risen sharply this year and remained above the Fed’s target for more than five consecutive years. After Fed Chairman Warsh spoke about curbing inflationary pressures, market bets on US Fed rate hikes heated up significantly, and the US dollar strengthened. Independent analyst Tai Wong said: "Chairman Warsh made clear that inflation has not yet shown a material slowdown and stressed that the US Fed 'still has work to do,' a signal that triggered a sharp sell-off in the gold market. Although this may still be a 'more thunder than rain' communication strategy, it was enough for the market to view the September meeting as a toss-up between a rate hike and a pause." Warsh's remarks were his closest public acknowledgment to date that further rate hikes may be needed to ease price pressures. In his speech, he noted that if policymakers cannot be confident that underlying inflation is steadily returning to the 2% target, the US Fed "still has work to do." As a result, traders quickly increased their bets on a September rate hike. (Jin10 Data App)
Eugene Epstein, head of trading and structured products at Moneycorp in Stamford, Connecticut, said of Fed Chairman Warsh's remarks: "We will see what impact this has on next month's meeting. But I feel like this is now the fourth, maybe even the fifth, time I have watched him give the same speech. Because frankly, he is indeed saying that they will focus on inflation. But he will not provide forward guidance, and inflation is not heading in the direction they want." (Jin10 Data App)
In addition, US job growth in the year through March was milder than previously reported, highlighting the downward trend in the labour market and helping explain why the US Fed cut interest rates in 2025 despite persistent inflation. According to preliminary benchmark revision data released Friday by the US Bureau of Labor Statistics, nonfarm payrolls may be revised down by 79,000, a decline of 0.1%. Final data will be released early next year. (Jin10 Data App)
Economists at Deutsche Bank expect the US Fed to deliver 25-basis-point rate hikes in each of September and December. Fed Chairman Warsh stressed in his Jackson Hole speech the need to bring inflation back to the 2% target and sent a clearly hawkish signal. Deutsche Bank believes the bar to avoiding a 25-basis-point rate hike in September is already high unless upcoming economic data are "clearly weaker than expected." The market also quickly raised its rate-hike bets: CME data show that the probability of cumulative rate hikes reaching 50 basis points or more by December rose to 51%, from only 29% a day earlier; the probability of cumulative rate hikes of 25 basis points was 38%, and the probability of holding rates unchanged was only 11%. After Warsh's speech, market bets on a September rate hike also heated up noticeably.(Jin10 Data App)
On the macro front:
This week will bring releases of China's August official manufacturing PMI, Germany's August CPI m/m preliminary, the US August Dallas Fed business activity index, China's August RatingDog manufacturing PMI, the UK August Nationwide house price index m/m, Switzerland July real retail sales y/y, France's August final manufacturing PMI, Germany's August final manufacturing PMI, France's August final manufacturing PMI, Germany's August final manufacturing PMI, the eurozone August final manufacturing PMI, the UK August final manufacturing PMI, UK July mortgage approvals, the eurozone August CPI y/y preliminary, the eurozone August CPI m/m preliminary, the eurozone July unemployment rate, the US August S&P Global manufacturing PMI final, the US August ISM manufacturing PMI, US July JOLTS job openings, US July construction spending m/m, Australia Q2 GDP y/y, New Zealand's interest rate decision due September 2, US August ADP employment change, Canada's interest rate decision due September 2, US July factory orders m/m, China's August RatingDog services PMI, Switzerland August CPI m/m, France's August final services PMI, Germany's August final services PMI, the eurozone August final services PMI, the UK August final services PMI, the eurozone July PPI m/m, US August Challenger job cuts, US initial jobless claims for the week ending August 29, the US July trade balance, the US August S&P Global services PMI final, the US August ISM non-manufacturing PMI, the eurozone July retail sales m/m, Canada's August employment change, the US August unemployment rate, US August seasonally adjusted nonfarm payrolls, US August average hourly earnings y/y, US August average hourly earnings m/m, and the US August Global Supply Chain Pressure Index, among other data.
In addition, other events to watch this week will include: the Group of Twenty (G20) finance ministers and central bank governors meeting, which will run through September 1; the 2026 SCO Council of Heads of State meeting; the Reserve Bank of New Zealand's rate decision and monetary policy statement; the Bank of Canada's rate decision; a monetary policy press conference by Bank of Canada Governor Macklem and Senior Deputy Governor Rogers; the US Fed's Beige Book; an interview with US Fed Governor Waller; opening remarks by 2026 FOMC voter and Cleveland Fed President Hammack at the "Fed Communities" event; and a speech by Bank of England Governor Bailey.
It is worth noting that due to the UK Summer Bank Holiday, the LME and the London Stock Exchange will be closed next Monday.
Crude Oil:
In overnight trading last Friday, both oil futures fell, with US crude down 0.11% and Brent crude down 0.26%. On the weekly chart, US crude futures fell 4.16%, while Brent futures fell 4.73%. The market weighed the guidance from the Jackson Hole remarks on the Fed's rate path and the outlook for navigation through the Strait of Hormuz.
On August 28 local time, Iran's Islamic Revolutionary Guard Corps Navy said in a statement that US officials' claims about the opening of the Strait of Hormuz were lies, intended only to control oil prices and conceal their failure. The statement stressed that the Revolutionary Guard's control over this strategic waterway was absolute. Iran has ordered that no vessels attempting to transit the Strait of Hormuz without coordinating with Iran be allowed to pass. The Revolutionary Guard navy said this action would continue until the US completely ended its military operations against Iran and fulfilled its due obligations. (CCTV)(Jin10 Data APP)
On August 28 local time, Iranian President Pezeshkian said regarding the current negotiations with Oman over the Strait of Hormuz that Oman initially supported Iran and later adopted a more reserved stance, but in recent meetings the two sides reached consensus again and agreed to reopen the strait's shipping lane under a coordinated plan. He stressed that Iran is now working to ensure that if the shipping lane is reopened under a specific framework, the US must also fulfill its obligations. These obligations include lifting the blockade and sanctions, unfreezing Iranian funds, and ending Israel's hostile actions in Lebanon. He also mentioned that Iran will open the Strait of Hormuz based on its own national policy. "Opening the Strait of Hormuz is consistent with the framework set out in the Islamabad Memorandum of Understanding, has been accepted by all parties, and must be implemented." In addition, Pezeshkian said Iran is reaching consensus on how to interact with its neighbors and forming a common vision. (CCTV)
In addition, according to Turkish media reports, the foreign ministers of the UK, Germany, France, Egypt, Saudi Arabia, Pakistan, and Turkey will hold a meeting in Istanbul on Sunday. The meeting was initiated by Germany and Turkey, with topics including ways to ensure freedom of navigation in the Strait of Hormuz and the regional security situation. Participating countries hope the meeting can send a signal to the US emphasizing the need to continue negotiations with Iran. (Jin10 Data APP)
The US Energy Information Administration (EIA): US oil production is expected to average 13.83 million barrels per day in August, up slightly from 13.82 million barrels per day in July; it is expected to average 13.77 million barrels per day in September.(Jin10 Data APP)
The US government is seeking to acquire a major stake in Venezuela’s oil reserves, according to people familiar with the matter. The Pentagon is in talks with energy investor Alejandro Betancourt about a potential partnership involving as many as 17 oil fields spanning Venezuela’s main oil-producing regions, including the Junín region of the Orinoco Heavy Oil Belt and fields around Lake Maracaibo. Options under discussion include having investment overseen by the Pentagon’s Office of Strategic Capital (OSC), and possibly even the US securing a lease of up to 100 years. Washington currently effectively controls Venezuelan oil sales and has already relaxed sanctions to allow US companies to enter. As the US-Iran war disrupts Middle East supply and pushes up global energy prices, the US hopes to accelerate the restoration of Venezuelan oil production. However, the OSC has no clear authority to directly hold project equity, and the related plans are expected to trigger legal and political disputes in both the US and Venezuela.(Jin10 Data APP)
US President Trump announced on the 28th in a social media post that the US has reached an agreement with Venezuela to gain “majority control” over more than 65 billion barrels of Venezuela’s proven oil reserves. Trump said the US and Venezuela worked together, through cooperation with private enterprises, to gain “majority control” over more than 65 billion barrels of Venezuela’s proven oil reserves, and that US taxpayers would bear no cost for this. Trump said the deal “will more than double US oil reserves, significantly boost oil supply, and significantly lower US gasoline prices for a long time to come.” However, Trump did not disclose the specific details of the agreement, and the White House has not yet issued any formal announcement on it.(Jin10 Data APP)
Recommended reading: