While Lithium Beneficiation Advances, Zimbabwe's Chrome Sector Still Awaits Its Own Toll-Processing Model

Published: Aug 7, 2026 21:42

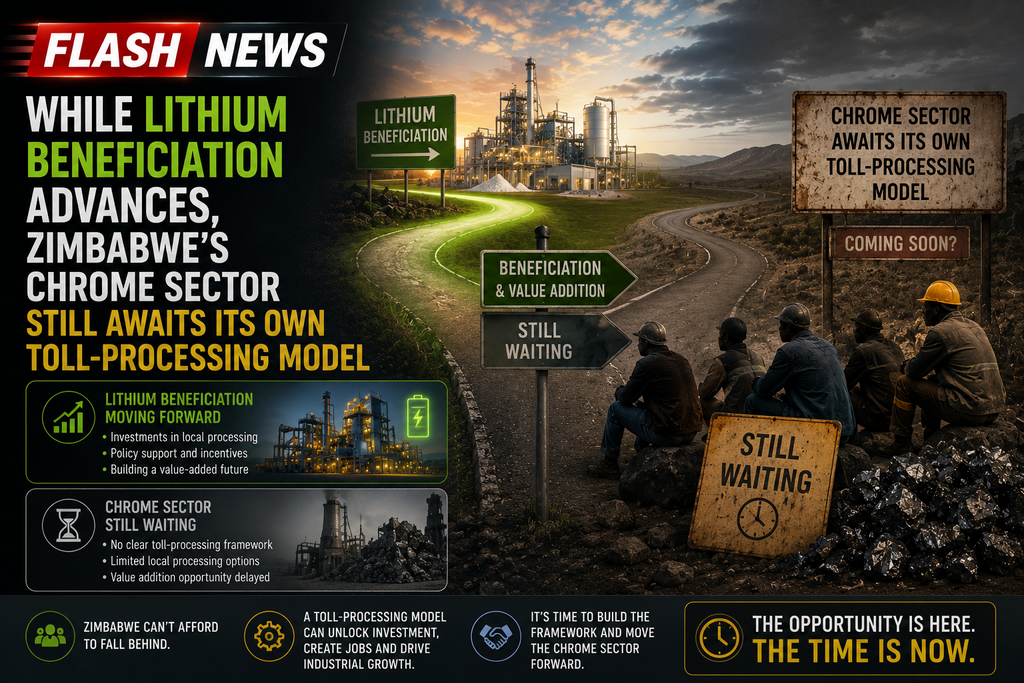
[SMM Express] More than six weeks after Zimbabwe's Mines Minister Dr Polite Kambamura promised "very soon" to roll out targeted policy interventions for the chrome sector — including a toll-processing model allowing small-scale miners to process ore for a fee rather than sell it to foreign-owned smelters — chrome producers say they are still waiting. Speaking during a technical media tour of Prospect Lithium Zimbabwe in Goromonzi on 17 July, Kambamura highlighted lithium beneficiation as a policy success story, pointing to Zimbabwe's first locally produced lithium sulphate, exported from the Arcadia plant in April, alongside further lithium processing facilities under construction at Kamativi and Sinomine Bikita. Chrome, by contrast, came up in the same discussion as the sector where that model has yet to take hold for smaller producers.

Shelton Lucas, business development director at Naivo Mining — which operates chrome, antimony and tungsten projects in Mashava, Ngezi and Kadoma, and who also chairs the Chrome Miners Association of Zimbabwe — said his company remains unable to capture the value of its own raw chrome. "For our raw chrome, we are now forced to sell to local Chinese smelters where they underpay us," Lucas said, adding that unlike antimony, where he has the resources to build a value-addition plant, the cost of chrome processing infrastructure remains prohibitive. His comments echo concerns he raised in early June, when he described local buying prices for chrome ore — then around US$70 per tonne, against international CIF China values several times higher — as reflecting a "predatory price regime." At the time, Kambamura pointed to an existing MMCZ fund intended to capacitate small-scale chrome miners and said he would soon announce policy interventions, including toll processing through government-linked facilities such as ZimAlloys.

Zimbabwe's broader mining outlook remains strong: the Chamber of Mines projects 10% sector growth for 2026, with export earnings potentially reaching US$7.5–11 billion, and the Ministry has separately outlined plans for regional beneficiation hubs that would let chrome-producing areas specialize in ferrochrome and chromium alloys. But the gap between that national-level ambition and the lived experience of small-scale chrome producers, still selling raw ore to a limited pool of local smelter buyers more than six weeks after relief was first promised, illustrates a recurring theme in Zimbabwe's beneficiation drive: policy announcements and on-the-ground implementation are not always moving at the same pace, even as the government's own flagship example — lithium — demonstrates what a fully realized beneficiation pathway can look like.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Premier African Minerals Flags US$19.1 Million Funding Need for Zulu Lithium-Tantalum Project​
14 hours ago
Premier African Minerals Flags US$19.1 Million Funding Need for Zulu Lithium-Tantalum Project​
Read More
Premier African Minerals Flags US$19.1 Million Funding Need for Zulu Lithium-Tantalum Project​
[SMM Flash] Premier African Minerals has identified an estimated US$19.1 million funding requirement through December 31, 2027, as it seeks additional capital for its Zulu Lithium and Tantalum Project in Zimbabwe and other corporate obligations. The company has called a general meeting for September 23, where shareholders will vote on resolutions providing additional share-issuance authority. Premier said its available funds are limited and warned that failure to secure further financing could materially affect the Zulu project and the wider group.​ The proposed authorities include the potential issuance of up to 58.63 billion new shares to provide funding flexibility, alongside separate provisions covering creditor settlements and conversion rights. The announcement highlights continued financing pressure surrounding Zulu as Premier works to optimise operations and progress the project towards sustainable production. For the tantalum market, securing sufficient capital will be important to Zulu’s ability to develop its prospective tantalum-bearing output, although the US$19.1 million represents an estimated funding requirement rather than financing already secured.
14 hours ago
[SMM Chromium Flash] Global Chrome Ore Departures Surge 83.99% WoW to 691,800 mt, Maputo and Richards Bay Both Rebound
14 hours ago
[SMM Chromium Flash] Global Chrome Ore Departures Surge 83.99% WoW to 691,800 mt, Maputo and Richards Bay Both Rebound
Read More
[SMM Chromium Flash] Global Chrome Ore Departures Surge 83.99% WoW to 691,800 mt, Maputo and Richards Bay Both Rebound
[SMM Chromium Flash] Global Chrome Ore Departures Surge 83.99% WoW to 691,800 mt, Maputo and Richards Bay Both Rebound
Global chrome ore departures from major export ports totaled 691,800 mt in the week ended September 4, up 83.99% week-on-week, according to SMM's latest data. The sharp rebound follows two consecutive weeks of decline and marks the strongest weekly departure volume recorded in the current data series, with gains registered across nearly every tracked port. Maputo continued to anchor overall volumes, with departures rising to 512,100 mt from 339,200 mt, a 50.97% increase that kept the port's share of total departures above 70%. Richards Bay returned to active shipping after recording zero departures the prior week, loading 57,800 mt, while Mersin more than doubled to 84,500 mt from 36,800 mt, its strongest weekly total in recent weeks. Beira also resumed shipments after an extended period of inactivity, recording 29,500 mt, its first departures in the current data series. On balance, the broad-based pickup across Maputo, Richards Bay, Mersin, and Beira marks a shift from the more concentrated, Maputo-led flows seen over the preceding weeks toward a more synchronized recovery across the region's ports. The modest gap between combined major-port volumes and the global total, roughly 7,900 mt, reflects smaller contributions from non-major loading points.
14 hours ago
[SMM Chromium Flash] China's Chrome Ore Port Inventory Rises to 5.22 Mt as of Sep 4, Led by Tianjin Port Build
15 hours ago
[SMM Chromium Flash] China's Chrome Ore Port Inventory Rises to 5.22 Mt as of Sep 4, Led by Tianjin Port Build
Read More
[SMM Chromium Flash] China's Chrome Ore Port Inventory Rises to 5.22 Mt as of Sep 4, Led by Tianjin Port Build
[SMM Chromium Flash] China's Chrome Ore Port Inventory Rises to 5.22 Mt as of Sep 4, Led by Tianjin Port Build
As of September 4, 2026, China's total chrome ore inventory at ports stood at 5.219 million mt, up 191,000 mt (+3.80%) from 5.028 million mt on August 28. Tianjin Port, China's dominant chrome ore hub, held 4.5737 million mt, up 186,900 mt (+4.26%) week-on-week, accounting for 87.6% of the national total, up from 87.3% the prior week. The remaining ports collectively held just 645,300 mt (+42,000 mt, +0.66% WoW), essentially flat. Almost the entirety of this week's national inventory build was therefore concentrated at Tianjin, reaffirming its role as the primary discharge and warehousing hub for seaborne ore serving Inner Mongolia and other northern ferrochrome smelting clusters. The build reflects a supply side that continues to outrun downstream offtake. South Africa remains the overwhelming source of China's ore, with H1 2026 imports up nearly 30% YoY and exports staying elevated as Transnet rail reforms and growing use of the Maputo corridor via Mozambique ease logistics bottlenecks that had previously capped shipment volumes. Zimbabwean supply has also surged (+44% YoY in H1), adding further to arrivals. On the demand side, ferrochrome producers have kept operating rates high even as high-carbon ferrochrome prices eased roughly 100 yuan/mt in August on oversupply and sluggish retail sales, while China's stainless steel sector, despite entering its traditional September-October peak season, is seeing mills resume post-summer-maintenance output faster than downstream orders are recovering, with July stainless exports down 13.2% MoM. With ore arrivals holding firm and consumption growth lagging, port stocks, concentrated at Tianjin, look set to stay well-supplied into the Mid-Autumn Festival and National Day holiday period.
15 hours ago
[SMM Express] More than six weeks after Zimbabwe's Mines Minister Dr P - Shanghai Metals Market (SMM)


