[SMM Analysis] Indonesian nickel ore quota headlines whipsaw China's stainless futures

Published: Aug 7, 2026 17:49
SMM Weekly Stainless Steel Futures Review — week of July 27 – July 31, 2026. Conflicting RKAB supplementary quota signals and a hawkish Fed swing the benchmark contract to a RMB 30/mt gain in the week of August 3–7.

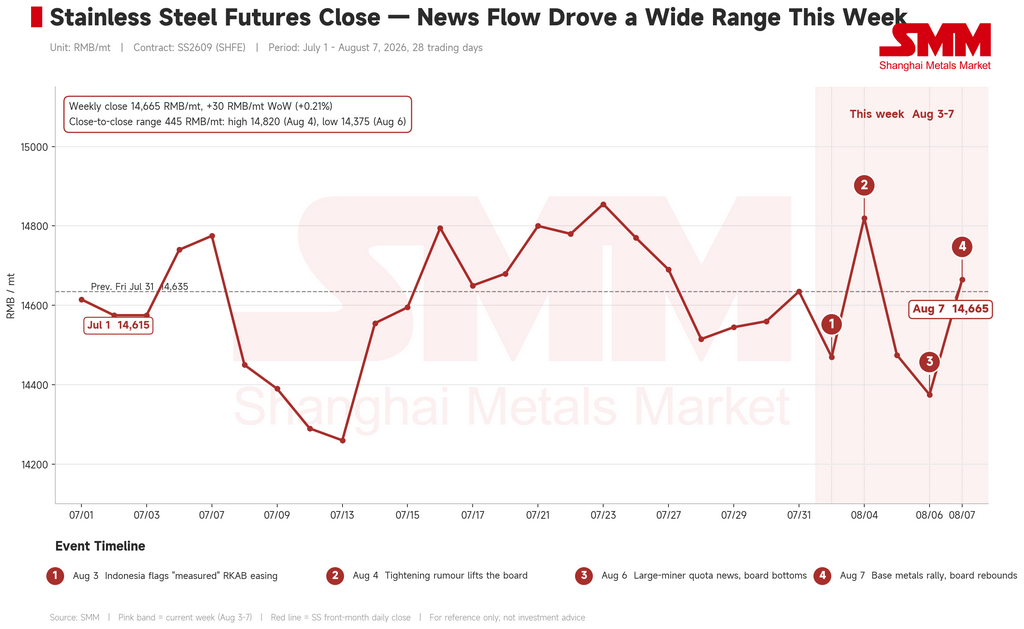
China's benchmark stainless steel futures contract (SS2609 on the Shanghai Futures Exchange) closed the week at RMB 14,665/mt (about $2,160/mt), up RMB 30/mt or 0.21% week on week, after a session-to-session range that saw the contract settle as low as RMB 14,375/mt (about $2,117/mt) on Thursday. The week's direction was set almost entirely by Indonesian nickel ore policy headlines rather than by stainless fundamentals.
Indonesian quota headlines drove the tape in both directions

Indonesia's RKAB system sets annual production and sales quotas for miners; a supplementary approval round is currently underway, and it governs how much laterite nickel ore reaches the market in the second half. On August 3, Indonesia's energy and mineral resources minister said the government would apply a "measured relaxation" to RKAB, and the market initially traded it as tightening: SHFE nickel jumped to RMB 132,650/mt (about $19,535/mt) on August 4, pulling stainless up with it.
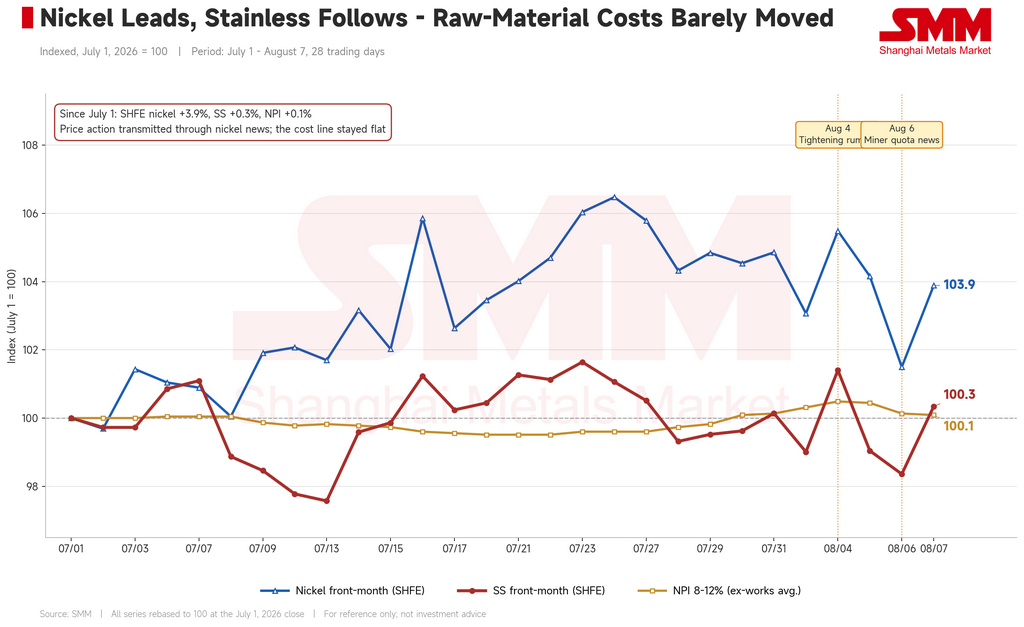
Two days later the trade reversed. Reports that a major Indonesian miner expects a large supplementary allocation sent SHFE nickel down to RMB 128,230/mt (about $18,884/mt), and stainless followed to its weekly low. The same policy thread was priced in opposite directions within four sessions.

Macro stayed a background drag

The US Federal Reserve held rates steady but kept a hawkish tone, with several officials openly discussing a hike. US July ADP private payrolls came in at just 44,000, well below the 70,000 consensus, which pulled hike expectations back and softened the dollar mid-week before caution returned ahead of the payrolls report.

Destocking against the seasonal grain
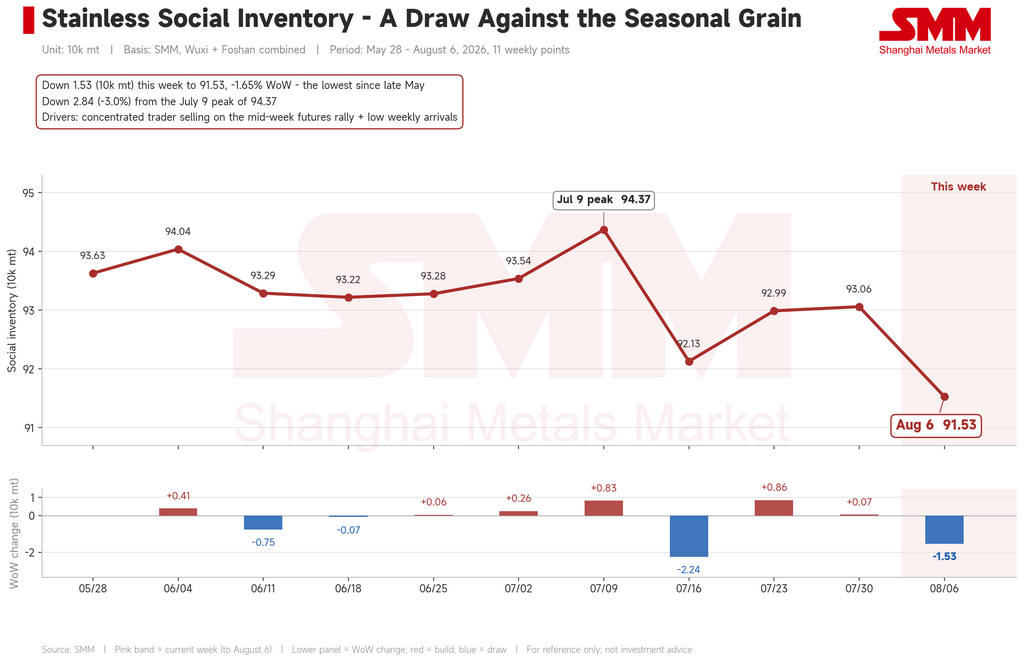
Combined social inventory in Wuxi (Jiangsu) and Foshan (Guangdong), China's two main stainless trading and distribution hubs, fell to 915,300 mt as of August 6, down 1.65% from 930,600 mt a week earlier. That reverses the recent mild build and is unusual in the low-demand summer season. Spot prices held up far better than futures, with mill list prices steady and trader quotes cut only modestly on down days.

Costs split; mill margins narrow
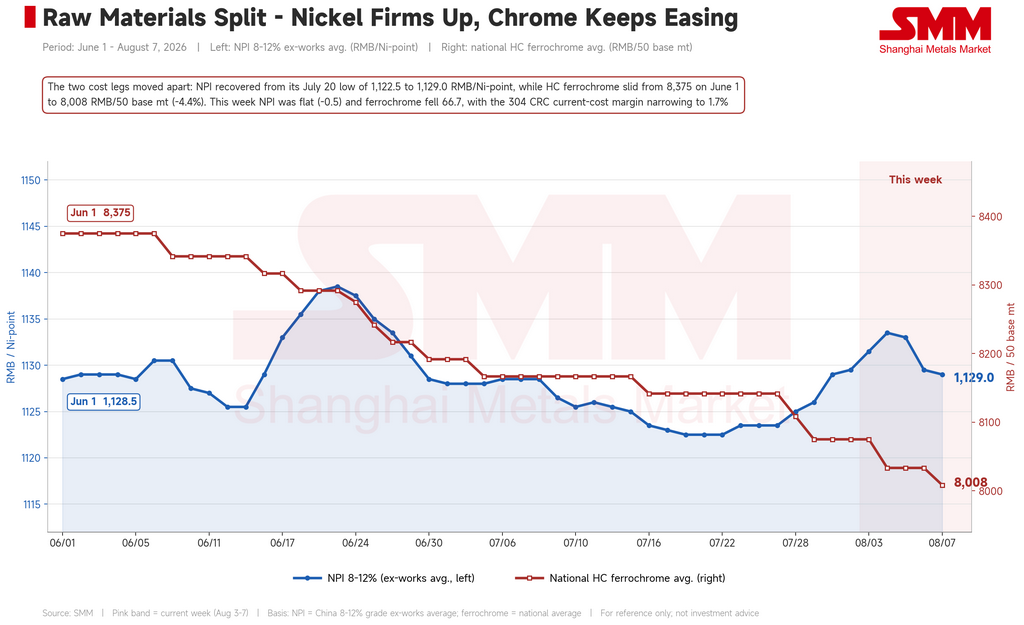
Nickel Pig Iron (NPI) was essentially flat at RMB 1,129 per nickel point (about $166.3), while high-carbon ferrochrome slipped to RMB 8,008 per 50 base mt (about $1,179). With finished prices falling faster than the raw material basket, the 304 cold-rolled coil margin narrowed to 1.7% on current-cost accounting — thinner, but still positive, so no production cuts are being forced.

Outlook

Range-bound trading is the base case near term. The upside is capped by seasonal demand weakness and rising August output as previously idled mills restart; the downside is limited by firm nickel-linked costs and inventories that are no longer building.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
High-Grade NPI Prices Drop Further as Stainless Steel Weakness Persists
Sep 4, 2026 17:44
High-Grade NPI Prices Drop Further as Stainless Steel Weakness Persists
Read More
High-Grade NPI Prices Drop Further as Stainless Steel Weakness Persists
[SMM Nickel Flash] On September 4, spot high-grade NPI weakened further, with a clear signal of downward price exploration. The continued weakness in stainless steel dragged down NPI pricing, and some traders chose to front-run shipments, intensifying the divergence in market sentiment.
Sep 4, 2026 17:44
SMM Nickel Flash: High-Grade NPI Sentiment Weakens, Downstream and Upstream Factors Decline
Sep 4, 2026 17:43
SMM Nickel Flash: High-Grade NPI Sentiment Weakens, Downstream and Upstream Factors Decline
Read More
SMM Nickel Flash: High-Grade NPI Sentiment Weakens, Downstream and Upstream Factors Decline
[SMM Nickel Flash] On September 4, the SMM high-grade NPI market sentiment factor stood at 1.75, down 0.02 MoM. The upstream sentiment factor for high-grade NPI was 1.84, down 0.03 MoM, while the downstream sentiment factor for high-grade NPI was 1.65, down 0.02 MoM. Weakness in spot high-grade NPI further intensified.
Sep 4, 2026 17:43
China and Indonesia See Squeezed NPI Profitability Amid Rising Costs and Stable Nickel Ore Prices
Sep 4, 2026 17:42
China and Indonesia See Squeezed NPI Profitability Amid Rising Costs and Stable Nickel Ore Prices
Read More
China and Indonesia See Squeezed NPI Profitability Amid Rising Costs and Stable Nickel Ore Prices
[SMM Nickel Flash] China's nickel ore prices remained stable this week, while Indonesian nickel ore prices edged lower. However, driven by the continued rise in domestic coke prices, auxiliary material costs for smelting rose in both China and Indonesia. Combined with ocean freight rates from Indonesia to China remaining at high levels, multiple factors squeezed smelting margins, putting profitability of NPI production in both China and Indonesia under pressure this week.
Sep 4, 2026 17:42
[SMM Analysis] Indonesian nickel ore quota headlines whipsaw China's stainless futures - Shanghai Metals Market (SMM)