

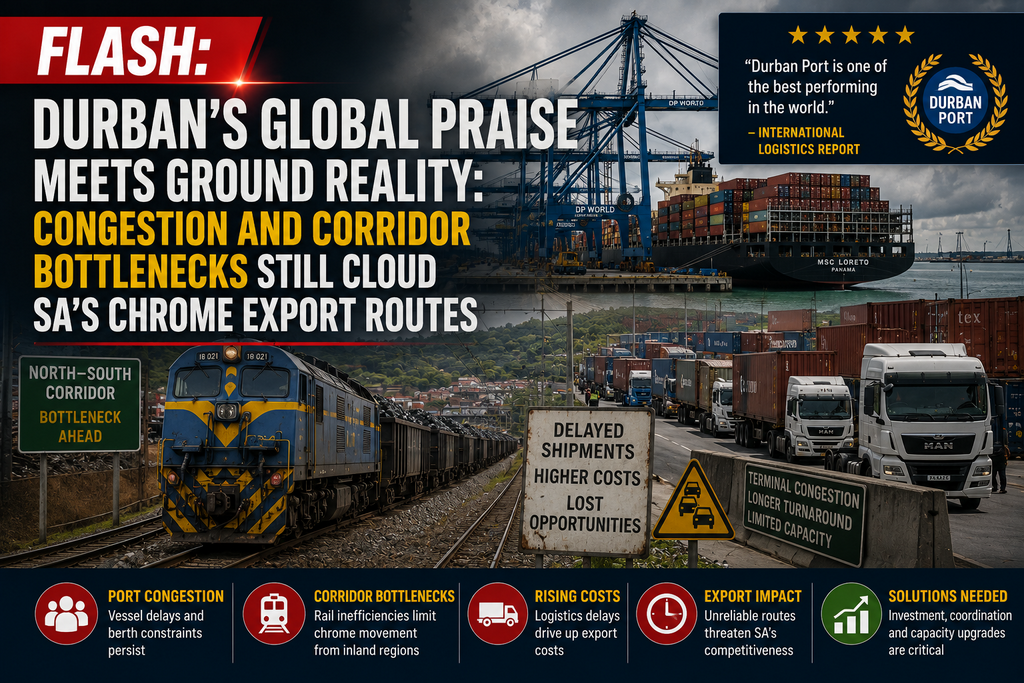
South Africa's ports are sending mixed signals for chrome ore and ferrochrome exporters this week. Fresh recognition of Durban's turnaround is running alongside renewed congestion at the terminal level and worsening delays along the road corridors that carry much of the country's bulk mineral cargo to the coast.
Durban's turnaround recognized, but queues are lengthening again
The Port of Durban, the primary gateway for South African chrome ore and ferrochrome shipments, was recently ranked the world's most-improved port by the World Bank and S&P, with its performance score surging 479 points in 2025. Transnet says its eight commercial seaports handled more than 300 million tonnes of cargo in the 2025/26 financial year, a 9% rise in vessel traffic and the strongest cargo throughput growth since 2011/12.
That progress has not stopped local congestion from creeping back up. Published vessel-waiting-time data tracked in early July showed Durban's delay indicator climbing to roughly four days, up from around two days the previous week, while Coega/Ngqura, another route used for bulk exports, held at about five days. Cape Town was separately ranked South Africa's worst-performing port in the same World Bank/S&P assessment that praised Durban.
Corridor and border delays offset port-level gains
A significant share of South African chrome ore and concentrate is trucked to the coast rather than moved by rail, making inland corridors as important as the ports themselves. A Trademark Africa-commissioned assessment found that Durban's improved performance is not translating into faster end-to-end transit times, because border crossings along the North-South Corridor remain a persistent bottleneck.
Average South African border-crossing times deteriorated by roughly 23% week-on-week to about 9.6 hours in early July, even as Lebombo (the main crossing on the Maputo Corridor used for chrome bound for Maputo harbour) saw truck volumes ease slightly and queue times improve. Further north, congestion at the Kasumbalesa crossing into the DRC has cut daily vehicle clearances by more than half, illustrating how regional border capacity, not just port throughput, shapes actual delivery times for African mineral exporters.
Investment and reform response
South Africa's transport ministry has extended the tenure of Transnet's turnaround board by six months, to January 2027, to allow more time to complete the appointment of a permanent replacement board and continue the state logistics group's recovery plan. Durban Container Terminal Pier 2, the port's largest container terminal, is set for an 11 billion rand investment from Philippines-based ICTSI as part of Transnet's wider push toward private-sector terminal operation. Cape Town has also expanded private participation, with nine of its eleven terminals now privately operated.
On the alternative-route side, Maputo has launched Mozambique's first Port Community System, a digital platform intended to connect shipping lines, customs, transporters and other port users on a single system. If effectively implemented, it could strengthen Maputo's position as an alternative export gateway for South African chrome moved via the Maputo Corridor, though officials note the benefit will depend on execution rather than the platform's existence alone.
Why it matters for chrome and ferrochrome trade
Bottom line: Global rankings point to a genuine Transnet turnaround, but week-to-week congestion data and deteriorating border-crossing times suggest chrome and ferrochrome exporters should still budget for variable lead times, particularly on Maputo Corridor-bound cargo, rather than assume headline port improvements have fully resolved South Africa's export logistics constraints.
NOTE: Compiled by SMM Africa (Zambia office) from Business Day, EWC (Exporters Western Cape) Logistics News Update, and Transnet/World Bank-S&P port performance data. Figures reflect the most recently available public reporting as of 22 July 2026 and are subject to change as Transnet and corridor authorities issue updates.


