High Raw Material Costs + Weak Consumption: Secondary Lead Supply & Prices Under Pressure

Published: Jun 9, 2026 20:25
Overall, the secondary lead market will remain in a pattern of "weak cost support and strong consumption suppression" in the short term. Smelter production resumptions in June will find it difficult to fully offset previous cuts, with the supply side showing marginal improvement but remaining tight. Lead prices will continue to fluctuate weakly.

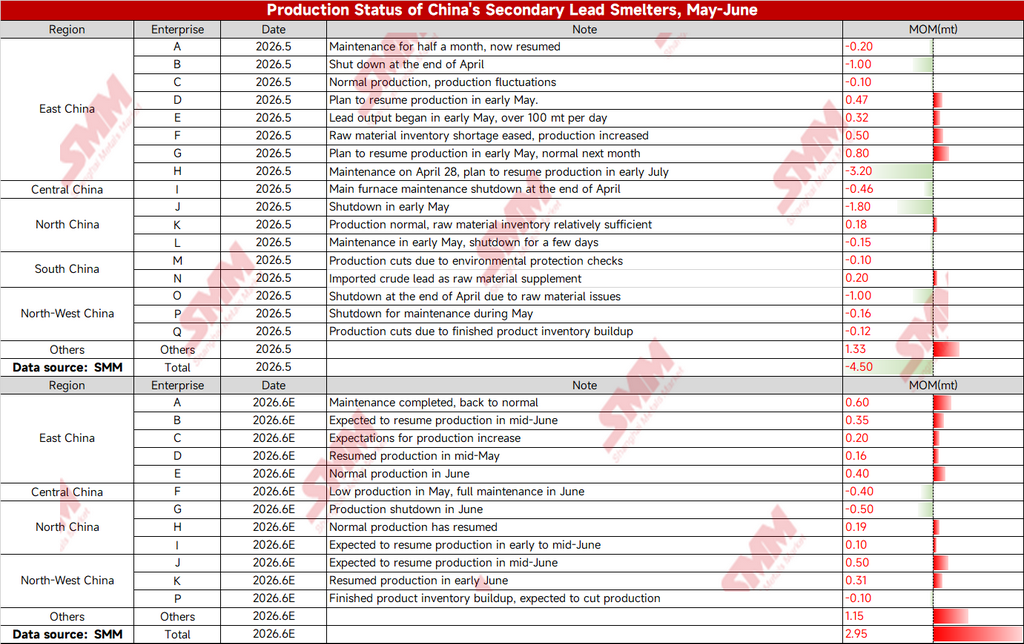
Data from SMM shows that in May, the MoM impact on refined lead from secondary lead enterprises in China totaled -45,000 mt, with the supply contraction widening further. Smelters in east China, central China, and north China, affected by production halts, maintenance, raw material shortages, and environmental protection checks, saw production cuts continue to spread.
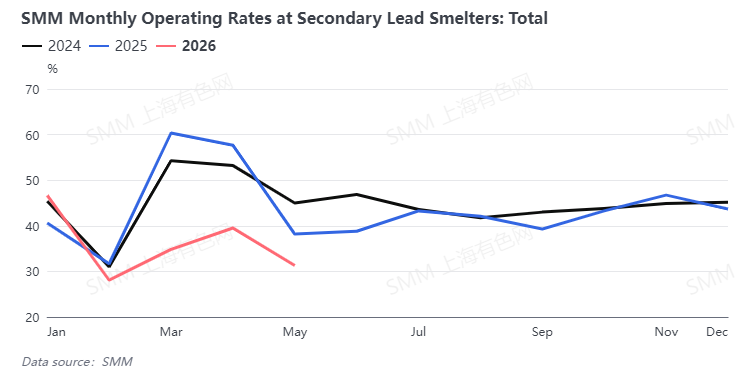
The enterprise operating rate declined significantly YoY, falling to a low level seen in recent years.

Raw material side, although the average price of scrap EV batteries retreated from highs, it remained at a relatively high level of 9,725 yuan/mt.
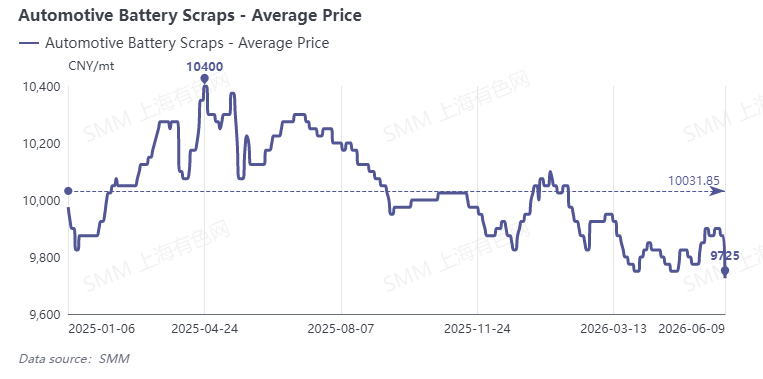
Elevated procurement costs continued to squeeze smelter margins, and coupled with finished product inventory buildup at some enterprises, the willingness for passive production cuts strengthened further.

While June production schedules indicate supply is expected to recover MoM, with the total MoM impact on refined lead at +29,500 mt and clear expectations for production resumptions and increases among smelters in east China and northwest China, the pace of recovery remains highly dependent on raw material arrivals. The tight supply pattern in the scrap battery recycling sector persists, limiting supply elasticity.
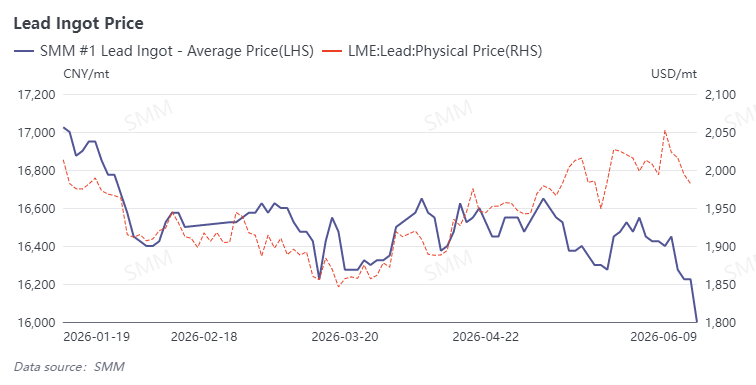
Consumption side, the downstream lead-acid battery market is in the traditional off-season, with sluggish end-use demand. China's spot lead prices continued to fluctuate downward, with the average SMM #1 lead ingot price having fallen below 16,200 yuan/mt. LME lead prices were also in the doldrums, with both domestic and overseas markets lacking clear upward momentum.
Overall, the secondary lead market will remain in a pattern of "weak cost support and strong consumption suppression" in the short term. Smelter production resumptions in June will find it difficult to fully offset previous cuts, with the supply side showing marginal improvement but remaining tight. Lead prices will continue to fluctuate weakly. Going forward, close attention should be paid to improvements in raw material arrivals and the recovery of end-use consumption, as both will jointly determine the pace of secondary lead supply recovery and the trajectory of lead prices.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
13 hours ago
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
Read More
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
[SMM Analysis] Detailed Data on China's Sulphuric Acid Production in August
NBS data shows that China's sulphuric acid (100% equivalent) production in August was 7.984 million mt, down 308,000 mt from 7.676 million mt in July, a YoY decline of 15.5%. The cumulative production of sulphuric acid (100% equivalent) in 2026 was 68.141 million mt, a cumulative YoY decline of 4.6%.
13 hours ago
August lead concentrate imports pulled back, with limited recovery expected in September [SMM Analysis]
16 hours ago
August lead concentrate imports pulled back, with limited recovery expected in September [SMM Analysis]
Read More
August lead concentrate imports pulled back, with limited recovery expected in September [SMM Analysis]
[Lead Concentrate Imports Pull Back in August, Limited Recovery Expected in September] According to the latest customs data, China imported 87,000 mt in physical content of lead concentrates in August 2026, down 28,200 mt in physical content or 24.44% MoM and down 35.35% YoY. Cumulative lead concentrate imports from January to August totaled 906,300 mt in physical content, down 2.3% YoY.
16 hours ago
[SMM Flash] Sulphuric acid prices in some regions dropping below 1,000 yuan/mt
18 hours ago
[SMM Flash] Sulphuric acid prices in some regions dropping below 1,000 yuan/mt
Read More
[SMM Flash] Sulphuric acid prices in some regions dropping below 1,000 yuan/mt
[SMM Flash] Sulphuric acid prices in some regions dropping below 1,000 yuan/mt
Since 10 July, SMM Chinese sulfuric acid price index from Copper smelters has declined for 11 consecutive weeks on a weekly basis. This weekend, sulphuric acid prices were further reduced in some regions, with the ex-works price of 98% smelting acid falling below 1,000 yuan/mt. However, demand from the fertiliser industry has yet to show any clear improvement, and there are no signs that exports of sulphuric acid and phosphate fertiliser can be restarted, leaving the market dominated by a strong wait-and-see sentiment.
18 hours ago

