
Ammonium Perrhenate Procurement Analysis

Published: May 28, 2026 18:49 (GMT+8)
During December 2025 to May 2026, the CAS Institute of Metal Research completed 2,800 kg of ammonium perrhenate procurement amid concentrated supplier supply and a nearly 90% six-month price surge, with tight market supply driven by manufacturers’ inventory hoarding and robust institutional and corporate demand, keeping prices upward.

I. Overall Overview

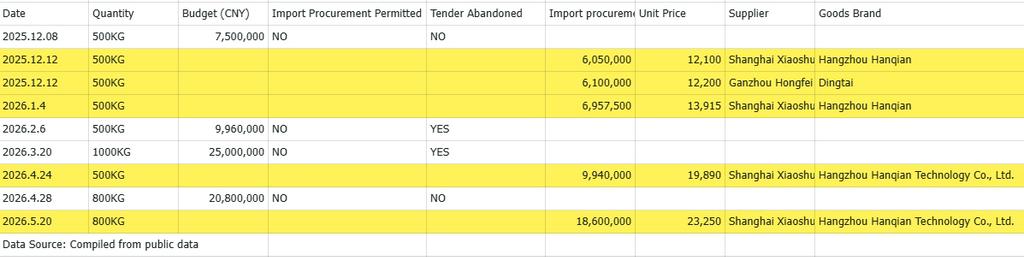
During the statistical period from December 8, 2025 to May 20, 2026, the Institute of Metal Research, Chinese Academy of Sciences launched a total of 10 procurement batches. Among them, 5 batches were successfully awarded and moved to delivery execution; 2 batches resulted in failed bids. Another 2 batches had budgets recorded but no final transaction data available, remaining pending or incomplete.

II. Key Procurement Milestones and Delivery Details

The total weight of delivered goods under completed procurement during the period reached approximately 2,800 kilograms. Detailed transaction information for each batch is as follows:

December 12, 2025 (2 batches)Two separate procurements were completed, each with a quantity of 500 kg. The unit price stood at RMB 12,100 per kg (total value: RMB 6.05 million) and RMB 12,200 per kg (total value: RMB 6.10 million) respectively.

January 4, 2026A 500 kg procurement was finalized at a unit price of RMB 13,915 per kg, with a total value of RMB 6.9575 million.

April 24, 2026A 500 kg procurement was completed at a unit price of RMB 19,890 per kg, with a total value of RMB 9.94 million.

May 20, 2026A large-scale procurement of 800 kg was executed at a unit price of RMB 23,250 per kg, with a total value of RMB 18.6 million.
III. Core Trend Analysis

High Concentration of Suppliers

Transaction records show that Shanghai Xiaoshudian Chemical Technology Co., Ltd. holds a dominant position in the supply chain. This supplier secured the vast majority of awards across all 5 publicly disclosed successful batches. Additionally, the cooperation frequency and single-batch procurement volume have increased over time, with the per-batch quantity rising from 500 kg to 800 kg.

Stepped Surge in Procurement Unit Prices

The unit price of the commodity witnessed a notable stepped upward trend. The average unit price was RMB 12,150 per kg in December 2025, climbing to RMB 13,915 per kg in January 2026 and RMB 19,890 per kg in April 2026, before hitting RMB 23,250 per kg in May 2026. Within six months, the procurement price of the raw material surged by nearly 90%, almost doubling, indicating mounting upward price pressure across the upstream raw material sector.

According to statistics from SMM, China’s domestic output of ammonium perrhenate reached approximately 24,000 kg in 2025, while the consumption of rhenium metal stood at around 15,000 kg, equivalent to 21,000 kg of ammonium perrhenate. On paper, the market still saw a supply surplus. Nevertheless, actual delivery data reveals that some producers held back inventories, leading to a real market supply far below the 24,000 kg output figure.

Overall, large institutional buyers have ramped up stockpiling and continued to deplete circulating inventory. Coupled with new tender demands released by Sinopec, the supply-demand gap for high-purity ammonium perrhenate is narrowing. Prices are poised to stay firm with an upward bias, and available goods will further concentrate among core suppliers and major end-users.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Weakening cost support for silicone; DMC prices slightly lowered [SMM Silicone Weekly Review]
10 hours ago
Weakening cost support for silicone; DMC prices slightly lowered [SMM Silicone Weekly Review]
Read More
Weakening cost support for silicone; DMC prices slightly lowered [SMM Silicone Weekly Review]
[SMM Silicone Weekly Review: Cost Support for Silicone Weakens, DMC Prices Edge Down] This week, overall silicone costs pulled back, and the industry's comprehensive production costs declined accordingly. As of October 22, the average price of #421 silicon metal for silicone use in east China stood at 9,750 yuan/mt, remaining largely stable; the mainstream transaction price of #421 silicon in east China averaged 9,550 yuan/mt, down 0.52% WoW, with silicon metal prices trending downward this week. Meanwhile, methanol market prices pulled back, dragging methyl chloride costs lower in tandem. This week, the average market price of methyl chloride was 3,450 yuan/mt, down 6.76% WoW.
10 hours ago
【Flash | South Korea’s Molybdenum Flows Diverge as Concentrate Imports Fall 26%】
11 hours ago
【Flash | South Korea’s Molybdenum Flows Diverge as Concentrate Imports Fall 26%】
Read More
【Flash | South Korea’s Molybdenum Flows Diverge as Concentrate Imports Fall 26%】
South Korea imported 2,707.3 tonnes of roasted and other molybdenum concentrates in September 2026, down 25.9% YoY, SMM calculations based on customs data show. Roasted concentrate imports fell 28.8% to 1,740.0 tonnes, including 500.0 tonnes from Chile versus 1,410.7 tonnes a year earlier. Roasted concentrate exports rose 6.5% to 516.6 tonnes, mainly to Japan, India and Vietnam. Ferromolybdenum exports fell 29.2% to 1,121.1 tonnes, with shipments to China dropping from 580.0 to 70.5 tonnes. Imports of molybdenum oxides and hydroxides rose 311.0% MoM to 97.2 tonnes, although January–September volumes were down 39.2% YoY. National customs flows cannot measure Busan port throughput or warehouse spot stocks.
11 hours ago
PV Upstream Multi-Segment Stalemate Holds Steady, Module Prices Continue to Decline [SMM Weekly Review]
11 hours ago
PV Upstream Multi-Segment Stalemate Holds Steady, Module Prices Continue to Decline [SMM Weekly Review]
Read More
PV Upstream Multi-Segment Stalemate Holds Steady, Module Prices Continue to Decline [SMM Weekly Review]
[SMM Weekly Review: PV Upstream Segments Hold Steady in Stalemate, Module Prices Continue to Slide] This week, solar cell market prices remained stable overall, with quotes across all sizes unchanged WoW. Supply stayed at low levels and inventory continued to draw down. The market maintained a balance between cost support and demand divergence, with the tug-of-war between upstream and downstream persisting. Prices are expected to remain stable in the short term. In terms of pricing, all sizes held steady. The 183 price range remained at 0.29-0.301 Yuan/W. The 210R price range held at 0.305-0.314 Yuan/W, still dominated by exports to ex-China markets. The export window is expected to extend into early November, with supply prioritized for export orders. Available domestic supply is limited, leaving no basis for price adjustments. The 210N price range held at 0.295-0.3 Yuan/W, stabilizing after last week's raise. Although wafer producers intend to hold prices firm, the recent continued decline in silver prices has offset cost-side support, limiting upward momentum for prices. At this stage, downstream buyers are restocking at a need-based pace, with actual order negotiations locked in a stable tug-of-war. In the short term, the upstream-downstream stalemate may persist until early November, and prices across all sizes are expected to remain stable or move sideways.
11 hours ago
