SMM Ferrous Metals Salon - Hangzhou Session Successfully Held

Published: May 28, 2026 10:01 (GMT+8)

On May 26, 2026, the "2026 SMM Ferrous Salon — Hangzhou Session" event, jointly hosted by Zheshang Futures Co., Ltd. and SMM Information & Technology Co., Ltd., was successfully held. Nearly forty clients from the ferrous industry chain attended the conference, sharing and exchanging views on topics such as the current status of the ferrous industry, steel export opportunities, market trading hot topics, and steel enterprise risk management, inspiring future cooperation and trading ideas in the steel industry.

Chen Kaihang, Chief Black Series Analyst at Zheshang Futures Research Center, believes:
1. Rebar demand is declining, with supply adjusting to match demand. Electric furnace production remains resilient, while blast furnaces cannot deliver profits;
2. HRC is driven by international steel prices, but China's FOB needs to be in a price depression to gain export advantages;
3. Iron ore supply is increasing, demand is unlikely to grow, inventory is at high levels, costs are falling, and the downtrend is pronounced;
4. Coking coal speculation cannot drive steel, delivery issues persist, and risks will be greater after speculation ends;
Summary: HRC FOB determines the price ceiling of HRC futures, and the HRC-rebar spread will stay high or even continue to widen slightly. Steel raw material prices face downward pressure. Overall, the strategy for steel remains shorting on rallies. Bottom-fishing will only be feasible when blast furnace rebar production pulls back again.

SMM senior ferrous metals analyst Ding Xiaoli stated:
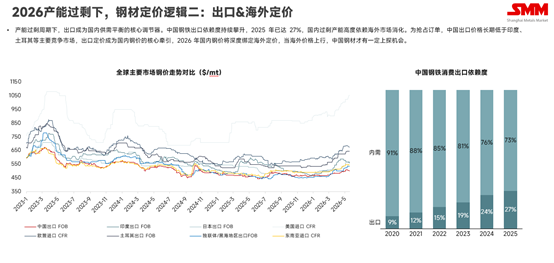
In an overcapacity cycle, exports have become the core regulator of China's supply-demand balance. China's dependence on steel exports has continued to climb, reaching 27% in 2025, with domestic surplus capacity highly reliant on markets outside China for absorption. To secure orders, China's export prices have long remained below those of major competing markets such as India and Turkey, making export pricing the core driver of domestic steel prices. In 2026, domestic steel prices will be deeply tied to ex-China pricing, and only when prices outside China rise will Chinese steel have some upside potential.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Wang Hongzhi Surveys Jilin: Expand Energy Investment, Advance New-Type Grid, Ensure Winter Power Supply
1 min ago
Wang Hongzhi Surveys Jilin: Expand Energy Investment, Advance New-Type Grid, Ensure Winter Power Supply
Read More
Wang Hongzhi Surveys Jilin: Expand Energy Investment, Advance New-Type Grid, Ensure Winter Power Supply
From September 20 to 21, Wang Hongzhi, Party Leadership Group Secretary and head of the National Energy Administration, led a team to Jilin to survey energy investment, winter peak energy and power supply, new-type power grid construction, and new fuel development. Wang Hongzhi stressed the need to expand the scale of energy investment and accelerate the construction of major energy projects. Fully advance new-type power grid construction and appropriately push forward the implementation of new-type power grid project tasks ahead of schedule. Leverage Jilin's resource advantages and actively and orderly promote the high-quality development of industries such as new energy, hydrogen energy, and green fuels. Broaden investment channels, improve service levels, and actively attract various enterprises, especially private enterprises, to participate in energy project construction. Solidly carry out all work related to winter peak energy and power supply to ensure the people stay warm through the winter. Attach great importance to workplace safety and safeguard high-quality energy development with high-level safety.
1 min ago
[CPCA: Retail sales of new energy passenger vehicles in China reached 596,000 units from September 1-20, down 9% YoY]
2 mins ago
[CPCA: Retail sales of new energy passenger vehicles in China reached 596,000 units from September 1-20, down 9% YoY]
Read More
[CPCA: Retail sales of new energy passenger vehicles in China reached 596,000 units from September 1-20, down 9% YoY]
[CPCA: Retail sales of new energy passenger vehicles in China reached 596,000 units from September 1-20, down 9% YoY]
The CPCA released data showing that from September 1-20, retail sales of passenger vehicles in China reached 878,000 units, down 22% YoY and up 8% MoM. Cumulative retail sales since the beginning of this year reached 2.593 million units, down 21% YoY. From September 1-20, retail sales of new energy passenger vehicles in China reached 596,000 units, down 9% YoY and up 14% MoM. Cumulative retail sales since the beginning of this year reached 7.27 million units, down 12% YoY. From September 1-20, the penetration rate of new energy vehicles in China's passenger vehicle retail market was 67.9%. From September 1-20, the penetration rate of new energy vehicles in wholesale shipments by passenger vehicle producers in China was 73.9%.
2 mins ago
[SMM Sheets & Plates Daily Review] Short-term sheets & plates continue to consolidate
2 mins ago
[SMM Sheets & Plates Daily Review] Short-term sheets & plates continue to consolidate
Read More
[SMM Sheets & Plates Daily Review] Short-term sheets & plates continue to consolidate
[SMM Sheets & Plates Daily Review] Short-term sheets & plates continue to consolidate
Today, the most-traded HRC contract drifted lower, closing at 3,301, down 0.18% intraday. Spot prices were mostly stable, with some markets seeing catch-up declines of 10-20 yuan/mt. In terms of supply, this week's HRC impact from maintenance was 109,700 mt, down 12,900 mt WoW. Next week's HRC impact from maintenance is 82,600 mt, down 27,100 mt WoW, leaving HRC supply relatively ample. Demand side, spot pullback room before the holiday is relatively narrow, with traders and steel mills mainly holding prices firm, and some end-users showing slightly higher stockpiling enthusiasm. Raw material side, according to an SMM survey, daily average hot metal output this week was 2.3943 million mt, down 4,800 mt WoW, with further declines likely ahead, weakening cost support. Watch for negative feedback risks after the holiday. Looking ahead, cost support is unlikely to provide a strong directional trend in the short term. Pre-holiday procurement demand is being released in some markets, and HRC social inventory is destocking. The most-traded HRC contract is expected to mainly move sideways in a narrow range in the short term.
2 mins ago