【SMM Analysis】High Costs Worsen Loss Risks, Limited Demand Release Keeps Ferrochrome Stable

Published: Mar 31, 2026 17:12 (GMT+8)
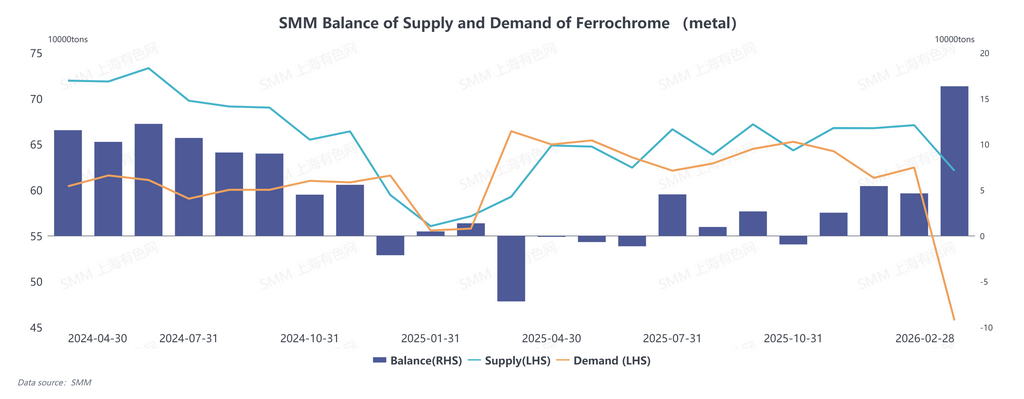
As of March 31, faced with upward cost pressure from high chromium ore prices, most ferrochrome producers have planned maintenance and output cuts recently. The supply-demand relationship of ferrochrome is expected to gradually adjust to a tight balance in the outlook.

As of March 31, retail prices of ferrochrome remained stable. Quotes in Inner Mongolia stood at 8,600–8,700 yuan per 50% basic ton, while those in Sichuan were 8,650–8,800 yuan per 50% basic ton, up 100 yuan month-on-month. The price gap between northern and southern regions narrowed, yet the spread between retail and long-term contract prices remained notable. Faced with upward cost pressure from high chromium ore prices, most ferrochrome producers have planned maintenance and output cuts recently. The supply-demand relationship of ferrochrome is expected to gradually adjust to a tight balance in the outlook.

1. Costs Keep Rising, Leading to Price Inversion

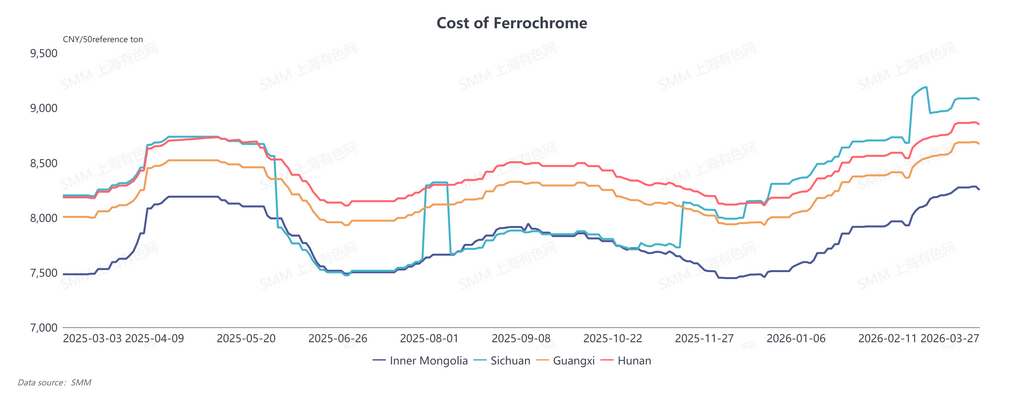
At present, the spot cost of ferrochrome in Inner Mongolia has reached 8,320 yuan per 50% basic ton, and the average cost in southern China hit 8,876 yuan per 50% basic ton, rising 3.75% month-on-month. On one hand, continuous gains in raw material chromium ore prices have driven up costs; on the other hand, frequent adjustments to power policies have intensified electricity cost pressure.
Chromium Ore

Post-holiday futures and spot prices of chromium ore have kept climbing. Geopolitical conflicts in the Middle East pushed up fuel prices and ocean freight rates, with some shipping companies imposing war surcharges, significantly raising landed costs of chromium ore, while overseas futures quotes trended steadily upward. South African fine ore was quoted at 318 USD/ton, and Turkish fine ore exceeded 400 USD/ton. Meanwhile, low-priced inventories from earlier periods have been cleared. Amid high receiving costs, domestic traders hold a strong attitude of supporting and probing price increases, keeping spot chromium ore prices at high levels.

Electricity

Policy adjustments have lifted electricity costs for ferrochrome producers. In southern China (e.g., Guizhou), electricity prices rose by 0.08–0.12 yuan per kWh, pushing up costs by nearly 400 yuan; in northern China (Inner Mongolia), settlement electricity prices increased by 0.02 yuan per kWh, lifting costs by nearly 100 yuan. Shrinking profit margins have put ferrochrome enterprises in a cost-price inversion dilemma.

2. High Downstream Scheduling but Limited Demand Release

According to SMM statistics, stainless steel output in March 2026 surged 44.65% month-on-month, generating ferrochrome demand of approximately 617,500 metal tons. Although production scheduling rebounded to historical highs, purchasing activity by downstream steel mills was muted, as most consumed pre-holiday raw material inventories, resulting in thin inquiry and transaction sentiment in the ferrochrome market. Meanwhile, major steel mills set their March steel tender prices flat at 9,245 yuan per 50% basic ton month-on-month, falling short of bullish expectations amid the traditional peak consumption season of "Golden March, Silver April". Market participants lacked confidence, leading to overall weak performance during the month.
3. Industry Maintenance Plans to Tighten Future Supply

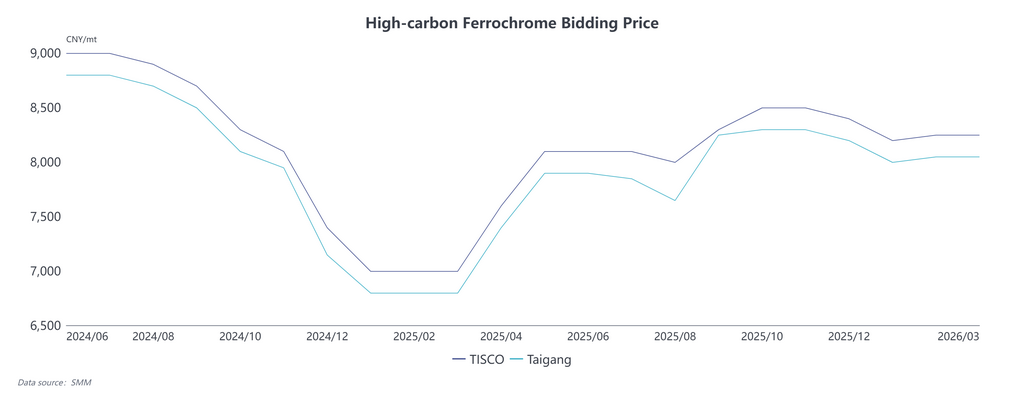
On March 20, Tsingshan and TISCO announced their April 2026 tender purchase prices for high-carbon ferrochrome at 8,395 yuan and 8,195 yuan per 50% basic ton respectively, up 150 yuan from March but below earlier bullish market forecasts. The wide spread between retail and long-term contract prices dampened market confidence. Coupled with heavy losses from soaring costs, the industry held meetings to discuss countermeasures. Some producers announced maintenance and output reduction plans, meaning China’s high-carbon ferrochrome output is likely to decline in April.

In overseas markets, negotiations over South Africa’s temporary electricity price policy have stalled. Major chromium producer Glencore stated that contract terms are unfeasible, leading to limited actual resumption of local ferrochrome production. China Customs data showed that China imported 265,100 tons of high-carbon ferrochrome in January–February 2026, down 51.6% year-on-year. It will take time for ferrochrome imports to return to average historical levels, so their impact on the domestic market will remain limited in the short term, with imports expected to stay low.

Overall, while downstream stainless steel maintains high production scheduling, ferrochrome supply is set to tighten. China’s ferrochrome supply-demand relationship is forecast to gradually shift from surplus around the Spring Festival to a tight balance.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
【Flash | Caserones Molybdenum Output Falls 66% Quarter on Quarter to Just 130 Tonnes】
2 hours ago
【Flash | Caserones Molybdenum Output Falls 66% Quarter on Quarter to Just 130 Tonnes】
Read More
【Flash | Caserones Molybdenum Output Falls 66% Quarter on Quarter to Just 130 Tonnes】
Lundin Mining Corporation reported third-quarter 2026 molybdenum production of 130 tonnes at the Caserones mine on a 100% mine basis. SMM calculations indicate declines of 65.6% quarter on quarter and 77.4% year on year. January–September output fell 29.5% to 1,097 tonnes. Molybdenum grade remained unchanged from the second quarter at 0.017%, but ore milled dropped 46.9% to 4.45 million tonnes. Two severe winter storms caused prolonged power outages and suspended operations for approximately 30 days in total. Lundin did not provide separate revised molybdenum guidance.
2 hours ago
Wafer Prices Fall Under Pressure Again as Cost Drag Weakens and Inventory Drawdown Continues, Module Prices Expected to Stop Falling [SMM Weekly Review]
10 hours ago
Wafer Prices Fall Under Pressure Again as Cost Drag Weakens and Inventory Drawdown Continues, Module Prices Expected to Stop Falling [SMM Weekly Review]
Read More
Wafer Prices Fall Under Pressure Again as Cost Drag Weakens and Inventory Drawdown Continues, Module Prices Expected to Stop Falling [SMM Weekly Review]
[SMM Weekly Review: Wafer Prices Fall Under Pressure Again, Cost Drag Weakens and Inventory Drawdown Accelerates, Module Prices Expected to Stop Falling] This week's module market changes were concentrated at both ends—individual specifications saw supplementary price cuts while inventory drawdown accelerated. On the distributed side, 182mm and HJT modules were each lowered by 0.0025 yuan/W, while all other specifications remained stable, and guidance prices were still not adjusted. On the centralized side, the three-tier quotes remained flat for the second consecutive week, with downward pressure further narrowing to individual specifications. As of now, the average price of domestic Topcon modules-182mm (distributed) is 0.6995 yuan/W; Topcon modules-210mm (distributed) average 0.718 yuan/W; Topcon modules-210R (distributed) average 0.7145 yuan/W; Topcon modules-210R high power (distributed) average 0.754 yuan/W; BC modules-210R (distributed) average 0.763 yuan/W; HJT modules-210mm (distributed) average 0.721 yuan/W. On the centralized side, 182 modules are priced at 0.691 yuan/W, 210 modules at 0.702 yuan/W, and 210R modules at 0.697 yuan/W.
10 hours ago
[SMM Chromium Flash] South Africa’s September HC FeCr Exports Reach 166,215 mt as China Takes 42% of Shipments
12 hours ago
[SMM Chromium Flash] South Africa’s September HC FeCr Exports Reach 166,215 mt as China Takes 42% of Shipments
Read More
[SMM Chromium Flash] South Africa’s September HC FeCr Exports Reach 166,215 mt as China Takes 42% of Shipments
[SMM Chromium Flash] South Africa’s September HC FeCr Exports Reach 166,215 mt as China Takes 42% of Shipments
South Africa’s high-carbon ferrochrome exports rose to 166,215 mt in September 2026, up 41.85% month-on-month from August’s 117,180 mt and the highest level of the April–September series. China took 70,075 mt, up 241.74%, lifting its share from 17.5% to 42.2%. Its gain of 49,570 mt exceeded the total net increase of 49,035 mt, as exports to all other destinations combined were essentially flat, down 0.55%. Canada fell 78.36% to 5,706 mt and the United States eased 5.88% to 24,499 mt, while “Others” rose 232.67% to 32,457 mt to become the second-largest destination. Glencore’s third-quarter report confirmed that Boshoek restarted in September and Wonderkop in October, but SMM’s reports show Chinese import demand remaining capped by ample domestic supply.
12 hours ago